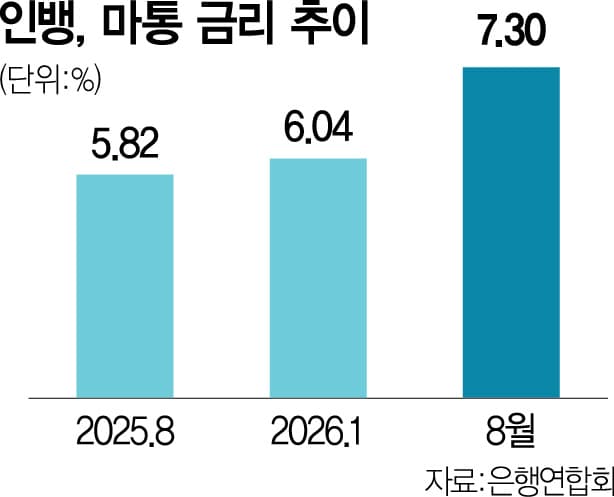
Rates on negative-balance credit lines at South Korea's internet-only banks, long seen as offering better terms than conventional lenders, are climbing quickly as market rates rise. Rates on accounts coming up for renewal are jumping by roughly 2 to 3 percentage points, pointing to a sharp increase in interest costs for low- and middle-income households and ordinary borrowers relying on these credit lines for everyday needs.
A salaried worker in his or her 40s with a credit score in the 900s, identified as A, recently applied to extend a negative-balance credit line at Kbank, according to financial industry sources on the 18th.
The borrower had been using a one-year credit line with a 50 million won ($35,000) limit. The rate rose to 8.8% from 5.2%, an increase of 3.6 percentage points, bringing it close to 9%. The higher rate takes effect Nov. 7. "This was my first renewal, and I was taken aback by how much the rate went up," A said.
Other cases have surfaced as well. In one online community post, a borrower with a perfect credit score of 1,000 said the rate on a 100 million won ($70,000) credit line rose about 1.5 percentage points to 5.89% from 4.35% upon renewal. Another borrower with a score in the high 900s was offered 6.6% at renewal, up 2.5 percentage points.
The average rate on new negative-balance credit lines at the three internet-only banks — KakaoBank (323410.KS), K bank and Toss Bank — stood at 7.30% in August, up 1.48 percentage points from 5.82% a year earlier, according to the Korea Federation of Banks. That is also 1.26 percentage points higher than the 6.04% recorded in January and the highest level in two years and three months, since May 2024, when the rate was 7.24%. By bank, KakaoBank was highest at 7.94%, followed by Toss Bank at 7.21% and K bank at 6.74%.
Over the same period, the average rate at the five largest commercial banks — KB Kookmin, Shinhan, Hana, Woori and NH NongHyup — rose 0.64 percentage point to 5.17% from 4.53%. The increase at the internet banks was about 2.3 times as large. The gap between the two groups widened to 2.13 percentage points from 1.29 percentage points.
At the internet banks, even borrowers with the strongest credit have not been spared. For those with scores between 951 and 1,000, the average rate at the three banks rose 0.64 percentage point to 6.17% in August from 5.53% in January. At the five largest banks, the comparable rate rose to 5.11% from 4.68%. The burden is heavier for borrowers with lower scores. At KakaoBank, the rate for those scoring between 701 and 750 climbed 1.86 percentage points to 8.83% in August from 6.97% a year earlier. Assuming a borrower draws the full 30 million won ($21,000) on a credit line for a year, that translates into about 560,000 won ($390) more in annual interest.
The increases stem from rising market rates. The yield on six-month bank debentures rose 0.951 percentage point to 3.748% on the 16th of this month from 2.797% on Jan. 2, according to the Korea Financial Investment Association. It has stayed above its level at the start of the year, registering 3.008% at the end of May and 3.471% at the end of August. "A rise in market rates can feed through quickly to unsecured loan rates, including credit lines, where floating-rate products account for a large share," a financial industry official said.