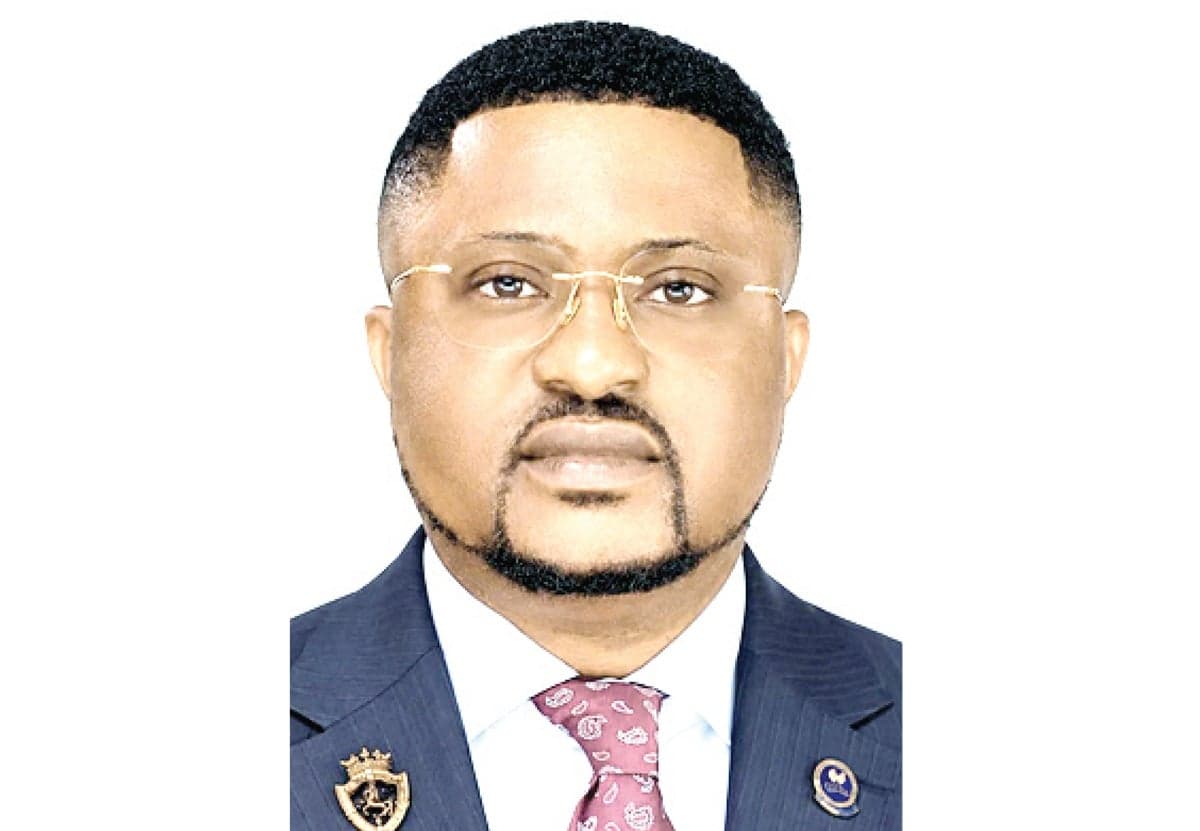
Mr. Jide Onasile, is a real estate practitioner, project manager, licensed estate surveyor and valuer, in this interview with Dayo Ayeyemi, he says Nigerians need more awareness regarding accessibility to mortgage products, financing options, to serve as an effective driver of mass housing delivery or wealth creation in real estate. Excerpts:
How will you describe Nigeria’s housing sector?
The housing sector is more crucial to a nation’s socioeconomic advancement and its citizens’ welfare than is always recognised. The construction and usage of adequate housing has an impact on a person’s environment, physical and mental health, and overall well-being. Its effects on macroeconomic variables such as employment, productivity, wealth creation, commodity sales, savings, investment and the performance of other sectors of the economy cannot be overstated.
For a number of reasons, adequate housing provision has since the 1960s elicited the attention, active and vibrant engagement of countries, both in the developed and developing nations. First, shelter is one of the basic and fundamental needs of man. Second, housing is a very essential durable consumer item, status enhancing, productivity impacting, increases workers’ health, well being and growth significantly. And because housing is one of the crucial indices for measuring peoples’ living standard across societies and nations, it becomes absolutely important that governments across the world should come up with policy frameworks and programmes of assistance in the vital areas of finance, research and provision of infrastructure to enhance or facilitate adequate housing delivery.
How has mortgage finance constituted a major barrier to housing development?
One area often fingered as one of the major constraints to housing development and delivery is mortgage financing. This is, and must be so because housing provision requires huge capital outlay, which is often beyond the capacity of people in the middle and low income groups. Considering the importance of housing and the fact that banks have consistent access to cheap sources of funds through retail deposits as well as the infrastructure to process real estate loans efficiently, and the risks to manage the risks involved, the Central Bank of Nigeria gave tacit endorsement to banks to support the development of the housing sector in Nigeria. Apart from the banks, the insurance companies are also fund mobilisers and important sources of capital fund for the economy. They are therefore well suited to providing finance because of their stable base of funding and long-term nature of their liabilities.
However, the main policy of government towards providing affordable and comfortable housing for all Nigerians is woven around the Federal Mortgage Bank of Nigeria (FMBN). The mortgage institution was established with the main objective of driving, addressing and meeting the housing needs of Nigerians through provision of sustainable liquidity, innovative products and excellent customer service.
Unfortunately, structural barriers, interconnected challenges of macroeconomic instability, institutional inefficiencies and weak legal enforcement weigh heavily on its operations and the Nigerian mortgage system generally, rendering it very ineffective, stunted, capturing less than one per cent of the country’s GDP, and less impacting, despite Nigeria’s massive housing deficit, estimated at about 15 million units, compounded by a growing urban population that urgently requires affordable housing.
Does Nigeria have an affordable mortgage?
Unlike in developed countries, where low, single digit mortgage rates make home ownership a realistic goal for middle-income households, Nigeria’s mortgage rates, which often exceed 20 percent are too high for a country, where the average worker earns far below the income threshold required to service such loans. This makes mortgage products become inaccessible to the majority of the people. The result is that our housing finance caters largely for the upper-income earners, leaving Nigerians in the middle and lower-income ends who form the bulk of the housing demand excluded from the system, thus creating affordability crisis, an economic and social problem which further widen inequality and undermines the transformative potential of housing finance. This is a big challenge, not to talk of the land tenure and titling system, which remains cumbersome, opaque, prone to abuse, and a big hindrance to housing development.
In a nutshell, the central issue in Nigeria’s mortgage system is affordability. Inextricably tied to the broader economic environment; the system renders the tool that has transformed housing access in advanced economies ineffective in our polity. This is the narrative the present administration endeavours to resolve and change with the introduction of key initiatives and reforms
As a nation, we ca no longer ignore a housing deficit conservatively estimated at about 15 million units, coupled with decades of limited access to affordable financing and home ownership opportunities for the majority of our citizens. Renewed Hope Agenda gave a clear directive, which is to reset the trajectory of housing in Nigeria, close the gap, and ensure that every Nigerian, whether low, middle, or high-income, has a fair chance to own a home. From the onset, the present administration was very clear in its Renewed Hope Housing Programme, a dynamic vision aimed at ensuring that housing has a broad national reach and deliver real impact for ordinary Nigerians.
ALSO READ: Uba Sani warns against reliance on foreign defence technology
Is government doing anything about this?
Guided by this vision, the Federal Government, early in the year, expanded the programme with a new N15 million interest-free loan window targeted principally at civil servants and public sector workers. The initiative, which endeavours to gradually ease mortgage rates, is directed at boosting home-ownership among middle-income government employees significantly. The new scheme builds on the existing FMBN mortgage products, and it is designed to meet the needs of every income segment by offering various financing options to assist Nigerians at every socioeconomic strata have a fair chance to home ownership.
What would you suggest?
What I think Nigerians need now is more awareness regarding accessibility to different mortgage products and financing options under the Renewed Hope Agenda, a policy framework which is set to reinvigorate the Nigerian mortgage landscape, which was hitherto small, restrictive, exclusionary, and unable to serve as an effective driver of mass housing delivery or wealth creation in real estate. The initiative, which also leverages public-private partnership for capital mobilisation offers various mortgage financing options and packages which include, among others, interest- free loans, and 15–20 years repayment period to make home ownership more affordable to Nigerians. The most critical objective of the programme is delivery of about 100,000 homes for middle-and-low income earners through mortgage, or outright purchase. Nigerians from anywhere in the country or abroad can apply online through the Federal Ministry of Housing and Urban Development digital housing portal. This innovative intervention is a critical tool for housing development, housing delivery, home ownership and national development.
WATCH TOP VIDEOS FROM NIGERIAN TRIBUNE TV
- Relationship Hangout: Public vs Private Proposals – Which Truly Wins in Love?
- “No” Is a Complete Sentence: Why You Should Stop Feeling Guilty
- Relationship Hangout: Friendship Talk 2025 – How to Be a Good Friend & Big Questions on Friendship
- Police Overpower Armed Robbers in Ibadan After Fierce Struggle