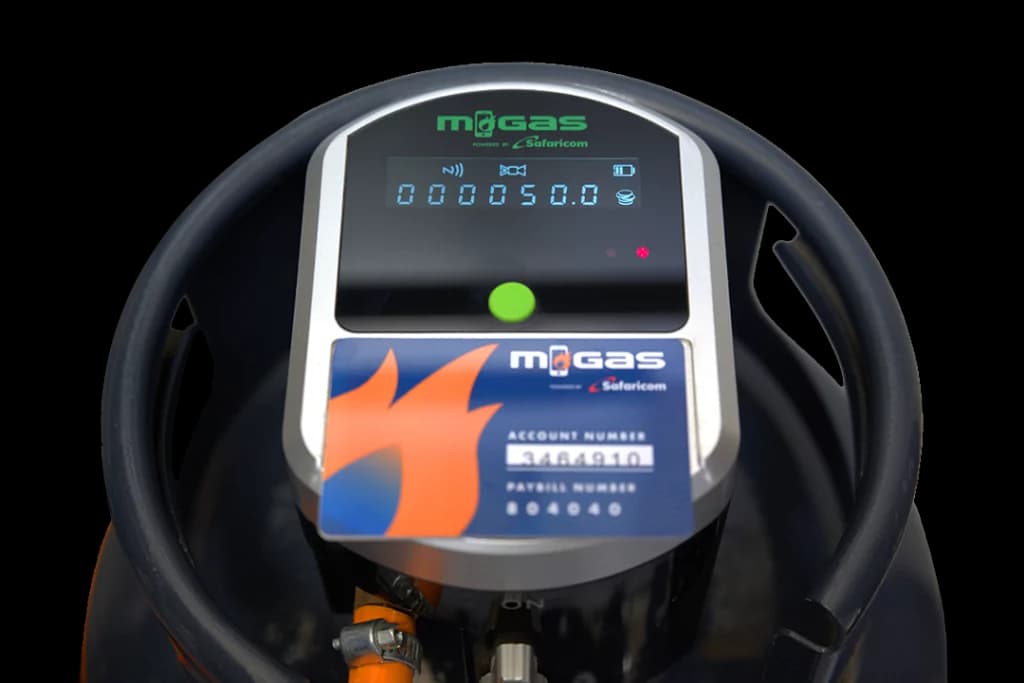
Circle Gas, the UK parent of Kenyan pay-as-you-cook liquefied petroleum gas (LPG) supplier M-Gas, reported $67 million in contracted carbon credits awaiting delivery and $57 million in cash prepayments in 2025, according to its financial statements.
The company’s dependence on carbon-credit revenue exposes the financial risks facing Kenya’s clean-cooking businesses, where government authorisation can determine whether contracted credits deliver their expected value.
The company’s accounts, filed in September, show the financial stakes. Circle Gas lost $39.3 million in 2025, held $1.1 million in cash at year-end and reported net liabilities of $156.7 million. It needs about $28 million in new funding to finance its growth plans.
Carbon credits are central to the economics of clean cooking businesses such as M-Gas. The company supplies LPG in small, affordable amounts with smart meters so households can pay as they cook. Revenue from the resulting emissions reductions can help support that model. Koko Networks, another Kenyan clean-cooking company, entered administration after the government declined to authorise the carbon-credit sales on which its business depended.
Circle Gas’s annual report says it received a “Letter of Acceptance” confirming that its carbon-credit projects met eligibility criteria and could proceed to apply for a “Letter of Authorisation.”
M-Gas announced in January 2026 that its clean-cooking carbon project had received a Letter of Approval. The report does not clarify whether this is the same document it calls a Letter of Acceptance.
Kenya’s carbon-market rules distinguish project approval from authorisation to transfer credits internationally. Under the relevant framework, the final authorisation requires government approval and determines whether specified emissions reductions can be transferred abroad.
Circle Gas did not respond to a request for comment.
The value of carbon credits
Circle Gas reported $67 million in contracted carbon credits yet to be delivered as of the end of 2025, and $57 million in cash already received as prepayments against carbon-credit contracts. The first figure represents credits awaiting delivery, while the second is money buyers have already paid.
The accounts do not disclose how much of the contracted portfolio depends on the outstanding authorisation or how much of the prepayments remains available.
Circle Gas says authorised credits can command significantly higher prices than credits sold in advance. It has not disclosed the expected premium. The company also excludes the higher value from its financial projections, leaving the potential upside outside its current funding assumptions.
Circle Gas grew revenue to $40.8 million in 2025 from $36.1 million, but remained loss-making, with a $39.3 million loss after tax. Its cash reserves fell to $1.1 million, while net liabilities climbed to $156.7 million from $116.5 million.
The company says it needs about $28 million to fund its 2026 growth plans. Without additional funding, it expects to limit investment and remain stagnant.
“At the date of approval of these financial statements, the additional third-party funding of approximately US$28.0m necessary to finance continued growth funding for the base case in 2026 is yet to be fully secured, and there is no certainty that funding will be available to the Group (Circle Gas),” the statement said.
The losses and funding needs cannot be attributed solely to the outstanding authorisation. But the delay leaves a potentially more lucrative source of carbon revenue uncertain as Circle Gas seeks new capital.
Koko’s carbon debt
Koko Networks built a business selling subsidised bioethanol stoves and fuel to low-income households, relying on carbon-credit sales to cover part of its operating costs. When the Kenyan government declined to authorise those sales, the company lost access to a revenue stream it needed to sustain the business.
Koko shut down in January 2026, laying off more than 700 employees. Its Kenyan and UK entities entered administration in February. The administrators now face the task of recovering money owed to creditors, with the carbon credits held by its UK arm a central asset. Without a sale, FirstRand Bank is owed $60 million, while other unsecured creditors are owed about $171 million.
Koko’s collapse shows how a clean-cooking business can accumulate substantial debts when it cannot sell the carbon credits expected to fund its operations.
The government rejected Koko’s application in early February 2026, with Trade Cabinet Secretary Lee Kinyanjui saying the volume of credits sought could have exhausted Kenya’s allocation for international transfers, leaving other projects in agriculture and manufacturing with little room to sell their credits abroad.
Unlike Koko Networks, Circle Gas has not had its authorisation request rejected. M-Gas announced that its project had received a Letter of Approval. However, Circle Gas’s accounts indicate it is still seeking a Letter of Authorisation and do not disclose how much of its contracted carbon credits depends on it.
Koko is the clearest warning of what is at stake: carbon credits may be recorded as assets, contracted to buyers and used to secure financing, but they cannot generate the expected cash if the company cannot sell them.
Kenya’s carbon-credit rules give the government control over which emissions reductions can be sold abroad, leaving companies exposed to decisions that can affect their revenues and debts.
Circle Gas secured earlier approval for its project but is still seeking authorisation, leaving the value and delivery of some contracted credits uncertain.
True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.
