Nigeria’s industrial policy faces a problem that billions of naira and dollars in new financing cannot solve on their own. The government is expanding development-finance institutions, pursuing international partnerships and promising manufacturers access to longer-term capital. Yet a factory struggling with expensive electricity, costly imported inputs, weak demand and unreliable logistics cannot become competitive simply because it receives a cheaper loan. Unless industrial financing tackles these underlying constraints, Nigeria risks expanding the money available to manufacturers without generating a corresponding increase in production, productivity and jobs.
That is the central test of the country’s industrial financing strategy: whether public money is removing the barriers that prevent factories from operating competitively or merely helping selected businesses cope with an expensive operating environment.
The distinction matters as the Federal Government pursues a broader industrial transformation agenda. In April 2025, Nigeria and the United Nations Industrial Development Organisation (UNIDO) signed a Programme for Country Partnership (PCP), a $174.585 million framework covering 2024–2028. The financing structure envisaged $149.619 million from UNIDO and development partners, alongside $24.966 million in Federal Government counterpart funding.
The partnership aims to strengthen industrial capacity, encourage technological innovation and support sustainable manufacturing. However, its financial framework is an input, not evidence of industrial transformation. Its success should ultimately be measured by the factories it helps modernise, the costs it reduces, the jobs it creates and the additional output generated.
At the partnership’s signing in April 2025, the Federal Government reported a financial commitment of approximately $1.28 million against its $24.966 million counterpart-funding obligation. This provides an initial implementation benchmark, not a current measure of disbursement. Without updated information on government payments, donor contributions and project-level expenditure, the extent to which the programme has moved from commitments to implementation remains difficult to establish.
The policy diagnosis must come before the money
Nigeria’s industrial financing strategy rests on a sound economic argument. Manufacturers need capital to purchase machinery, expand production, adopt technology and develop higher-value products. Commercial banks may hesitate to finance projects with long payback periods, uncertain cash flows or inadequate collateral. Development-finance institutions can bridge this gap through longer-term lending, risk-sharing arrangements and technical assistance.
The problem is that finance represents only one part of the constraints facing manufacturers.
A company may borrow to install a modern production line but struggle to operate it because electricity costs consume its margins. Another may have adequate machinery but lack reliable foreign-exchange access for essential imported components. A third may possess the capacity to increase production but face insufficient demand, expensive transportation or difficulty meeting export-market standards.
In each case, cheaper credit may ease financial pressure without resolving the underlying problem. A factory that cannot operate profitably will not become competitive simply because its borrowing costs fall. It may instead accumulate additional debt while remaining unproductive.

Industrial financing must therefore begin with a diagnosis of the constraints affecting particular sectors and firms. Equipment loans may help businesses with viable demand but insufficient investment capital. Energy-efficiency financing may be more effective where inefficient machinery drives production costs. Export guarantees, improved standards infrastructure and better logistics may be necessary where manufacturers struggle to reach larger markets. The objective should not be to distribute more credit indiscriminately. It should be to ensure that each intervention addresses a demonstrable constraint and produces additional economic activity that would otherwise not have occurred.
What the expanding financing architecture can achieve
The Federal Government’s February 2026 Nigeria Industrial Policy brought several financing instruments into a broader industrial-development framework. These include plans to recapitalise the Bank of Industry to N3 trillion and expand sector-specific intervention funds from N1 trillion to N3 trillion. In May 2026, the African Development Bank approved a $200 million facility for the Bank of Industry.
Together with the UNIDO partnership and industrial energy-efficiency initiatives, these measures could strengthen the institutional capacity to finance manufacturing projects that conventional lenders consider too risky or long-term. The Bank of Industry’s reported lending activity suggests that industrial financing is already extending beyond policy announcements. According to the Presidency, the bank disbursed N636 billion to more than 7,000 enterprises in 2025, including N79 billion allocated to manufacturing.
These figures demonstrate reported financing activity, but they do not establish how much additional production, employment, productivity growth or export revenue the manufacturing allocation generated. That distinction is critical to evaluating the programme.How many recipient factories expanded production? How many reduced unit costs, installed modern equipment or entered new markets? How many jobs were created rather than merely preserved? How much additional domestic value was generated? Without these indicators, disbursement figures demonstrate the reach of financing, not its complete economic impact.
The status of the different funding instruments also requires careful distinction. The proposed N3 trillion capital targets for the Bank of Industry is not necessarily equivalent to capital already paid into the institution. The planned expansion of intervention funds does not establish that the entire amount has been funded or disbursed. Similarly, the African Development Bank’s $200 million facility represents an approved financing commitment, not proof that the full amount has reached manufacturers or translated into operating factories.
Industrial financing passes through several stages: funding is proposed, resources are secured, facilities are approved, businesses receive financing, projects are completed and production outcomes emerge. Each stage carries a different economic meaning.
These instruments should not be added together as though their headline values represent cash already available to manufacturers. A proposed target is not paid-in capital, an approved facility is not necessarily a disbursed loan, and a donor-financing commitment is not a completed industrial project.
Public financing also carries an opportunity cost. Money allocated to an unviable factory cannot be used to support another productive business or address infrastructure deficiencies. Poorly designed subsidised lending can encourage political allocation, weaken repayment discipline and reward firms that would have invested without government assistance. A credible strategy therefore requires transparent beneficiary selection, technical and commercial appraisal, appropriate repayment arrangements and safeguards against politically directed lending. Public support should correct market failures, not become a permanent substitute for commercial viability.
Bank recapitalisation offers a warning
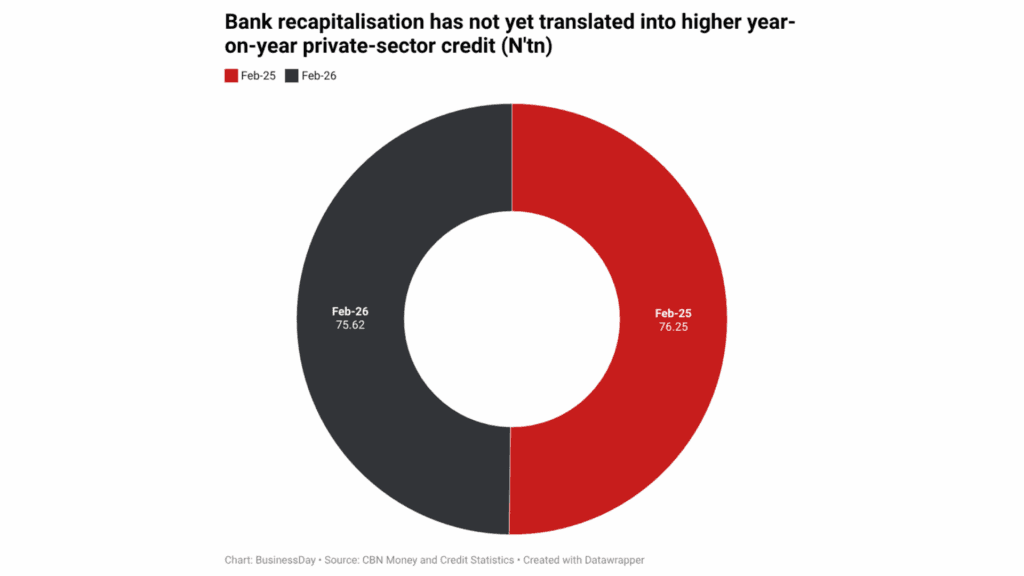
Nigeria’s banking recapitalisation illustrates why stronger financial institutions do not automatically produce more productive lending. Between 2024 and March 2026, banks raised more than N4 trillion in fresh capital, while 33 lenders met the revised capital requirements by the March 31, 2026 deadline. Yet private-sector credit was reported at N75.62 trillion in February 2026, compared with N76.25 trillion a year earlier.
These figures do not prove that recapitalisation caused credit to weaken. Lending also responds to interest rates, borrower demand, credit risk, loan classification and changes in bank balance sheets. As economist Ayo Teriba has argued in discussions of recapitalisation, banks may first need to repair balance sheets weakened by bad loans before expanding new lending.
The broader lesson is that increasing a financial institution’s capacity does not guarantee that the additional capacity will reach productive businesses. The same principle applies to the Bank of Industry. Achieving a N3 trillion capital target could strengthen its ability to lend, but it would not establish that viable manufacturers received financing or that production increased.
The government must measure financial performance alongside industrial additionality. How much new lending reaches viable manufacturers? How much private investment does each naira of public support attract? How many recipient firms increase production beyond what they would have achieved without assistance? These questions offer a stronger basis for judging policy effectiveness than the size of a development bank’s balance sheet.
Energy efficiency shows why implementation matters
The GEF-UNIDO Industrial Energy Efficiency and Resource Efficient Cleaner Production project offers a more direct test of whether industrial intervention can improve factory productivity. Approved for implementation in January 2020, the programme was designed to support more efficient industrial energy use and resource management, with financing support channelled through the Bank of Industry.
The economic rationale is straightforward. Manufacturers relying on self-generated electricity, inefficient equipment and poorly maintained production systems face costs that undermine competitiveness. Reducing energy consumption per unit of output can improve margins without requiring businesses to increase prices or expand production.
However, the number of workshops held, energy audits conducted or transition plans prepared is not the ultimate measure of success. These are implementation outputs. The economic outcome is whether factories complete recommended upgrades, reduce energy consumption per unit produced, lower operating costs and improve production reliability.
The public evidence reviewed for this analysis does not establish a consolidated count of completed factory retrofits and their measured savings. This does not prove that the programme has achieved nothing. It means the available evidence is insufficient to determine its aggregate industrial impact. The same measurement problem affects the wider financing architecture. Without a common project register, it is difficult to distinguish projects that have been announced from those that have received funding, completed construction or begun commercial operations.
Accountability must follow the money to the factory floor
Nigeria needs an industrial-policy evaluation framework that tracks public support from funding to measurable economic results. The first stage should capture inputs, including government counterpart payments, development-partner contributions, paid-in capital and approved credit facilities. The second should document outputs, such as loans disbursed, factories supported, machinery installed and infrastructure delivered.
The third stage should measure outcomes: lower production costs, higher capacity utilisation, increased output, improved productivity and additional employment. The final stage should assess broader impacts, including domestic value addition, competitive exports, reduced dependence on imported manufactured goods and manufacturing’s contribution to economic growth. These stages should never be treated as interchangeable. A project can receive its full funding and still fail to deliver its intended results. Equally, a completed project may be too small to make a meaningful difference to national industrial performance.
The Ministry of Industry, Trade and Investment, the Bank of Industry, the Central Bank of Nigeria, the Ministry of Budget and Economic Planning and UNIDO should publish a common industrial-project dashboard. For every major funding stream, it should disclose the financing source, approval date, amount committed and disbursed, beneficiaries, project locations, implementation status and expected completion dates.
Completed projects should be assessed against operating performance, including changes in capacity utilisation, output, energy consumption per unit produced, employment, domestic value added and exports. Where feasible, independent evaluations should compare supported firms with similar businesses that did not receive assistance. Such comparisons would help establish whether improvements resulted from public support or from wider changes in exchange rates, demand and economic conditions. The government should also attach clear conditions to continued assistance. Projects meeting agreed milestones could qualify for subsequent financing, while persistent delays should trigger reviews. Firms receiving concessional loans or subsidies should demonstrate credible commercial plans and measurable public benefits.
Crucially, industrial finance must complement policies addressing electricity costs, foreign-exchange access for essential inputs, transport infrastructure, technical skills and market access. A loan cannot compensate indefinitely for unreliable power or an inaccessible market. The objective is not to make manufacturers permanently dependent on subsidised financing. It is to help viable businesses overcome constraints that prevent them from investing, expanding and competing.
The verdict: productivity, not funding announcements
Nigeria’s industrial financing architecture is becoming more ambitious. The UNIDO partnership, planned expansion of the Bank of Industry, sector-specific intervention funds and African Development Bank facility offer instruments that could help close longstanding gaps in industrial investment.
But the existence of these instruments does not establish that those gaps have closed. Nor does the absence of a consolidated public tracker prove that the projects have failed. It means the available evidence does not yet provide sufficient confidence to judge the scale of implementation and the returns on public support. The policy challenge is twofold: remove the constraints that make Nigerian factories uncompetitive and establish whether industrial financing is successfully doing so.
Nigeria does not need to choose between financing manufacturers and demanding accountability. It needs both. The ultimate measure of industrial-policy success is not how many billions of naira or dollars the government announces, but how much additional, productive and competitive output those funds enable Nigerian factories to deliver.
Related News

Oluwatobi Ojabello, PhD, is a dynamic and multi-dimensional Assistant Editor for Economy and Markets with over two years of professional journalism experience. He delivers authoritative, data-driven coverage of fiscal policy, financial institutions and capital markets, using clear analysis to explain Nigeria’s most complex economic developments. His work focuses on macroeconomic policy, financial stability and corporate performance, turning technical issues into accessible narratives that inform both experts and everyday readers.

