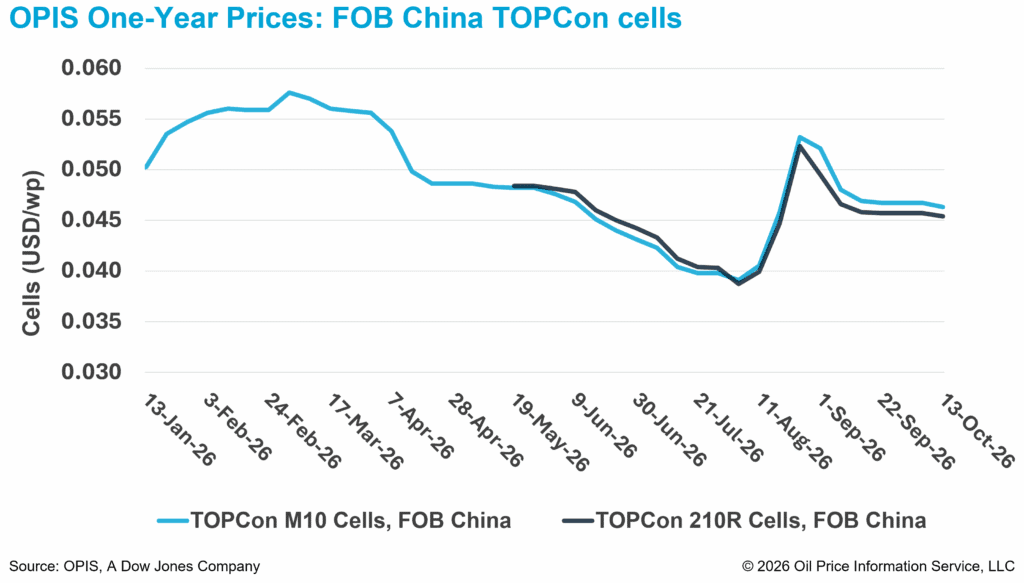
According to the OPIS Global Solar Markets Report released on Oct. 13, Free-On-Board (FOB) China TOPCon M10 cell prices fell 0.86% week on week to $0.0463/W, while FOB China TOPCon 210R cell prices fell 0.66% to $0.0454/W.
The declines ended two consecutive weeks of stability and left both formats around 13% below their late-August peaks, as overseas demand continued to signs of weakening after the Golden Week holiday.
A trader source, echoing a recent assessment by the China Nonferrous Metals Industry Association (CNMIA), said U.S. restrictions on stockpiling were expected to further weaken overseas demand and weigh on cell prices. The temporary U.S. rule covers polysilicon and its derivatives ahead of Section 232 measures taking effect on Dec. 4.
In India, a manufacturer said an earlier buying rush from the commercial and industrial (C&I) segment was tapering. An extended exemption allows eligible C&I projects commissioned by Dec. 31, 2026, to forgo the use of approved India-made solar cells. The manufacturer said, however, elevated FOB China cell prices and the approaching deadline made further stockpiling commercially unattractive.
In China, CNMIA forecast a gradual strengthening in utility-scale demand toward year-end. Procurement to meet project deadlines could support buying, although market participants questioned whether any pickup would translate into a sustained recovery in installations.
China added 97.19 GW of solar capacity in January-August, down more than 57% year on year, according to National Energy Administration (NEA) data.
The China Photovoltaic Industry Association (CPIA) forecast in February that installations would reach 180-240 GW in 2026, down around 24%-43% from the record 315.07 GW added in 2025. Reaching that range would require average monthly additions of 20.7-35.7 GW from September through December, compared with about 12.1 GW a month in January-August.
On the supply side, market participants continued to expect lower cell output in October, citing production-line upgrades ahead of China’s new minimum efficiency requirements. The mandatory standard, which covers modules and inverters, takes effect on Jan. 1, 2027, and will prohibit domestic sales of products that fail to meet the required thresholds.
pv magazine Session @ NetZero Milan Expo Summit 2026
The dynamics shaping global PV supply chains – including solar modules, inverters, and battery energy storage systems – will be discussed during the “Decoding solar supply chains” session at the NetZero event in Milan on Oct. 21.
The session will examine the forces reshaping clean energy supply chains, from manufacturing and sourcing strategies to shifting trade and regulatory requirements. It will also explore what these developments mean for companies procuring solar and energy storage equipment in an increasingly complex global market.
Join us in Milan to hear from industry experts and take part in the discussion on the future of solar supply chains.
Meanwhile, market sources said senior executives from several major solar manufacturers met in Hangzhou on Oct. 11 to discuss cost calculations, sales pricing and production cuts.
Although neither the meeting nor its reported outcomes have been officially confirmed, market participants said the discussions yielded more detailed implementation plans for capacity restrictions and a proposal to set a minimum polysilicon price of CNY 43 ($6.38)/kg, including tax. Sales below that threshold would reportedly be classified as low-price dumping.
Discussions also reportedly covered price floors of CNY 0.79/W for TOPCon modules and CNY 0.86/W for back-contact modules, with reported FOB equivalents of $0.117/W and $0.128/W, respectively.
The proposed TOPCon floor, at its FOB equivalent, would be approximately 9% above the Chinese Module Marker (CMM), OPIS’s benchmark for TOPCon modules below 645W from China, which was assessed at $0.107/W in the same report.
According to market participants, the proposed floors would apply to both export sales and domestic procurement, including tenders.
The meeting also reportedly called on relevant authorities to investigate and penalize state-owned enterprises that award procurement contracts through tenders based solely on the lowest available bids, citing concerns that such practices could disrupt market order.
However, market participants noted that industry self-regulatory agreements do not constitute legally enforceable price controls, with actual transaction prices continuing to be determined by supply-demand fundamentals. As such, the effectiveness of these measures would depend on manufacturers’ willingness to adhere to the proposed guidelines.
OPIS is a specialist business within Dow Jones Energy, a global energy intelligence business that brings together trusted price reporting, research and market intelligence across the energy value chain. OPIS publishes the OPIS Global Solar Markets Service, which includes pricing data for solar panels and components across Asia, Europe and the U.S., manufacturing capacity data, module forward curves, and a global solar policy tracker.
The post China TOPCon solar cell prices edge lower after Golden Week as industry weighs price floors appeared first on pv magazine Global.