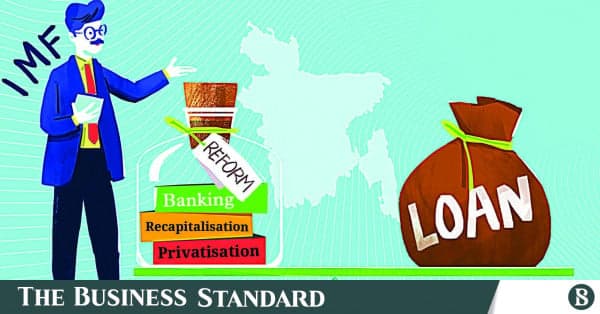
On 4 October, at an investor event in Dhaka, the finance minister said Bangladesh had cancelled its IMF programme because its conditions were unacceptable and would raise money from the market instead. Twelve days later, in Bangkok, he said the proposals were acceptable in principle and that officials would spend the next fortnight working through the details.
The change in tone matters. Bangladesh is again negotiating with the institution whose conditions it had publicly rejected.
Bangladesh is reported to be seeking a new programme worth $4.5 billion, with officials hoping for an agreement by the end of the year. The amount and timetable remain subject to negotiation. The more useful question is what that agreement should deliver beyond the money.
The debate is about the wrong number
Much of the discussion in Dhaka has been about whether $4.5 billion is enough and whether its conditions are acceptable. Investors will also ask what the programme says about the government's ability to carry out reforms.
The lesson is not that any asset sale will attract foreign funds. A large, well-prepared offer could draw attention, but investors would still need reliable accounts, sound governance and a convincing valuation.
Moody's returned Bangladesh's outlook to stable in September but continued to identify engagement with the IMF as an important source of support for external financing and reform. An IMF programme is a loan, but it also signals whether the government has agreed to a credible economic plan.
At the same time, Bangladesh is preparing a debut international sovereign bond of up to $1bn. The order in which the programme and the bond proceed could affect how investors assess the offer. An agreed reform plan would give them more to work with than promises made while negotiations remain unfinished.
What Pakistan's sequence shows, including the failure
I worked on Pakistan's state-asset sales under its 2013 IMF programme, and the sequence offers a useful comparison. Pakistan returned to the Eurobond market in 2014 and sold government stakes in United Bank Limited and Pakistan Petroleum Limited that June. A sale of its stake in Habib Bank followed in April 2015. These transactions formed part of a wider privatisation programme monitored through IMF reviews.
The failure in the middle is the more useful lesson. In November 2014, the government offered shares in Oil and Gas Development Company Limited at a minimum price. Demand covered only about half the offer, and the government withdrew the sale. The transaction was postponed, but the IMF programme continued.
Two differences limit the comparison. Pakistan had issued international bonds before, and these were sales of government holdings in companies already traded on stock exchanges. Bangladesh would be entering the international sovereign bond market for the first time. Preparing a state company for international equity investors would also take time.
The lesson is not that any asset sale will attract foreign funds. A large, well-prepared offer could draw attention, but investors would still need reliable accounts, sound governance and a convincing valuation. Bangladesh would need to prepare its equivalent on those terms.
Who pays for the banks
The sharper issue in the IMF discussions is not the size of the loan. Ahead of the Bangkok meetings, reporting indicated that the Fund wanted a credible assessment of banks' capital needs and a timetable for addressing weaknesses. That would give the bank clean-up a measurable place in the programme.
A capital shortfall is not automatically the amount taxpayers must pay. The eventual public cost would depend on recoveries from bad loans, contributions from existing owners, new investment and decisions about which banks should be restructured or resolved. But where public money is required, the cost belongs in the budget and should be explained.
A programme cannot make those losses disappear. It can require the government to publish a credible estimate, explain how the burden will be shared and set deadlines for action. Protecting depositors should be part of that plan.
The strongest objection is that asset sales do not address the underlying constraints. Weak revenue collection and poor bank governance do. Selling valuable holdings before they are ready, or into an unreceptive market, could also destroy value. Both concerns are valid. Neither is an argument against careful sequencing.
Revenue reform and bank repair must remain central to the programme. Privatisation proceeds would be a one-off contribution, not a substitute for either. Pakistan's withdrawn sale offers a narrower lesson about avoiding a fire sale. A government can set a minimum price and refuse an inadequate offer. It does not follow that an unsuccessful offer automatically fulfills an IMF benchmark. That would depend on the benchmark's agreed wording.
I argued in June that Bangladesh needed a market-access plan before its repayment pressures intensified. The point now is more immediate. Preparations for a bond are advancing while the terms of a new IMF programme are still being negotiated.
The Finance Division and Bangladesh Bank should consider three priorities in negotiating the programme and planning the bond.
First, secure and announce a staff-level agreement before the debut bond is priced. This is the stage at which IMF staff and the government have agreed terms, subject to approval by the Fund's Executive Board. It would not guarantee cheaper borrowing, but it would give investors a clearer basis for assessing policy commitments. Any additional borrowing cost accepted at issuance could remain with Bangladesh for the life of the bond.
Second, seek agreement on publishing a credible assessment of the banks' capital shortfall before programme approval, with a dated restructuring and recapitalisation plan to follow. If publication is made a prior action, it would need to be completed before the Board considers approval. The assessment should distinguish the banks' total capital needs from the expected call on public funds. Without that distinction, neither investors nor taxpayers can judge the bill.
Third, prepare one flagship privatisation, a substantial sale of shares in a suitable state company, with a realistic timetable in the programme. The company should be selected on commercial grounds and prepared for scrutiny by domestic and international investors. A minimum price should be set through a transparent valuation process, with room to postpone the sale if acceptable bids do not arrive.
The programme should distinguish between preparing and offering the shares and completing the sale. The government should also commit to using any proceeds to help meet the public cost of bank restructuring, with the allocation recorded transparently in the budget. No spending should depend on proceeds that have not yet been received.
Pakistan's experience included a return to international bond markets, several completed share sales and a postponed transaction. It offers a useful example of sequencing, not a guarantee that Bangladesh would achieve the same results. The $4.5 billion matters. But a credible bank-repair plan and better-prepared access to capital markets could prove more valuable over time.
Fahim Chowdhury is an investment banker who has raised over $200 billion and executed 500+ capital markets transactions in 30+ markets, including numerous privatisations. He is currently Managing Director at RetailBook and was previously at Citi. He has advised on privatisations and sovereign capital raises in Pakistan, Turkey, Romania, Slovenia, Poland, and the UAE.