From higher personal tax relief and stamp duty exemptions to corporate tax breaks, green investments, and deductions for supporting students, these are the Budget 2027 tax measures worth knowing about.
 Cover image via ASNB Academy
Follow us on Instagram, TikTok, and WhatsApp for the latest stories and breaking news.
Budget 2027 is not just about cash aid, minimum wage increases, and changes to personal income tax rates
The government has also announced a wide range of tax incentives that could help Malaysians reduce their tax bills, buy their first homes, run businesses, and invest in specific industries.
Some of these measures are relatively easy to overlook, including tax relief for AI subscriptions and pet adoption fees, stamp duty exemptions for opening bank accounts, and deductions for businesses that contribute food and equipment to student welfare programmes.
Others are designed specifically for companies, investors, manufacturers, and financial service providers.
Here are all the tax incentives and related tax measures announced under Budget 2027, grouped by who stands to benefit and what the incentives cover.
Personal income tax: 10 changes Malaysians should know about
- The basic individual income tax relief will increase from RM9,000 to RM12,000, marking its first revision since 2010. The higher relief reduces the amount of income subject to tax for eligible individual taxpayers.
- Tax rates will be reduced by one percentage point for two taxable-income bands. For RM70,000 to RM100,000, the proposed deduction is 18% from 19%, and for RM100,000 to RM150,000, it's 24% from 25%. The changes could leave eligible taxpayers with more disposable income, although the actual savings will depend on their individual tax calculations.
- At the other end of the income scale, the individual income tax rate for those with chargeable income exceeding RM1 million will be adjusted to 30% from the earlier 28%. This is a tax increase rather than a tax break, but it is part of the wider set of individual income tax changes announced in the budget.
- Eligible taxpayers will be able to claim expanded medical-related tax relief covering postnatal care services. The precise eligible expenses and claim conditions should be checked against the final tax guidelines.
- The existing relief for caring for parents and grandparents will be expanded beyond strictly medical expenses to cover all eligible care expenses. This could make the relief more relevant to families paying for elderly care, rather than limiting claims to medical bills alone.
- The scope of sports equipment tax relief will expand to include purchases of sports shoes. For eligible taxpayers, this broadens the range of sporting expenses that may qualify for relief, subject to the final rules.
- Education and skills course fee relief will be expanded to cover all fields of study, alongside tuition fees for children. The change could make the relief more useful to taxpayers pursuing different learning pathways and families paying for their children's tuition.
- The expanded lifestyle relief will cover several expenses that people might not immediately associate with tax deductions, such as AI software subscriptions, vaccinations, and pet adoption fees paid to registered shelters. These additions could make certain everyday and digital expenses eligible for tax relief, depending on the applicable conditions and limits.
- Tax relief for mandatory PERKESO contributions will be expanded to include contributions under the self-employment social security scheme, Lindung Kendiri. This is particularly relevant to eligible self-employed individuals who need social protection but do not receive it through a conventional employer.
- Eligible taxpayers will receive additional tax relief of up to RM150 for voluntary contributions to the relevant 24-Hour and Self-Employment social security schemes. The measure provides a further tax incentive for those who contribute towards their own protection.
Image used for illustration purposes only.
Image via ASNB AcademyHomes, banking, and financing: Seven stamp duty measures
- Eligible first-time homebuyers will receive a full stamp duty exemption on transfer instruments and loan agreements for homes worth up to RM500,000. The exemption will apply to qualifying transactions through 31 December 2030.
- For eligible first homes priced above RM500,000 and up to RM750,000, the first RM500,000 will receive full stamp duty exemption, while the remaining balance will qualify for a 50% exemption. The announced period also runs through 31 December 2030.
- Stamp duty will be fully exempted on qualifying loan agreements and transfer instruments executed by rescue developers and original buyers involved in reviving abandoned housing projects. The measure is intended to support the revival of stalled developments and applies through 2030 under the announced arrangements.
- From 1 January 2027, opening savings and current accounts will receive a full stamp duty exemption. This is one of the more straightforward measures in the list, although the practical benefit will depend on the stamp duty that would otherwise have applied to the relevant account-opening documents.
- Qualifying loan agreements executed through peer-to-peer financing platforms will be subject to a fixed nominal stamp duty of RM10. The concession is scheduled to apply from 2027 to 2030.
- Banking agreements using excess credit facilities for eligible mid-tier companies and MSMEs will receive a fixed RM10 stamp duty rate. The measure is intended to reduce financing-related costs for qualifying businesses and will apply during the announced 2027–2030 period.
- The RM10 stamp duty concession for financing agreements under Skim CAKNA I and Skim CAKNA II will be extended through 2030. Eligible businesses should check the relevant scheme conditions before assuming that their financing qualifies.
Businesses and manufacturers: Six tax measures to know
- Eligible micro, small, and medium enterprises (MSMEs) will benefit from lower income tax rates across two bands. The first RM150,000 of chargeable income will be 14% down from 15%, and RM150,000 to RM600,00, it will be 16% down from 17%. The changes could reduce the tax burden for qualifying businesses, with actual savings depending on their chargeable income.
- The per-asset threshold for small-value asset capital allowance will increase to RM3,000. The annual claim ceiling for non-MSMEs will also rise to RM30,000. Capital allowances allow businesses to claim qualifying capital expenditure against taxable profits under the relevant tax rules. The higher limits could make it easier for businesses to claim allowances for smaller purchases.
- Accelerated capital allowance for qualifying locally purchased plant, machinery, information and communications technology equipment, and software will be extended to 31 December 2030. This could help eligible businesses obtain tax relief on qualifying investments sooner than under ordinary capital allowance arrangements.
- Manufacturers will be able to reclaim sales tax paid on qualifying locally purchased machinery, spare parts and equipment, as well as specified agricultural, animal feed, and pharmaceutical raw materials. The measure could reduce the tax cost of eligible purchases used in manufacturing, subject to the relevant refund requirements.
- Qualifying automotive vendors that are 100% locally owned can claim tax deductions of up to RM5 million for relocation expenses when moving to Tanjong Malim. The incentive will apply from 2027 to 2030 under the announced arrangements.
- Non-MSME companies will only be able to claim tax deductions for employee wage expenses if salaries are paid through the prescribed banking channels in accordance with the Employment Act 1955. This is a compliance requirement rather than a new tax break. Employers should review their payroll arrangements to ensure that wage expenses remain deductible under the revised rules.
Investment, finance, and shipping: Nine sector-specific incentives
- Eligible providers of Shariah-compliant fund management services will receive a 40% income tax exemption for years of assessment 2028 to 2030. The incentive is targeted at qualifying fund management businesses rather than individual investors.
- Tax deductions will be available for approved issuance costs associated with Prisma Sukuk for years of assessment 2027 to 2030. The measure could reduce the cost of raising funds through qualifying sukuk issuances.
- Grants received under the Sustainable and Responsible Investment (SRI) Sukuk and Bond Grant Schemes will be exempt from income tax. The measure is aimed at supporting eligible financing and fundraising activities connected to sustainable and responsible investment.
- Qualifying new companies and existing principal hubs under the Global Services Hub (GSH) framework will receive a preferential 5% income tax rate on eligible income exceeding the applicable baseline. Businesses will need to satisfy the relevant conditions to qualify for the incentive.
- Qualifying treasury and fund management activities under the Global Services Hub framework and the Johor-Singapore Special Economic Zone will receive withholding tax exemptions on interest payments and stamp duty exemptions on intercompany loans. These incentives are aimed at reducing financing and treasury costs for eligible operations.
- Eligible single-family offices and multi-family offices operating under the relevant Forest City framework can qualify for a 0% concessionary tax rate on eligible income for up to 20 years. This is a highly targeted incentive for qualifying family office structures, not a general tax exemption for people who invest or own property in Forest City.
- Income tax exemptions for qualifying private angel investors and individuals investing through Equity Crowdfunding platforms will be extended through 2030. Eligible investors should check the scheme's requirements, including any conditions relating to the investment and the relevant approval process.
- The 100% income tax exemption for eligible Malaysian domestic shipping enterprises will be extended through the year of assessment 2036. The extension offers longer-term tax certainty for qualifying operators in the domestic shipping sector.
- Stamp duty on qualifying loans used to purchase or build Malaysian vessels will be capped at RM2,000 for loans of up to RM100 million and RM5,000 for loans exceeding RM100 million. The measure reduces the stamp duty payable on eligible ship-financing agreements.
Green technology, social welfare, and culture: 10 more incentives
- Investment tax allowances of up to 100% for qualifying green technology projects, electric vehicle charging infrastructure and commercial green asset acquisitions will be extended through 2030. The incentive is intended to support investment in eligible green technologies and infrastructure.
- The service tax rate on eligible senior care services will fall from 8% to 6%. A full service tax exemption will also apply to qualifying senior care fees of up to RM96,000 annually. The changes could reduce the tax component of eligible care expenses, although the precise effect on the final amount paid will depend on the services covered and how providers price them.
- Employers will be eligible for tax deductions when they pay off employees' PTPTN education loans during 2027 and 2028. The measure could encourage companies to offer student loan repayment assistance as an employee benefit, subject to the final conditions.
- Private companies carrying out recognised youth industrial training programmes will be eligible for tax deductions under the BAKAT MADANI initiative. The incentive will run through 2030 under the announced arrangements.
- Cash donations to public university development funds and the School Public Contribution Fund (TSUWAS) will be eligible for tax deductions of up to 10% of aggregate income. Eligible donors should check the requirements governing qualifying funds, documentation and claims.
- Tickets to qualifying local films and theatre productions in the Federal Territories will receive a 100% entertainment duty exemption. The measure could reduce the tax burden associated with eligible performances and screenings, although it does not automatically mean every ticket price will fall by the same amount.
- Qualifying arts, cultural, sports, and entertainment events held at Stadium Merdeka and Stadium Negara will receive a 100% entertainment duty exemption. The measure is targeted at events staged at the two heritage venues and is separate from the exemption for local film and theatre tickets.
- Tax incentives for organising international meetings, incentive travel, conferences and exhibitions will be extended through the year of assessment 2030. The extension is intended to support eligible business events and the wider meetings, incentives, conferences and exhibitions industry.
- Import duty exemptions will apply to eligible inputs and raw materials used to manufacture designated goods made in Langkawi. Manufacturers will need to check which products and materials qualify under the applicable conditions.
Additionally, businesses can claim deductions for donating food and equipment to student kitchens
Businesses that donate food supplies and cooking equipment for eligible university student kitchen programmes will qualify for tax deductions from 1 January 2027 to 31 December 2030.
The measure was announced in the context of the Dapur Siswa MADANI programme, which provides cooking equipment, food supplies and affordable meals to students.
The Domestic Trade and Cost of Living Ministry subsequently linked the broader initiative to its Ihsan Food Bank (i-FB) ecosystem. Businesses considering donations should check the final guidelines to confirm which contributions and recipient organisations qualify.
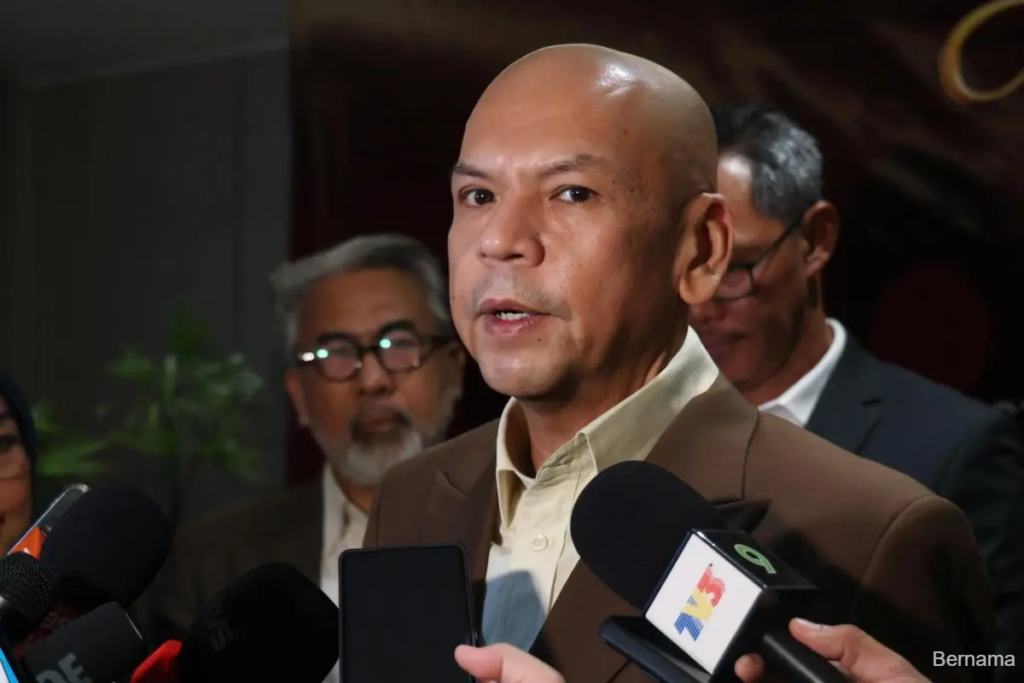
Domestic Trade and Cost of Living Minister Datuk Armizan Mohd Ali.
Image via BernamaFOLLOW SAYS