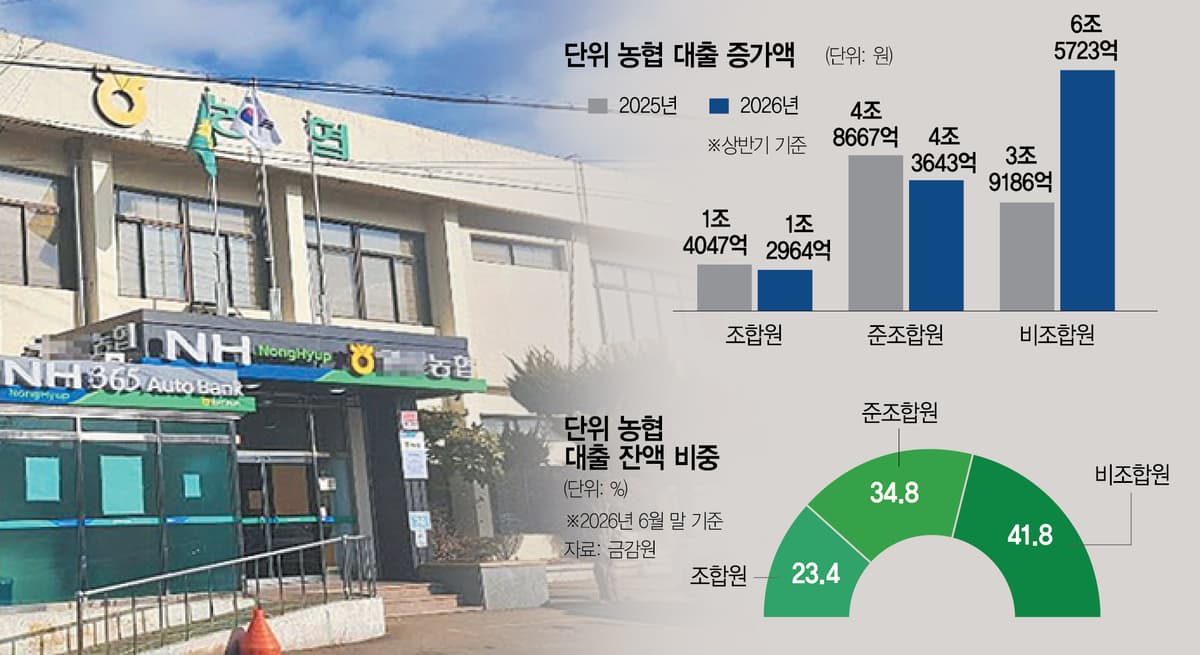
Farmer members account for less than a quarter of outstanding loans at South Korea's agricultural cooperatives, and roughly 90% of the lending growth in the first half of this year went to associate and non-members. As the number of farmers declines and cooperative banking expands around customers outside the membership, critics say Nonghyup must redefine its role in line with its founding purpose.
Loans at the country's 1,112 agricultural cooperatives rose by 12.23 trillion won ($8.5 billion) in the first half of this year, according to financial industry data released on the 11th. Of that, 10.94 trillion won, or 89.4%, went to associate members and non-members, up 3.2 percentage points from 86.2% a year earlier. Total outstanding loans rose 5.05% to 399.97 trillion won at the end of June, from 380.72 trillion won a year earlier.
Non-member lending drove the overall increase. Loans to non-members rose 6.57 trillion won in the first half, accounting for 53.7% of the total increase. Associate member loans rose 4.36 trillion won, or 35.7%. Loans to farmer members grew just 1.3 trillion won, or 10.6%. Associate members are people who do not qualify as farming members but meet requirements such as residency in the area. Non-members include small businesses and sole proprietors that use the cooperatives for banking.
The gap was also clear in growth rates. Non-member loan balances stood at 167.19 trillion won at the end of June, up 4.1% from the end of last year. Associate member loans rose 3.2% to 139.22 trillion won. Member loans grew 1.4% to 93.76 trillion won over the same period.
As a result, the member share of total lending fell to 23.4% at the end of June from 23.8% at the end of last year. Associate members and non-members accounted for 34.8% and 41.8%, respectively. The member share was 33.7% in 2015, according to the Future Strategy Research Institute at the National Agricultural Cooperative Federation. A share that once exceeded a third of all lending has fallen below a quarter in about a decade.
The shift toward non-member lending was evident at individual cooperatives. At North Seoul Nonghyup, non-member loans rose 69.4 billion won of a total 73.3 billion won increase in the first half, or 94.6%. At North Busan Nonghyup, non-member loans accounted for 76.2 billion won of a 77.3 billion won increase, or 98.6%. At Gimhae Nonghyup, non-member loans made up 42.5 billion won, or 99.9%, of the total increase.

Nonghyup says farmer membership is shrinking while demand from non-members, including corporate borrowers, is rising. Membership fell by about 60,000 to 2,027,481 last year from 2,087,359 in 2021, according to data the federation submitted to Rep. Kang Seung-kyu of the People Power Party. "With the number of farmer members steadily declining, demand from non-members such as corporate borrowers is trending higher," an official at the federation said. "To support our commercial operations and keep the cooperatives running, the banking business is necessary to some extent."
Nonghyup has also been pushing to ease the cap that limits non-member loans to 50% of total lending. But critics say the cooperatives should examine whether expanding through customers outside the membership fits their founding purpose of supporting farmers. "Nonghyup differs from a commercial bank in that it is a cooperative organization of farmers," a financial industry official said. "Associate members include local residents, but most of the lending growth is concentrated among customers other than farmer members." A senior financial industry official added that with the farming population bound to keep shrinking, it is time to reassess how the cooperatives should run their lending business.
Asset quality and profitability are also at issue. A research presentation by the federation's Future Strategy Research Institute in April found that cooperatives with a higher share of lending outside their membership tended to carry greater risk of bad loans and generate lower returns. According to Kim Jae-wook, an associate research fellow at the institute, a 10 percentage point higher share of non-member lending was associated with a non-performing loan ratio 0.2 to 0.4 percentage points higher and operating profit about 190 million to 310 million won lower.