
In real terms, Canadians’ incomes have essentially stagnated for over a decade. Contributing factors include persistently slow growth of wages and salaries, as well as high inflation starting in 2021. But an often-overlooked factor is that via rising income taxes and higher mandatory contributions to the Canada/Quebec Pension Plan governments are taking a bigger bite out of people’s incomes.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman, and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account.
- Share your thoughts and join the conversation in the comments.
- Enjoy additional articles per month.
- Get email updates from your favourite authors.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account
- Share your thoughts and join the conversation in the comments
- Enjoy additional articles per month
- Get email updates from your favourite authors
Sign In or Create an Account
Transfers from households to governments rose steadily over the past five years, from 29.7 per cent of household primary income to 33.3 per cent. In the last two years they grew by 9.8 per cent, much faster than incomes did. The government’s increased take from paycheques was led by sizeable hikes in “contributions” to social insurance plans, i.e., payroll taxes, mostly for the Canada and Quebec Pension Plans (C/QPP). Personal income taxes also accelerated, rising 12.4 per cent over the past two years, compared with 9.8 per cent in the previous two years.
Get the latest headlines, breaking news and columns.
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
A welcome email is on its way. If you don't see it, please check your junk folder.
The next issue of Top Stories will soon be in your inbox.
We encountered an issue signing you up. Please try again
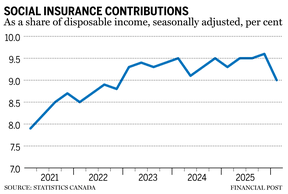
Over the past five years, the revenue raised by social insurance contributions mandated by governments rose fully 57.9 per cent, largely because of the 2018 “enhancement” to the Canada/Quebec Pension Plans, which brought both higher contribution rates and a higher maximum contribution. Bigger pension plan contributions reduced household disposable income by a full percentage point after 2021. That’s a significant amount at a time when slow income growth and high inflation were already squeezing real incomes. At $173.4 billion, social insurance contributions added almost 50 per cent to personal income taxes, which totalled $418.7 billion in 2025.
At the time, one criticism of the 2018 overhaul of the C/QPP was that higher contributions might coincide with and therefore aggravate a slump in income growth. In the event, that’s exactly what happened. Not taking a full percentage point out of disposable incomes would have helped offset the affordability crisis, especially for young people, who will not see the benefit of higher pensions for decades but face the immediate problem of being unable to buy a home and start a family. As a rule, higher pension plan contributions should only be implemented when the economy is booming, as in the late 1990s, not when it is faltering, as was the case for most of the past decade.
The hike in pension contributions also raised their take to near 10 per cent of paycheques. In his 2016 book Prisoners of Hope about the Johnson presidency in the 1960s, Randall Woods cited research by experts that found workers rebelled when contributions to social security programs exceeded 10 per cent of pay, just as they rebel when income tax rates surpass 50 per cent.
Governments now generally acknowledge that the hike in contributions to the C/QPP was unnecessarily steep. The latest actuarial studies conducted by the Office of the Superintendent of Financial Institutions have found that these pension plans were overfunded, and the contribution rate for the QPP was therefore cut in 2026, with a cut coming for the rest of Canada next year. Pension contributions fell 5.6 per cent early in 2026, though that’s small consolation for households who for years have been over-contributing even as many struggled to cover basic needs.
Governments like to claim they are trying to make life more affordable for Canadians. In 2024, the Trudeau government boasted that its $250 “Working Canadians Rebate” would put money “directly into the pockets of the middle-class — those who have worked hard to beat inflation,” while the companion temporary two-month GST/HST exemption would enable them to “buy essentials like groceries, snacks and kids’ clothing.” The reality is that such tax rebates are usually a one-time payment, while higher prices and rising taxes and pension contributions are much longer-lasting, if not permanent.
Bringing real relief to Canadians will require permanent cuts in taxes and social insurance “contributions.”
Philip Cross is a senior fellow at the Macdonald-Laurier Institute.
Join the Conversation
This website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more about cookies here. By continuing to use our site, you agree to our Terms of Use and Privacy Policy.