Business Korea · সাধারণ
SK’s ‘Bill’ for Westinghouse: How Much to Buy and What to Gain?
২১/১০/২০২৬
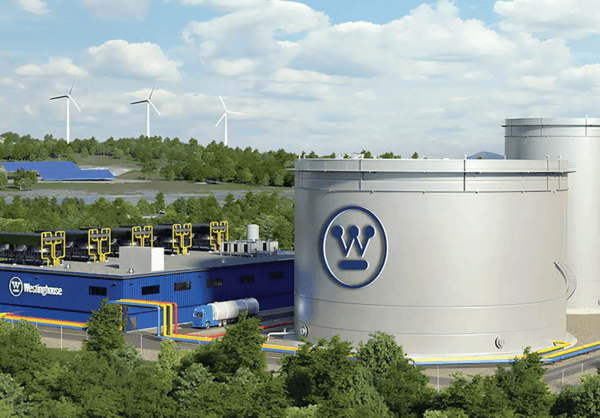
Westinghouse nuclear plant. (Photo courtesy of Westinghouse)
As SK Group reviews the acquisition of a stake in the U.S. nuclear power company Westinghouse, attention is focused on the transaction conditions that will determine the actual investment benefits. The key is how much the stake is purchased for and what business opportunities are secured.
Returns as a shareholder depend on the purchase price and the growth potential of Westinghouse. To expand the investment effects into power generation and artificial intelligence (AI) data center businesses, a separate agreement detailing joint development and operational participation is necessary.
According to the industry on Oct. 21, SK is reviewing an equity investment in Westinghouse along with Samsung C&T, Hyundai Engineering & Construction, and Doosan Enerbility. The total acquisition size of the Korean consortium is discussed to be a 5% to 10% stake, with an investment of up to around 4 trillion won (about $3.018 billion). SK’s individual investment amount, stake ratio, and business cooperation conditions have not been confirmed.
The investment returns SK can expect fall largely into two categories. One method is to gain profits from cash distribution and the increase in equity value as a shareholder of Westinghouse, or to generate revenue by participating in nuclear power plant development and operation through a separate business agreement.
First, if the stake is acquired without a separate business participation agreement, SK’s returns will primarily be linked to Westinghouse’s cash distribution and the rise in stock value. Westinghouse generates sales across the overall construction and operation of nuclear power plants, including reactor design, nuclear fuel, and maintenance. Not only new nuclear power plant orders but also the service demand arising from operating nuclear power plants are subject to evaluation.
The returns to be gained as a shareholder can be estimated in scale through past performance. Canada’s Cameco, which holds a 49% stake in Westinghouse, received a total of $220.5 million last year. This is the combined amount of $49 million in February and an additional distribution of $171.5 million related to the Czech Dukovany nuclear power project in October.
If this is simply converted in proportion to the stake ratio, the distribution per 1% stake is $4.5 million. Assuming SK held a 3% stake under the same conditions, it would correspond to $13.5 million, and if 5%, it would be $22.5 million. These are not figures estimating SK’s actual stake ratio or future receipts.
However, approximately 78% of last year’s distribution was an additional distribution related to the Dukovany project. Excluding this and using only the February receipt of $49 million as a standard, the amount per 1% stake decreases to $1 million. The amounts corresponding to 3% and 5% stakes also lower to $3 million and $5 million, respectively. Cameco also stated that it does not expect an additional distribution of a similar scale to the Dukovany project this year. This means that additional distributions arising from specific projects can significantly influence annual cash returns.
Applying the purchase price reveals a difference in the cash distribution return rate. Assuming the total stock value of Westinghouse is $30 billion, and applying a scenario where the stake is acquired at a price 10% lower than this, the purchase price for 1% is $270 million. Substituting last year’s distribution of $4.5 million per 1% stake into this, the cash return rate is 1.7%. If $1 million, which excludes the Dukovany-related additional distribution, is applied, it lowers to 0.4%. When raising the total stock value to $50 billion and applying the same discount rate, the return rates are approximately 1.0% and 0.2%, respectively.
These figures are a comparison applying hypothetical prices to past performance. They do not indicate future dividend prospects or average annual return rates, nor do they reflect stake sale gains and tax or procurement costs. To secure investment feasibility at such a price range, evidence is needed that future profit increases and equity value appreciation will lead to additional returns.
If business participation conditions are secured along with the equity investment, the scope of returns widens. In addition to the distribution received from Westinghouse, returns can also be pursued in the development and operation of power generation projects in which SK participates. The core is to go beyond the direction of cooperation and specify the projects to participate in, the roles, and the profit distribution conditions.
The previously executed investment in TerraPower serves as a reference case. SK Inc. and SK Innovation invested $250 million in TerraPower in 2022. In August this year, SK Innovation signed a term sheet with TerraPower for the development of the first commercial sodium nuclear power plant in South Korea and global expansion initiatives. They also decided to review cooperation opportunities utilizing digital twins and AI in the operation and maintenance fields. This specified the scope of business cooperation following the equity investment.
The key is whether the same connection is possible in the Westinghouse investment. There is also room to combine nuclear power technology with SK’s power generation and data center businesses. The required funds and return structure will also vary depending on whether they participate in development, invest in power generation assets, or take charge of operations.
To connect with the power demand of data centers, power securing conditions must be prepared separately. Simply holding a stake in a nuclear technology company does not allow one to receive power supply from power plants. Investments in power plants or long-term power purchase agreements are necessary. The 20-year power purchase agreement that Microsoft signed with Constellation in 2024 is an example of connecting data center power demand with a nuclear power plant restart project.
Authority as a shareholder and business rights must also be distinguished. Board participation and information access are means to understand the investment status and engage in major decision-making. Conditions for joint development or operational participation are matters to be determined in a separate business agreement.
In the current ownership structure where Brookfield and Cameco hold 51% and 49% stakes respectively, what rights the Korean consortium will secure and what authority SK will exercise among them are also subjects of negotiation. An SK Group official said, “We are reviewing various options.”
মূল প্রতিবেদনে যান ↗