- The energy impact and the strangulation of supply towards Europe
- Cascading consequences on industry, agriculture, and maritime freight
- The limitations of the Northern Sea Route (NSR) as an alternative
On repeated occasions we have focused on what is happening both in the vicinity of the Strait of Ormuz and in Bab el-Mandeb, and the consequences this holds for us.
Despite various attempts to restore normality to the area, an agreement to stabilise the region — something that would take several months to take effect, even if struck tomorrow — is far from being a reality, let alone a possibility. And more concerningly: everything indicates that the situation's trend is worsening. Therefore, today we will delve even deeper into the problem of the straits.
International trade, within our globalised world context, maintains a structural dependency on maritime transport, channelling over 80% of the global volume of goods via this route.

The logistic architecture interconnecting production centres in East Asia and the primary hydrocarbon exporting hubs of the Middle East with Europe's consumer markets and industries rests upon a set of bottlenecks or choke points, depending entirely on their transitability.
Amongst what we might consider the naval arteries carrying the vital elements that keep the world functioning, the Strait of Ormuz and the Strait of Bab el-Mandeb represent the most critical energy and general cargo nodes on the planet.
The Strait of Ormuz constitutes the most critical point of global oil traffic. Approximately 20 million barrels per day of all types of petroleum derivatives, including crude, condensates, and refined products, transit its waters, accounting for nearly 20% of global oil consumption and 25% of world maritime hydrocarbon trade.

Likewise, the strait channels roughly 11.4 billion cubic feet per day (Bcf/d) of liquefied natural gas (LNG), equivalent to over 20% of global LNG trade, originating primarily from Qatar's export plants.
Meanwhile, the Strait of Bab el-Mandeb operates as the key southern access towards the Red Sea and the Suez Canal. Under normal operating conditions, this passage absorbs between 12% and 15% of world maritime trade and approximately 15% of global container traffic.
In the energy sphere, flow through Bab el-Mandeb historically reached close to 8.8 million barrels per day of crude and derivatives, although effects caused by instability in the Red Sea reduced this volume to approximately 4.2 million barrels per day in the first half of 2025, as numerous shipping lines decided to divert their routes towards the path skirting the Cape of Good Hope.

The energy impact and the strangulation of supply towards Europe
The eventuality of a simultaneous disruption, whether total or partial, in both straits would expose the European economy to an unprecedented supply shock in all history. The combined disconnection of the Persian Gulf's primary gas and crude source, alongside the paralysis of the most direct maritime route between Asia and Europe, would demand an immediate restructuring of capital, energy, and industrial logistics flows, with the consequent increase in both costs and time.
A total or partial closure of Ormuz would entail a strangulation of global hydrocarbon supply by neutralising the maritime outlets of Saudi Arabia, the United Arab Emirates, Iraq, Kuwait, Qatar, and Iran. Indeed, that is the scenario we have been living through for several months.
Although pipelines designed to bypass the strait exist — most notably the East-West Petroline pipeline in Saudi Arabia, with a theoretical capacity of 4.7 to 5.0 million barrels per day, and the Abu Dhabi Crude Oil Pipeline (ADCOP) in the UAE at 1.5 million barrels per day —, the combined usable bypass capacity does not exceed 6.5 million barrels. This means that over 13 million barrels of daily crude and all 11.4 Bcf/d of LNG exports fail to reach the market.

For the European market, the interruption of Qatari LNG, which contributes close to 30 million tonnes annually to the global market and satisfies a critical share of Western Europe's demand, generates an immediate and irreplaceable deficit.
When the closure of Bab el-Mandeb is added, the reduced volumes of Saudi crude managing to reach the port of Yanbu on the Red Sea cannot access the Mediterranean via Suez directly either, forcing the circumnavigation of the African continent. And this assumes the Houthis halt their actions against these facilities and allow normality to be restored.

The direct economic impact manifests as a constant instability in Brent crude prices, with a clearly bullish trend that could drive quotations above $120 to $150 per barrel in the short term, accompanied by spikes of over 200% in natural gas prices at the Netherlands' TTF (Title Transfer Facility) node.
This energy escalation, if unchecked, will reactivate inflationary pressures on the Harmonised Index of Consumer Prices (HICP) in the euro area, undermining household purchasing power and forcing central banks to tighten monetary conditions.
Nor can it be overlooked that we are entering a time of year where gas consumption for heating is necessary, if not essential, for a large part of the European population.

Cascading consequences on industry, agriculture, and maritime freight
Yet other key sectors are suffering the consequences of this perfect storm, and one of them is European manufacturing industry. This sector runs the risk of experiencing a cascading disruption due to a lack of intermediate inputs. Petrochemical complexes located along the Rotterdam-Antwerp-Rhine axis depend on naphtha, condensates, and basic chemicals originating from Persian Gulf refineries.
Significant reduction, or even interruption, of these supplies results in forced capacity reductions in the production of polymers, synthetic resins, and elastomers, directly impacting the automotive, packaging, and construction value chains.
Simultaneously, the European industrial sector, due to Red Sea transitability issues, suffers the consequences of structural delivery delays for electronic components, machinery parts, and industrial inputs sourced from China, South Korea, Taiwan, and Vietnam. With container ships forced to bypass Bab el-Mandeb and the Suez Canal, additional transit time is having a severe negative impact on just-in-time production systems, compelling European manufacturing plants to accumulate costlier safety inventories or paralyse assembly lines due to shortages of key components.

And we must bear in mind that we are not yet feeling the full effects of actions around Bab el-Mandeb. Several weeks or months typically pass from the onset of problems until the impact reaches Europe, allowing us to state with certainty that the worst is yet to come. Likewise, should the situation be resolved, whether in Ormuz or Bab el-Mandeb, results will take time to show.

The impact on the European agri-food sector is perceived through two main mechanisms: soaring fertiliser prices and shortages of agricultural raw materials.
The synthesis of nitrogen fertilisers (such as urea and ammonium nitrate) requires natural gas as a fundamental raw material via the Haber-Bosch process. The peak in TTF gas prices is drastically driving up production costs for fertiliser plants across the European Union, forcing temporary facility shutdowns as occurred in prior energy crises.
In turn, the disruption of traffic through Bab el-Mandeb is affecting the direct flow of key inputs from Asia and the Middle East, such as Qatari urea and the phosphates and potash transiting towards the Mediterranean.

The cumulative increase in fertiliser costs, estimated at over 100%, inevitably translates into operating costs for European farmers, reducing nutrient usage, lowering cereal and oilseed crop yields, and passing double-digit price hikes onto processed foods in European supermarkets.
That is to say, the ultimate consequence of everything we have described thus far — and these are facts, not mere speculation — is borne by consumers, who face near-unaffordable prices across all manner of consumer goods and basic necessities.
The impossibility of using the Bab el-Mandeb, Red Sea, and Suez route alters the efficiency of global maritime traffic. The Shanghai-Rotterdam route via Suez spans roughly 8,440 nautical miles (nm), a distance rising to 11,720 nm when skirting the Cape of Good Hope, representing a 39% increase. At a commercial speed of 15 knots, this detour adds between 12 and 14 days (moving from 22-24 days to 34-38 days), extending the complete round-trip rotation by nearly a month.

From a shipping perspective, the need to maintain weekly services with voyages 55% longer in duration absorbs between 8% and 10% of the global container fleet capacity, creating an artificial shortage of available space.
Although ships save Suez Canal tolls, which range between $336,000 and $784,000 per transit for large vessels, fuel consumption increases by approximately 30% (roughly 840 additional metric tonnes per voyage), adding over $700,000 in bunker costs per journey based on average prices.
The net result is a rebound in freight rates (reflected in the Shanghai Container Freight Index - SCFI) and the application of route disruption surcharges, raising the final cost of imported consumer goods (electronics, textiles, footwear, and homeware) in the European market.

The limitations of the Northern Sea Route (NSR) as an alternative
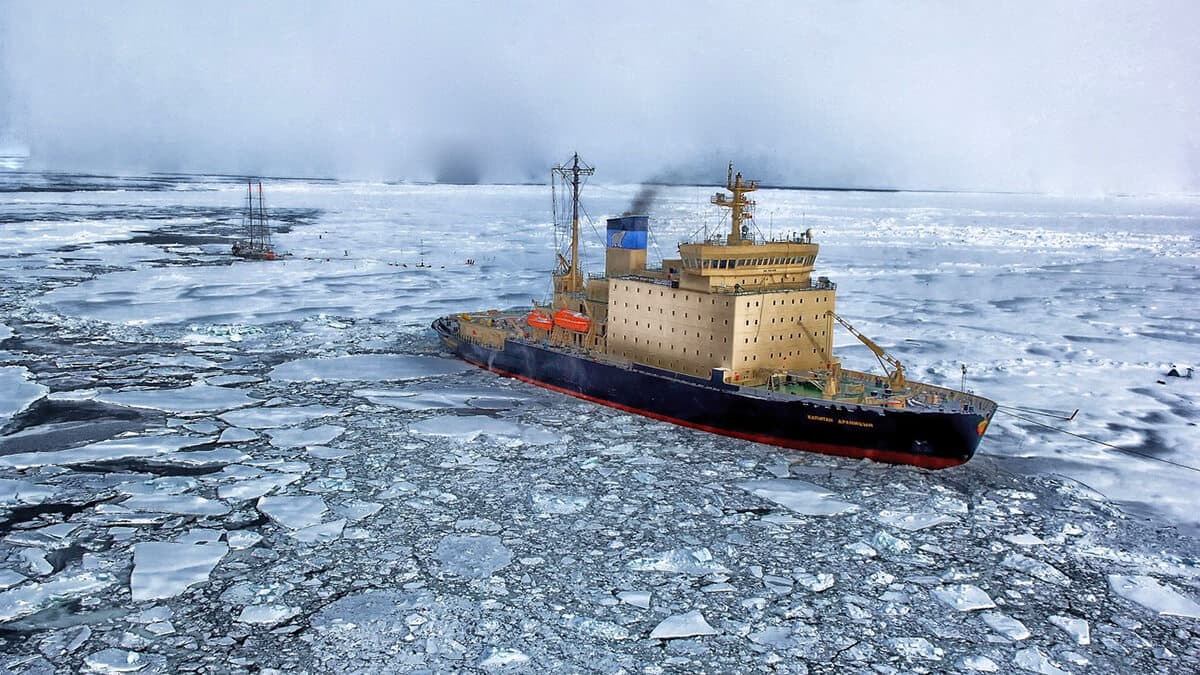
Against this backdrop, greater use of the Northern Sea Route (NSR), which skirts Russia's Arctic coast from the Kara Strait to the Bering Strait, is increasingly discussed and tabled, repeatedly proposed as a commercial alternative to traditional route vulnerabilities.
In purely geographical terms, the NSR offers distance cuts for trade between Northeast Asia and Northwest Europe:
- Yokohama-Rotterdam Route: Distance is reduced from 11,133 nm via Suez (and 14,448 nm via the Cape) to just 7,010 nm through the Arctic, representing a distance saving of between 37% and 51%.
- Shanghai-Rotterdam Route: The journey goes from 10,320–11,720 nm via traditional paths to approximately 8,280 nm via the NSR, cutting distance by between 27% and 30%.
Regarding navigation times, an Arctic journey between China and Northern Europe takes between 18 and 20 days at standard speeds, compared to the 34 to 38 days required to skirt Africa.

Despite savings in nautical miles, the NSR's capacity to mitigate a closure of Ormuz and Bab el-Mandeb is marginal due to physical, logistic, and geopolitical bottlenecks.
Yet advantages do not tell the whole story. Firstly, there are severe bathymetric restrictions. The Sannikov Strait and the Laptev Strait impose a maximum draught limit of 13 metres. This condition absolutely excludes large Neo-Panamax and ULCV class container ships (from 14,000 to 24,000 TEU), which require draughts between 14.5 and 16 metres. Navigation on the NSR is restricted to small and medium-sized vessels (Feeder and Supramax from 2,500 to 4,800 TEU), a factor with a devastating effect on the economies of scale underpinning mass Asia-Europe trade.
Secondly, ice seasonality imposes reduced operational windows. Despite Arctic warming, safe navigation without heavy ice is limited to a period of 90 to 120 days per year (from July to October or early November). Outside this period, transit requires the support of nuclear-powered icebreakers from the Russian state company Rosatom, with toll and escort costs exceeding Suez Canal tariffs by up to 80%.

Thirdly, the geopolitical and international sanctions framework limits the commercial adoption of this route. Since the NSR runs through Russia's EEZ and territorial waters, Western shipowners face legal restrictions on making tariff payments to sanctioned Russian entities, as well as the refusal of international insurers within the International Group of P&I Clubs to grant universal cover for vessels transiting the region.
In volume terms, in 2024 the NSR recorded record traffic of 37.9 million tonnes, of which only 3.0 million corresponded to international transit. In 2025, volume stood at 37.02 million tonnes, with 3.2 million tonnes of transit and some 400,000 tonnes of containerised cargo driven by Chinese operators. Compared to the over 1.2 billion tonnes transiting the Suez Canal in normal years, the NSR absorbs less than 0.5% of containerised trade between Asia and Europe.
As we can see, despite being touted as an alternative route, the NSR remains a long way from mitigating the problems caused by the Middle East situation, leading us to assume that even harder times lie ahead, with fuel prices, for example, hovering above the €2.5 per litre level and likely closer to €3 around the Christmas holidays.
In forthcoming installments, we shall examine how this entire situation affects another strait where tension has mounted in recent months and which strikes very close to home: Gibraltar.