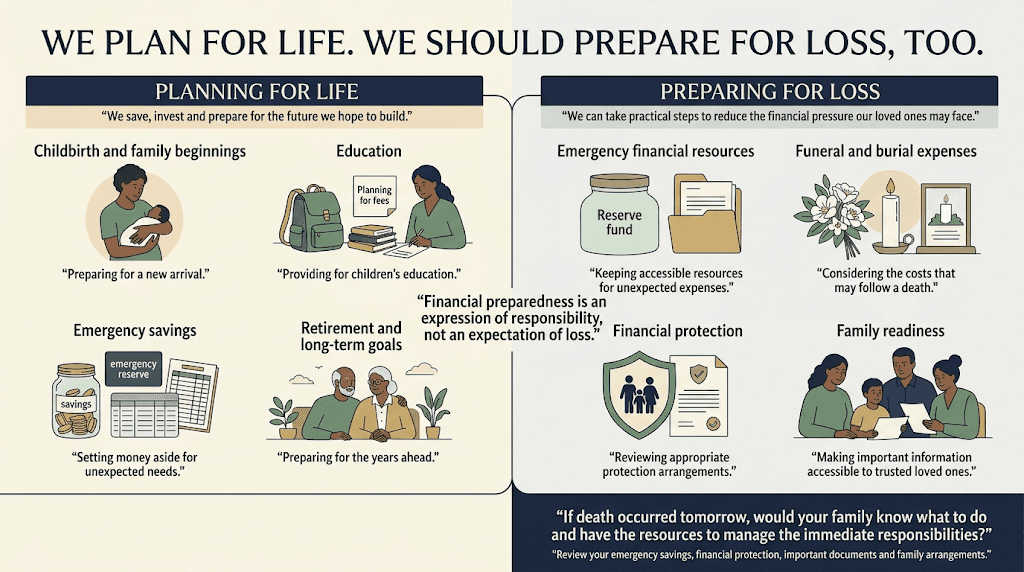
When a family is expecting a child, preparations often begin months before the baby arrives. Parents budget for hospital bills, delivery, baby clothes and other necessities. Some even begin saving for school fees long before the child is old enough to speak.
These preparations are driven by responsibility. Parents understand that a new life comes with financial obligations, and they do their best to prepare.
Yet, when it comes to death, many families take a different approach. Because nobody knows when it will happen, we often leave the financial implications to chance. The subject is uncomfortable, so we postpone the conversation until circumstances force us to confront it.
Unfortunately, avoiding the conversation does not eliminate the responsibilities that follow.
When grief meets financial pressure
A client once contacted me about liquidating an investment to meet an urgent family need. His mother had been hospitalised for some time, and the medical expenses had become overwhelming. What began as an effort to secure her recovery had gradually consumed the family’s available resources.
There was no way to know how long the treatment would last or what the eventual outcome would be. Like many families, they were doing everything they could to care for someone they loved.
Sadly, his mother passed away. The family was then confronted with another financial responsibility: her burial expenses.
Beyond the grief of losing a parent, there was the pressure of finding money to meet immediate obligations. The resources available to the family had already been stretched by the medical crisis, and the burial introduced another expense at an exceptionally difficult time.
This experience highlights a reality many families face. An unexpected illness can disrupt financial plans, deplete savings and place investments under pressure. When death follows, funeral expenses can deepen the burden.
The lesson is not that families should avoid spending money to care for loved ones. It is that even when we do everything possible, we cannot always control the outcome. Preparing financially can help families manage the responsibilities that follow without placing the entire burden on whoever is available to pay.
Death has financial consequences too
Financial planning conversations often focus on growing wealth, buying property, paying school fees, investing and preparing for retirement. These are important goals, but a complete financial plan should also consider how a family would cope with death.
Depending on the circumstances, surviving family members may have to meet burial expenses, settle outstanding obligations, maintain household expenses and provide for dependants. Without readily available funds, they may be forced to borrow, sell assets hastily or liquidate long-term investments at an inconvenient time.
The consequences can extend beyond the immediate expense. Money intended for a child’s education may be redirected. Retirement savings may be depleted. A surviving spouse or adult child may suddenly find themselves carrying responsibilities they were not financially prepared to shoulder.
Financial preparedness should therefore be measured not only by how much we earn, save or invest, but also by how well our finances can withstand difficult and unexpected events.
Preparing for life’s uncertainties
One practical step is to establish an emergency fund that can help cover unexpected expenses. However, emergency funds often have several competing demands, including medical emergencies, temporary loss of income and other unforeseen needs. They may not be sufficient to cover every financial shock.
Families can also explore appropriate financial protection arrangements, including insurance, as part of a broader plan. The important thing is to understand what any arrangement covers, its limitations and whether it meets the family’s needs and budget.
Other practical measures include keeping important financial documents accessible to trusted family members, making appropriate provisions for dependants, reviewing existing financial protection and ensuring that loved ones know whom to contact when assistance is needed.
These steps cannot remove the pain of losing someone. They can, however, reduce some of the financial confusion and pressure that may accompany the loss.
Give your family the gift of preparedness
Planning for death is not wishing for it to happen. Neither is it a substitute for living fully, caring for loved ones or investing in the future. It is an acknowledgement that responsible financial decisions must account for more than the events we hope to experience.
As you save for your children’s education, build an investment portfolio, prepare for retirement and establish an emergency fund, consider another question: if death occurred tomorrow, would your family have the financial resources and information needed to manage the immediate responsibilities?
If the answer is no, it may be time to review your financial plan.
We cannot determine exactly when a loved one will leave us, and no amount of financial preparation can make bereavement easy. But we can take steps to ensure that those we love are not left to navigate grief and financial pressure without support.
We plan for the arrival of life because we understand that preparation is an expression of responsibility. Perhaps it is time to extend that same responsibility to life’s inevitable end.
A thoughtful financial plan should prepare your family not only for the life you hope to build together, but also for the responsibilities they may face when you are no longer there.
Related News

