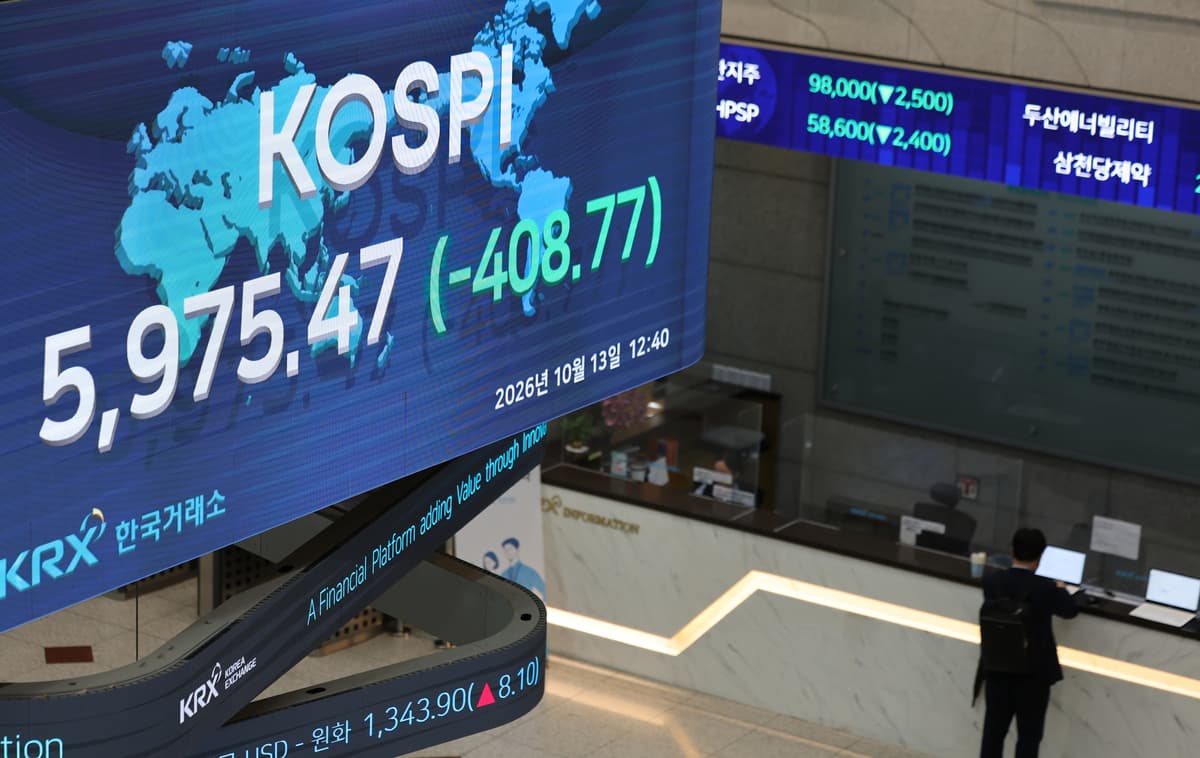
The KOSPI closed at 6,035.35 on the 13th, down 5.5% from the previous session, after a sell-side sidecar was triggered intraday for the first time in two months. The index narrowly held the 6,000 line, but a sell-off centered on chip stocks has pushed it down nearly 14% over five trading sessions. The shock is all the greater because the plunge came after Samsung Electronics (005930.KS) reported record third-quarter operating profit of more than 107 trillion won.
Unlike major markets elsewhere, Korea's bourse fell especially sharply, weighed down by the advance of Chinese chipmakers and debate over whether the semiconductor cycle has peaked. The environment facing Korea's chip industry is anything but easy. China's ChangXin Memory Technologies (CXMT) said recently it plans to release an advanced memory module within this year that can yield more chips from a single wafer. U.S. big tech firms including Microsoft and Amazon are also moving to expand their own artificial intelligence chips. These are factors that could fundamentally shake a chip market now tilted in favor of suppliers.
The International Monetary Fund on the same day raised its forecast for Korea's economic growth this year to 3.3% from 2.6%. Major global institutions have been lifting their forecasts for Korea's growth this year into the 3% range, citing strong semiconductor performance. Yet the country's reliance on a single industry is excessive, adding to uncertainty in both financial markets and the real economy. The IMF advised the Korean government to secure fiscal room for a future economic crisis rather than spend the tax revenue gained from the chip boom right away. It is a warning to prepare for the possibility that the memory chip boom driven by AI investment will turn, and to get ready for a post-semiconductor era. Changyong Rhee, the former Bank of Korea governor, also voiced concern recently about the government's expansionary fiscal stance, which leans on the semiconductor super cycle.
This is a time for clear-eyed preparation against risks, not premature celebration. The government must recognize the limits of an economy pulled by chips alone and devote all its efforts to building up the drivers that can sustain growth. Additional tax revenue should be directed to supporting future growth rather than to excessive cash handouts. Uniform regulations that hold back investment, such as the so-called yellow envelope law on labor disputes and the 52-hour workweek, should also be lifted. Now is the time not to waste the time the chip industry has bought, but to mount an all-out push to add new growth engines.