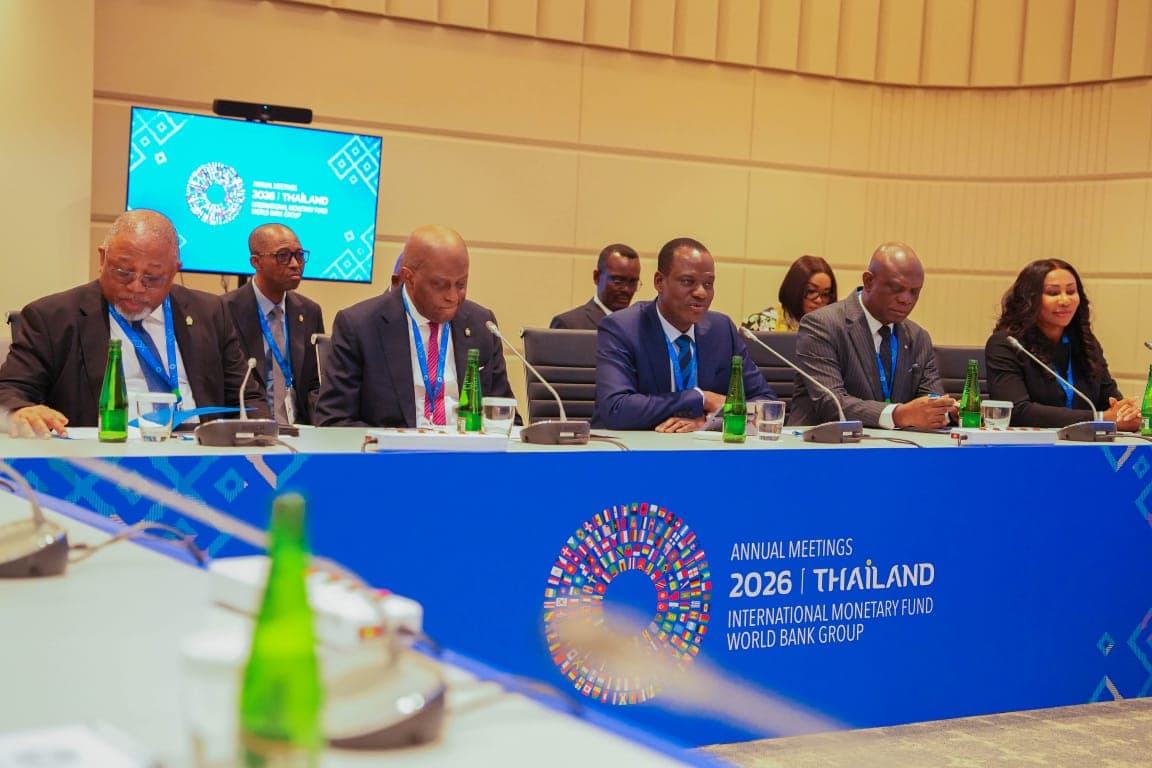
The Federal Government has identified power infrastructure and human capital development as key priorities for public investment as Nigeria seeks to translate recent macroeconomic stability into faster economic growth, increased private investment and job creation.
Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, alongside the Governor of the Central Bank of Nigeria (CBN), Olayemi Cardoso, disclosed this after a meeting with the President of the World Bank Group, Ajay Banga.
TheNewsGuru (TNG) reports that the meeting took place on Monday on the sidelines of the 2026 International Monetary Fund (IMF) and World Bank Group Annual Meetings in Bangkok, Thailand.
Oyedele is leading Nigeria’s delegation to the annual meetings, which provide a platform for discussions on the country’s economic reforms, investment prospects and engagement with international development partners.
TNG gathered that the meeting reviewed Nigeria’s reform progress and the next phase of the government’s economic agenda. Discussions focused on how to convert macroeconomic stability into stronger economic growth, attract more private capital and increase domestic revenue.
Banga commended the progress of Nigeria’s reforms, highlighting the significant increase in private capital inflows into the country.
He noted that private capital inflows had risen from about $300 million in 2023 to nearly $6 billion in 2026, representing an approximately 20-fold increase.
Oyedele also highlighted the country’s rising economic growth and improvements in revenue generation, noting that Nigeria’s tax-to-GDP ratio had increased from about seven per cent to 12.5 per cent over the same period.
The minister said the improved revenue position gives the government greater capacity to finance public investment without resorting to deficit monetisation.
The meeting also explored ways Nigeria could leverage World Bank guarantee instruments to mobilise financing for critical infrastructure projects and attract additional private capital into the domestic market.
Such guarantees are expected to help unlock financing for projects that require substantial investment, particularly in sectors where infrastructure gaps constrain economic activities and private-sector expansion.
Power infrastructure and human capital development were identified as priority areas for sustained public investment because of their importance to business competitiveness, productivity and employment generation.
The discussions further emphasised the need to improve the quality of public spending, ensuring that government expenditure produces measurable economic and social benefits.
The Federal Ministry of Finance said the meeting formed part of the government’s broader engagement with development partners to consolidate the gains of ongoing reforms and attract fresh investment into the economy.
It added that Nigeria’s next priority was to translate stronger economic fundamentals into productive investment, more employment opportunities and improved living standards for citizens.