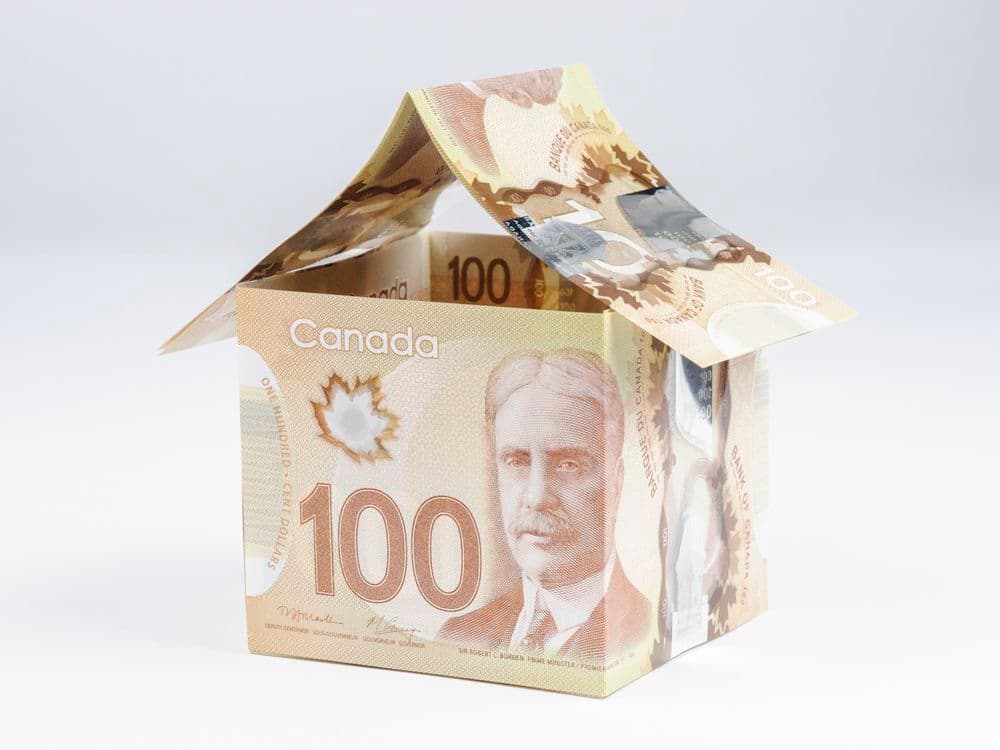
Canada’s biggest reverse mortgage lender is betting that for a growing number of near-retirees, traditional borrowing limits just don’t cut it.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman, and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account.
- Share your thoughts and join the conversation in the comments.
- Enjoy additional articles per month.
- Get email updates from your favourite authors.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account
- Share your thoughts and join the conversation in the comments
- Enjoy additional articles per month
- Get email updates from your favourite authors
Sign In or Create an Account
That’s the thinking behind HEB Advantage, which HomeEquity Bank is launching at the end of October.
The product lets homeowners aged 55 to 70 unlock a lump sum of up to 59 per cent of their home’s value with a unique hybrid loan structure.
For the first 10 years, borrowers pay monthly interest on part of the loan, after which required payments vanish completely.
SUBSCRIBER EXCLUSIVE: FP West: Energy Insider brings you behind the oilpatch’s closed doors with exclusive insights from insiders every Wednesday morning.
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
A welcome email is on its way. If you don't see it, please check your junk folder.
The next issue of FP West: Energy Insider will soon be in your inbox.
We encountered an issue signing you up. Please try again
It’s designed for house-rich, cash-flow-poor early retirees, gig workers, the self-employed, and semi-retirees — basically any homeowner in that age bracket who needs more cash than a traditional reverse mortgage offers, but whose debt service ratios turn conventional lenders off.
“It appears to address one of the biggest gaps in the reverse mortgage market,” said reverse mortgage expert Rebecca Awram of Indi Mortgage. “Borrowers who need more equity than their age allows them to access.”
Not a lot of options
Today, the best alternative to this product would theoretically be a prime home equity line of credit (HELOC), assuming the borrower could qualify and didn’t need to borrow the majority of their equity.
But as HomeEquity Bank CEO Yousry Bissada puts it, “advantage is not replacing the HELOCs of the world.”
It’s more for people who don’t want bigger HELOC payments, or can’t qualify for one at all.
A quick example
Picture a 60-year-old homeowner sitting on an $835,000 property who maxes out at $349,500 with a regular reverse mortgage.
HEB Advantage bumps that borrowing limit to $470,000 — putting about 35 per cent more cash in his pocket.
But banks aren’t charities, so the extra cash comes at a cost.
Advantage rates run about 0.60 percentage points higher on fixed terms and 0.25 points higher on variables, compared to standard CHIP loans.
At a 7.29 per cent three-year fixed rate, our imaginary borrower forks over $1,426 a month, per HomeEquity Bank’s illustration.
At first glance, that deal looks like a steal:
- The monthly payment is 48 per cent lower than an alternative lender’s 6.95 per cent HELOC.
- It’s 26 per cent lower than a prime HELOC at 4.95 per cent.

Just don’t mistake a smaller monthly bill for a cheaper loan.
That $1,426 covers only about half the monthly interest; the unpaid half quietly compounds in the background.
If rates theoretically held steady for a decade, that $470,000 debt would balloon to $712,000.
Meanwhile, a HELOC borrower dutifully paying all their monthly interest would still owe the original $470,000.
Where Advantage earns its keep is by undercutting the costly workarounds some cash-strapped 55-plus borrowers resort to:
- Grabbing an expensive non-prime loan or HELOC
- Maxing out a regular reverse mortgage and then bolting on a pricey private second mortgage (we’ll call this “RM + 2nd”).
The interest rate and/or payment on non-prime HELOCs is often a deal-killer, so we’ll focus here on the RM + 2nd.
HomeEquity Bank generally frowns on second mortgages behind its loans, but some borrowers add one anyway.
If we crunch the numbers on the RM + 2nd, you’re looking at a 6.69 per cent three-year CHIP for the first $349,500, plus a 12 per cent interest-only private second on the remaining $120,500.
On top of that, there’s an upfront lender/broker fee (typically around 2.5 per cent) on the second, plus one per cent to three per cent in renewal fees every one to five years.
The RM + 2nd’s monthly outlay looks gentler at $1,205 (you’re only paying interest on the second mortgage), but the unpaid CHIP interest stacks up like unopened mail.
A decade in, the RM + 2nd borrower owes about $795,000, roughly $83,000 more than the Advantage borrower.
Even with lower monthly payments, the lender fees and compounding interest mean the RM + 2nd route could still cost $70,000 more over a decade.
Plus, there’s the recurring migraine of hunting down new private lenders and paying fresh legal, appraisal and closing fees every one to five years.
A key motive for this product
All this financial engineering speaks to a broader truth: Canadians aren’t saving like they used to.
The household saving rate was 3.7 per cent in the second quarter, down from 5.3 per cent in early 2025 and roughly half the 7.4 per cent historical average since 1961, according to Trading Economics.
Only a third of Canadians contributed to an RRSP for the 2025 tax year, per Narrative Research, and a BMO poll found two-thirds agree it’ll be harder to save for retirement than it was for their parents.
So, when the nest egg comes up short, the nest itself has to pick up the tab.
Of course, ideally, people would stash more cash for retirement, but Canada’s oppressive cost of living and tax regime turn that into an uphill sprint.
Advantage can help bridge those shortfalls, while addressing a key drawback of reverse mortgages: too little upfront cash to pay off other debts and still have some left over.
Good HELOCs still rule
If you can pass the government stress test and qualify for a sufficient prime HELOC, take it and don’t look back.
With enough borrowing room, you can even cover the monthly interest from the HELOC itself to help with cash flow. But talk to a mortgage broker and choose the right lender, as some banks are more tolerant of people making endless interest-only payments than others.
By the way, mention that to a personal finance guru and they may shriek at the thought of paying debt with debt, but that’s basically how a reverse mortgage works anyway.
At least when you capitalize HELOC interest payments, you have a chance at saving more money because the rate is much lower.
The other HELOC trick is, you have to be careful to leave yourself enough borrowing room to pay the interest for a long time.
And you do go the line of credit route, try to keep it small enough so you can pay it off with a reverse mortgage later, if needed. A financial planner or mortgage professional can model the maximum HELOC amount you should stay under to make that work.
For homeowners who can’t solve their problems with a conventional mortgage or HELOC, Advantage offers a pragmatic, if pricey, middle ground: you sacrifice more of your estate tomorrow in exchange for a bigger cheque today — plus easier approval, and a firm retirement date for your monthly payments.
Robert McLister is a mortgage strategist, interest rate analyst and editor of MortgageLogic.news. You can follow him on X at @RobMcLister.
For the best national insured and uninsured mortgage rates, updated daily, please visit our mortgage rate page here.

Join the Conversation
This website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more about cookies here. By continuing to use our site, you agree to our Terms of Use and Privacy Policy.