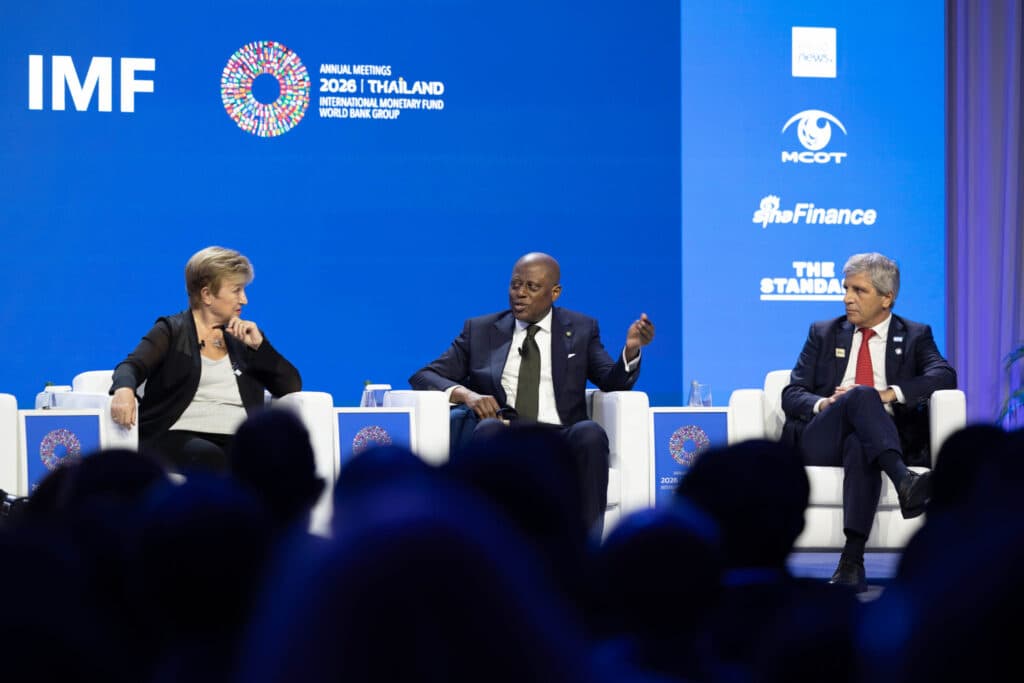
Olayemi Cardoso, governor of the Central Bank of Nigeria (CBN) says Nigeria’s monetary and foreign-exchange reforms have strengthened the country’s ability to withstand external economic shocks, while creating opportunities to attract investment and diversify foreign-exchange earnings.
Cardoso stated this on Thursday during a high-level discussion at the International Monetary Fund (IMF) Annual Meetings in Bangkok, where global economic leaders examined the risks confronting the world economy and the reforms required to sustain growth.
The session, Debate on the Global Economy: Forging Resilient and Dynamic Economies for the Future, featured IMF Managing Director Kristalina Georgieva, Eurogroup President and Greek Finance Minister Kyriakos Pierrakakis, Thailand’s Deputy Prime Minister and Finance Minister Ekniti Nitithanprapas, and Argentina’s Economy Minister Luis Caputo.
Moderated by Lisa Abramowicz, a journalist with Bloomberg the discussion focused on fiscal discipline, economic diversification, regional integration and investment as countries contend with inflation, rising borrowing costs and geopolitical uncertainty.
Cardoso noted that Nigeria’s experience over the past three years had reinforced the importance of consistent policies and decisive reforms in restoring economic stability and market confidence.
He recalled that the country had faced a severe foreign-exchange crisis, with net external reserves falling to approximately $3 billion at one point and outstanding foreign-exchange obligations exceeding $7 billion.
The situation required significant monetary and foreign-exchange adjustments, including aggressive interest-rate increases, the harmonisation of foreign-exchange windows and measures to improve transparency and market functioning.
Cardoso said these actions, alongside wider economic reforms, helped restore investor confidence, clear verified foreign-exchange obligations and strengthen reserves to their highest level in 18 years.
Reas also: CBN and finance ministry pitch $78.5bn infrastructure pipeline at IMF-World bank meetings
He explained that Nigeria’s inflation experience differed from those of many other countries because foreign-exchange and subsidy reforms had created additional price pressures when much of the world was easing monetary policy.
He said those conditions informed the CBN’s aggressive tightening programme in 2024 and its subsequent decision to reduce the benchmark interest rate in September 2026.
Cardoso noted that the adjustment was necessary to address weaknesses in monetary policy transmission and was absorbed without major market disruption because investors understood the Bank’s policy direction.
He also highlighted the CBN’s efforts to reduce Nigeria’s dependence on oil-related foreign-exchange inflows through increased diaspora remittances.
“When you are going through a crisis, it forces you to be creative,” he said.
According to Cardoso, the Bank engaged Nigerians abroad and international financial institutions to identify obstacles to remitting funds through formal channels.
The engagements informed changes to existing processes, including digital improvements, while a committee chaired by the Governor worked with commercial banks to implement the initiative.
He said monthly inflows increased from approximately $200 million to $600 million during the first year of the intervention, before reaching nearly $950 million in July 2026.
The CBN’s reported July figure of $947 million brought the country closer to its target of attracting $1 billion in monthly remittances through formal channels.
Cardoso said the experience demonstrated the potential for practical institutional reforms to expand foreign-exchange inflows and strengthen the country’s external position.
On economic diversification, he cited the development of domestic refining capacity, particularly the Dangote refinery, as an important step towards greater value addition and reduced dependence on exporting raw materials.
The Governor also pointed to renewed international market recognition, including Nigeria’s return to FTSE Russell’s frontier-market classification and the inclusion of Nigerian government bonds in a J.P. Morgan emerging-market benchmark.
His remarks came as Georgieva warned that the global economy’s resilience was increasingly under pressure from elevated debt, geopolitical disruption, inflation and growing disparities between countries benefiting from artificial intelligence investment and those being left behind.
The IMF Managing Director said governments needed to rebuild financial buffers and strengthen economic fundamentals rather than assume that recent global growth would continue uninterrupted.
Other panellists offered perspectives on the same challenge. Pierrakakis highlighted the importance of fiscal discipline and deeper European market integration, while Thailand’s Nitithanprapas described investments in regional energy networks, digital infrastructure and skills development.
Caputo outlined Argentina’s fiscal reforms and investment incentives, emphasising the importance of predictability and sound economic management in attracting private capital.
Asked about Nigeria’s role in encouraging investment across Africa, Cardoso said larger economies had a responsibility to demonstrate the value of sound economic policies and sustained reform.
He pointed to improving international market assessments as evidence of the progress Nigeria had made, while emphasising the need to maintain the country’s policy direction.
“We need to stay on that course,” he said, adding that demonstrating results was more important than making declarations.
Cardoso’s contribution situated Nigeria’s recent monetary reforms and efforts to diversify foreign-exchange inflows within the wider international discussion on how countries can strengthen economic resilience, attract productive investment and withstand future global shocks.
Related News

