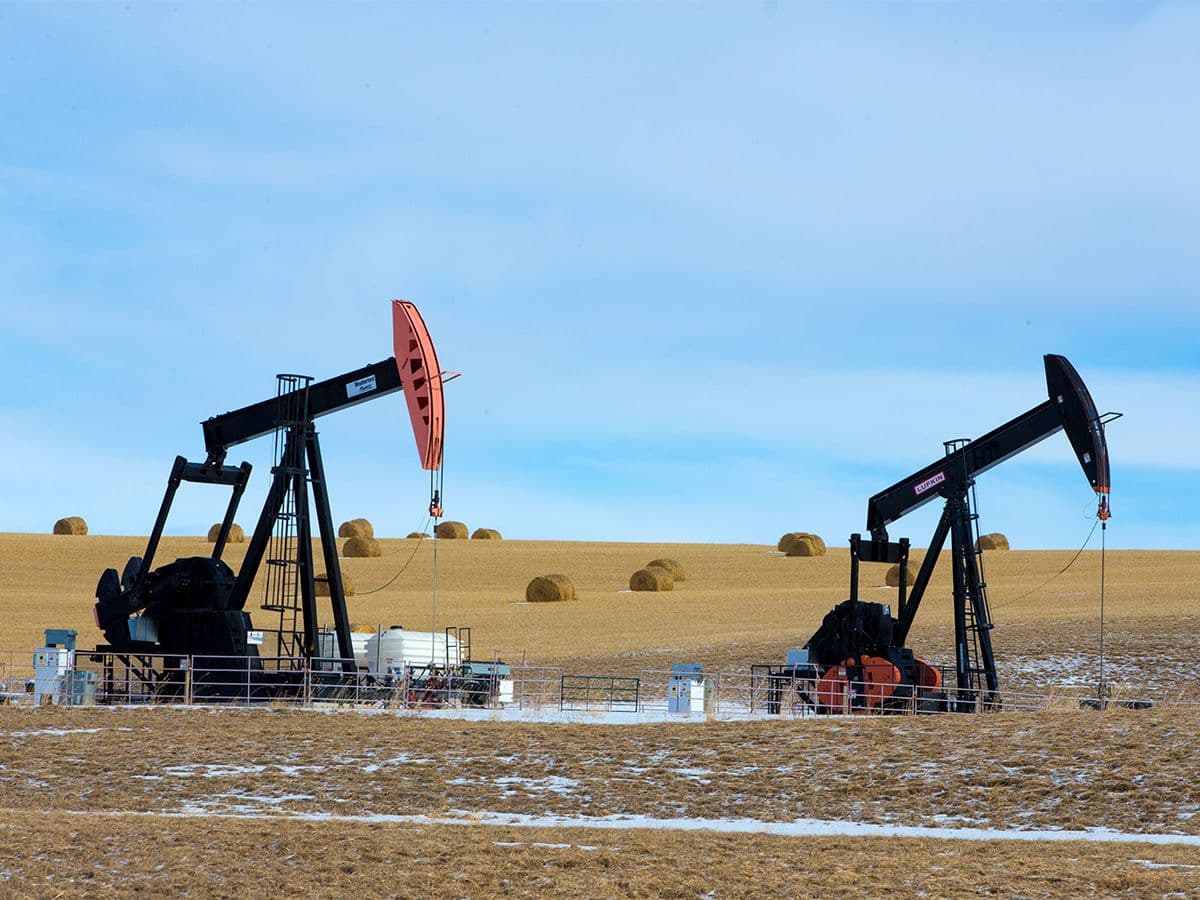
Canadian oil producers are set to unleash “epic” third-quarter financial results in the coming weeks, powered by supercharged energy prices, setting the table for a potential debt-free twist.
Subscribe now to read the latest news in your city and across Canada.
- Unlimited online access to articles from across Canada with one account.
- Get exclusive access to the Calgary Herald ePaper, an electronic replica of the print edition that you can share, download and comment on.
- Enjoy insights and behind-the-scenes analysis from our award-winning journalists.
- Support local journalists and the next generation of journalists.
- Daily puzzles including the New York Times Crossword.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account.
- Share your thoughts and join the conversation in the comments.
- Enjoy additional articles per month.
- Get email updates from your favourite authors.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account
- Share your thoughts and join the conversation in the comments
- Enjoy additional articles per month
- Get email updates from your favourite authors
Sign In or Create an Account
It will leave some of the largest producers with plenty of cash and the ability to have little or no net debt on their books over the coming year, analysts say — while allowing them to bankroll new growth initiatives or pursue other options.
“It’s clear that these companies are going to be generating just an epic level of free cash flow, and we see that continuing into 2027. And they, frankly, have a cash problem,” said Eric Nuttall, a senior portfolio manager with Ninepoint Partners, which holds shares in Cenovus Energy and Suncor Energy.
SUBSCRIBER EXCLUSIVE: FP West: Energy Insider brings you behind the oilpatch’s closed doors with exclusive insights from insiders every Wednesday morning.
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
A welcome email is on its way. If you don't see it, please check your junk folder.
The next issue of FP West: Energy Insider will soon be in your inbox.
We encountered an issue signing you up. Please try again
“They’re generating too much of it, and they don’t know what to do with it . . . Some companies are approaching debt-free status in 2027,” Nuttall said Thursday.
“It’s not really part of the business model to build cash, so we think you will see a combination of ongoing share buybacks combined with organic growth next year, which is a bit of a shift versus the past couple of years.”
The four largest oil producers in the country — Canadian Natural Resources, Cenovus Energy, Imperial Oil and Suncor Energy — are projected to collectively generate free funds flow (before paying out dividends) in the third quarter of $13.5 billion, said a new report.
“Canada’s majors are printing money, and we do not recall ever having seen this degree of collective balance sheet strength,” states the report by analyst Greg Pardy of RBC Capital Markets.
“What stands out most in our analysis is that net debt levels fell an estimated $5.2 billion — and appear poised to turn negative (i.e. net cash) for select producers by year-end 2026.”
RBC’s outlook says Suncor’s net debt is expected to sit around $1.8 billion at the end of the third quarter, excluding capitalized leases, “and appears poised to become net cash in the fourth quarter of 2026.”
The report says Imperial Oil’s balance sheet remains strong, with estimated net cash of $353 million at the end of September, while Cenovus Energy’s net debt level sat at about $3 billion.
Cenovus Energy announced the $5.7-billion acquisition of Athabasca Oil Corp. last week, while Suncor Energy unveiled the sale of offshore Canadian assets for $1.2 billion and increased its share buybacks from $500 million to $750 million per month.
Before the pandemic, companies in the Canadian oil and gas sector often spent in excess of their cash flow. That trend largely ended in 2017, with annual capital expenditures remaining under combined cash flow levels ever since, according to data from ARC Energy Research Institute.
This year, the research institute forecasts after-tax industry cash flow will increase by 39 per cent from year-earlier levels to $83.6 billion, while producers’ sustaining and growth capital will be less than half that amount.
After the pandemic and oil price crash earlier this decade, many producers paid off debt and returned more capital to investors through dividends and share buybacks.
“Debt repayment has been a core priority for the large majority of Canadian (exploration and production companies) over the last 12 months,” said Michael Berger, a senior analyst at Enverus.
“The sector has very healthy balance sheets. Of course, it’s a cyclical industry and things can change. So I think that’s an angle that companies are absolutely considering, given where oil prices are at today.”
The combined net debt levels of the four large oilsands producers increased to $36.4 billion in 2020, but fell to $23.5 billion last year, according to energy consultancy Wood Mackenzie.
Those levels are estimated to drop to $14.8 billion by year-end 2026, although it could potentially go lower, giving producers more flexibility to pursue investments or other options, said Ayisha Zia, a senior analyst with Wood Mackenzie.
“With all of this deleveraging that’s happened, it’s unlocked big financial headroom for these companies to either invest in their existing business or invest in M&A opportunities,” Zia said.
And there are indications companies may be willing to increase their growth spending as Alberta and Ottawa look to build a new West Coast pipeline, with an energy memorandum of understanding signed earlier this year between the Oil Sands Alliance and both governments.

Meanwhile, benchmark U.S. oil prices, which started the year around US$57 a barrel, have increased since the U.S. war with Iran began in late February, eclipsing $100 a barrel as energy shipments out of the Strait of Hormuz have been disrupted.
Prices for WTI crude jumped more than $2 on Thursday to close at $97.97 a barrel.
On Thursday, TD Cowen boosted its oil price forecast for West Texas Intermediate (WTI) crude this year, expecting it to average $85 a barrel — and $78 a barrel next year, increasing from $72 previously.
In a report, TD Cowen noted producers are benefiting from high oil prices, and downstream refining fundamentals are “exceptionally strong, with low product inventories and global refinery disruptions supporting elevated crack spreads,” although the price differential between WTI oil and Western Canadian Select heavy crude has widened recently.
“The balance sheet strength is phenomenal. I mean, the debate really is: Are these companies going to be incurring (debt) to facilitate growth — and I think they generally won’t need to,” said TD Cowen analyst Menno Hulshof.
“I don’t see a scenario where these companies are going to be taking balance sheet leverage much higher than it is right now.”
Chris Varcoe is a Calgary Herald columnist.
FP West: Energy Insider brings you behind the closed doors of the oilpatch, with exclusive insights from insiders every Wednesday morning. Sign up now.
Join the Conversation
This website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more about cookies here. By continuing to use our site, you agree to our Terms of Use and Privacy Policy.