Executive Summary
- Bitcoin swept to about $80K on October 15, just under the ETF and treasury cost bases, and the bids there refilled within days.
- Above price, the 6 to 12 month cost basis, a block of asks and the largest liquidation clusters all sit between about $85K and $87.5K.
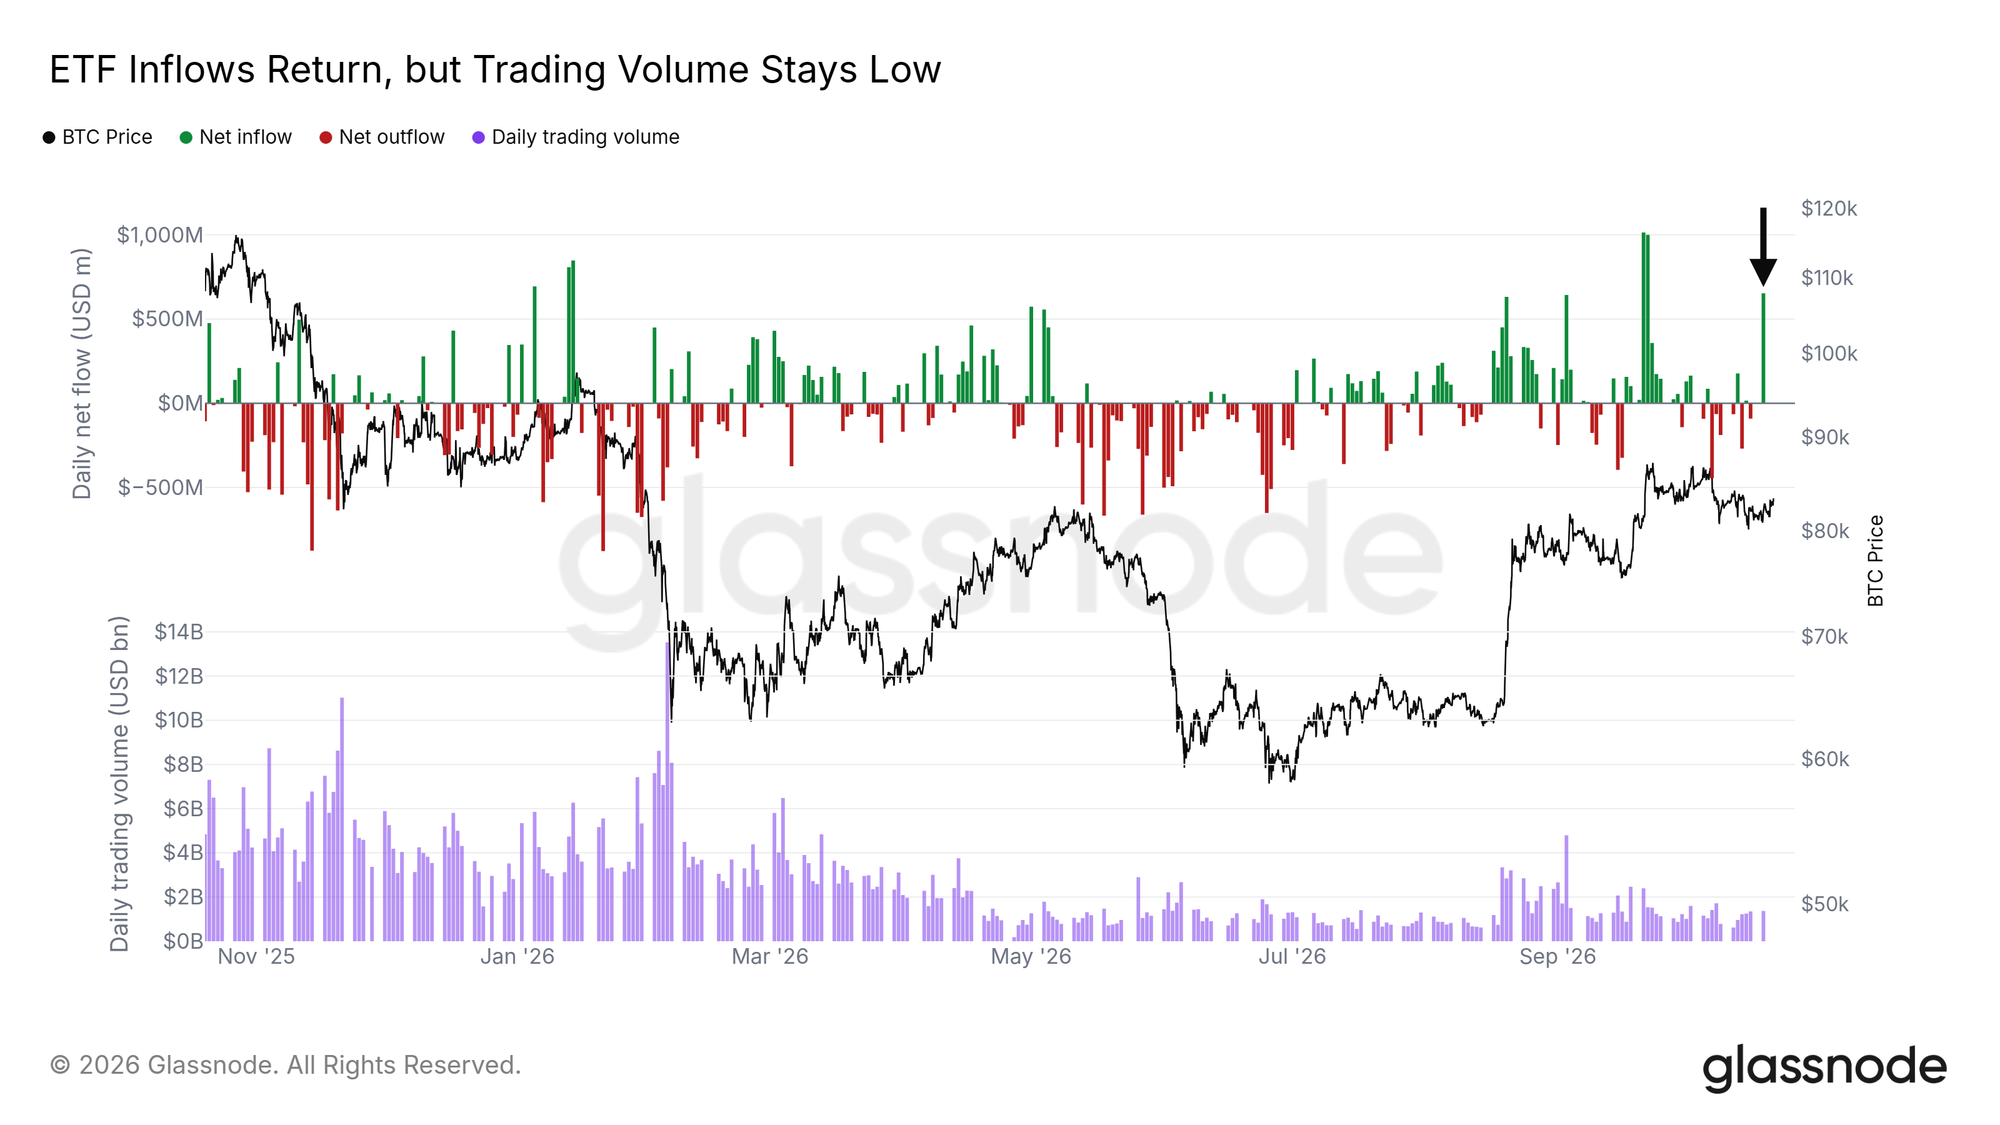
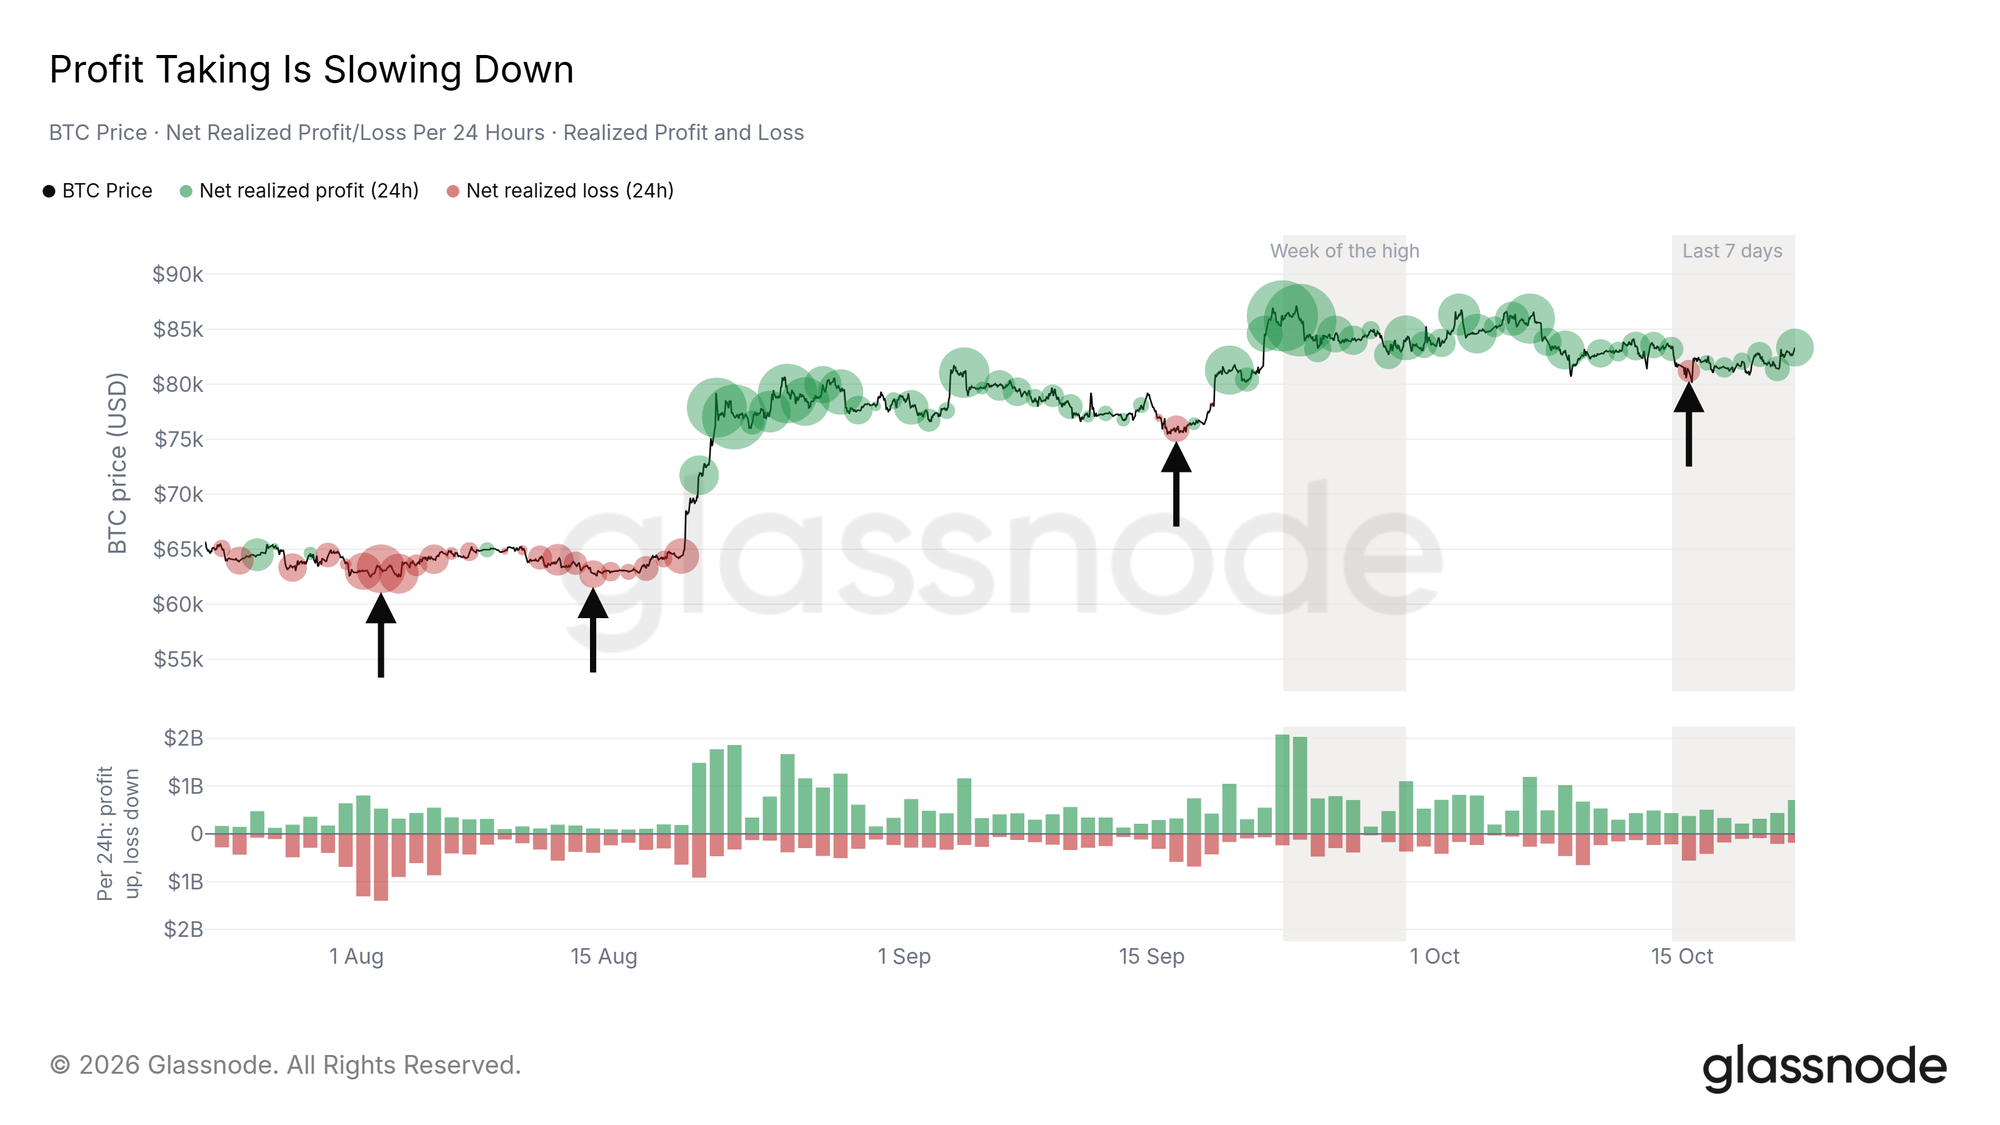
- The ETFs took in $653M on October 19 on thin volume, while profit taking has slowed to about half its pace at the September high.
- Next come the Fed decision on October 28 and MSCI's list of index removals on November 11, which could include Strategy.
- Altcoin froth and funding have cooled from their highs, though open positions are only slightly smaller.
Ready to get ahead of markets and sharpen your foresight? Try Glassnode. Sign up or talk to sales.
Swept at the Cost Basis
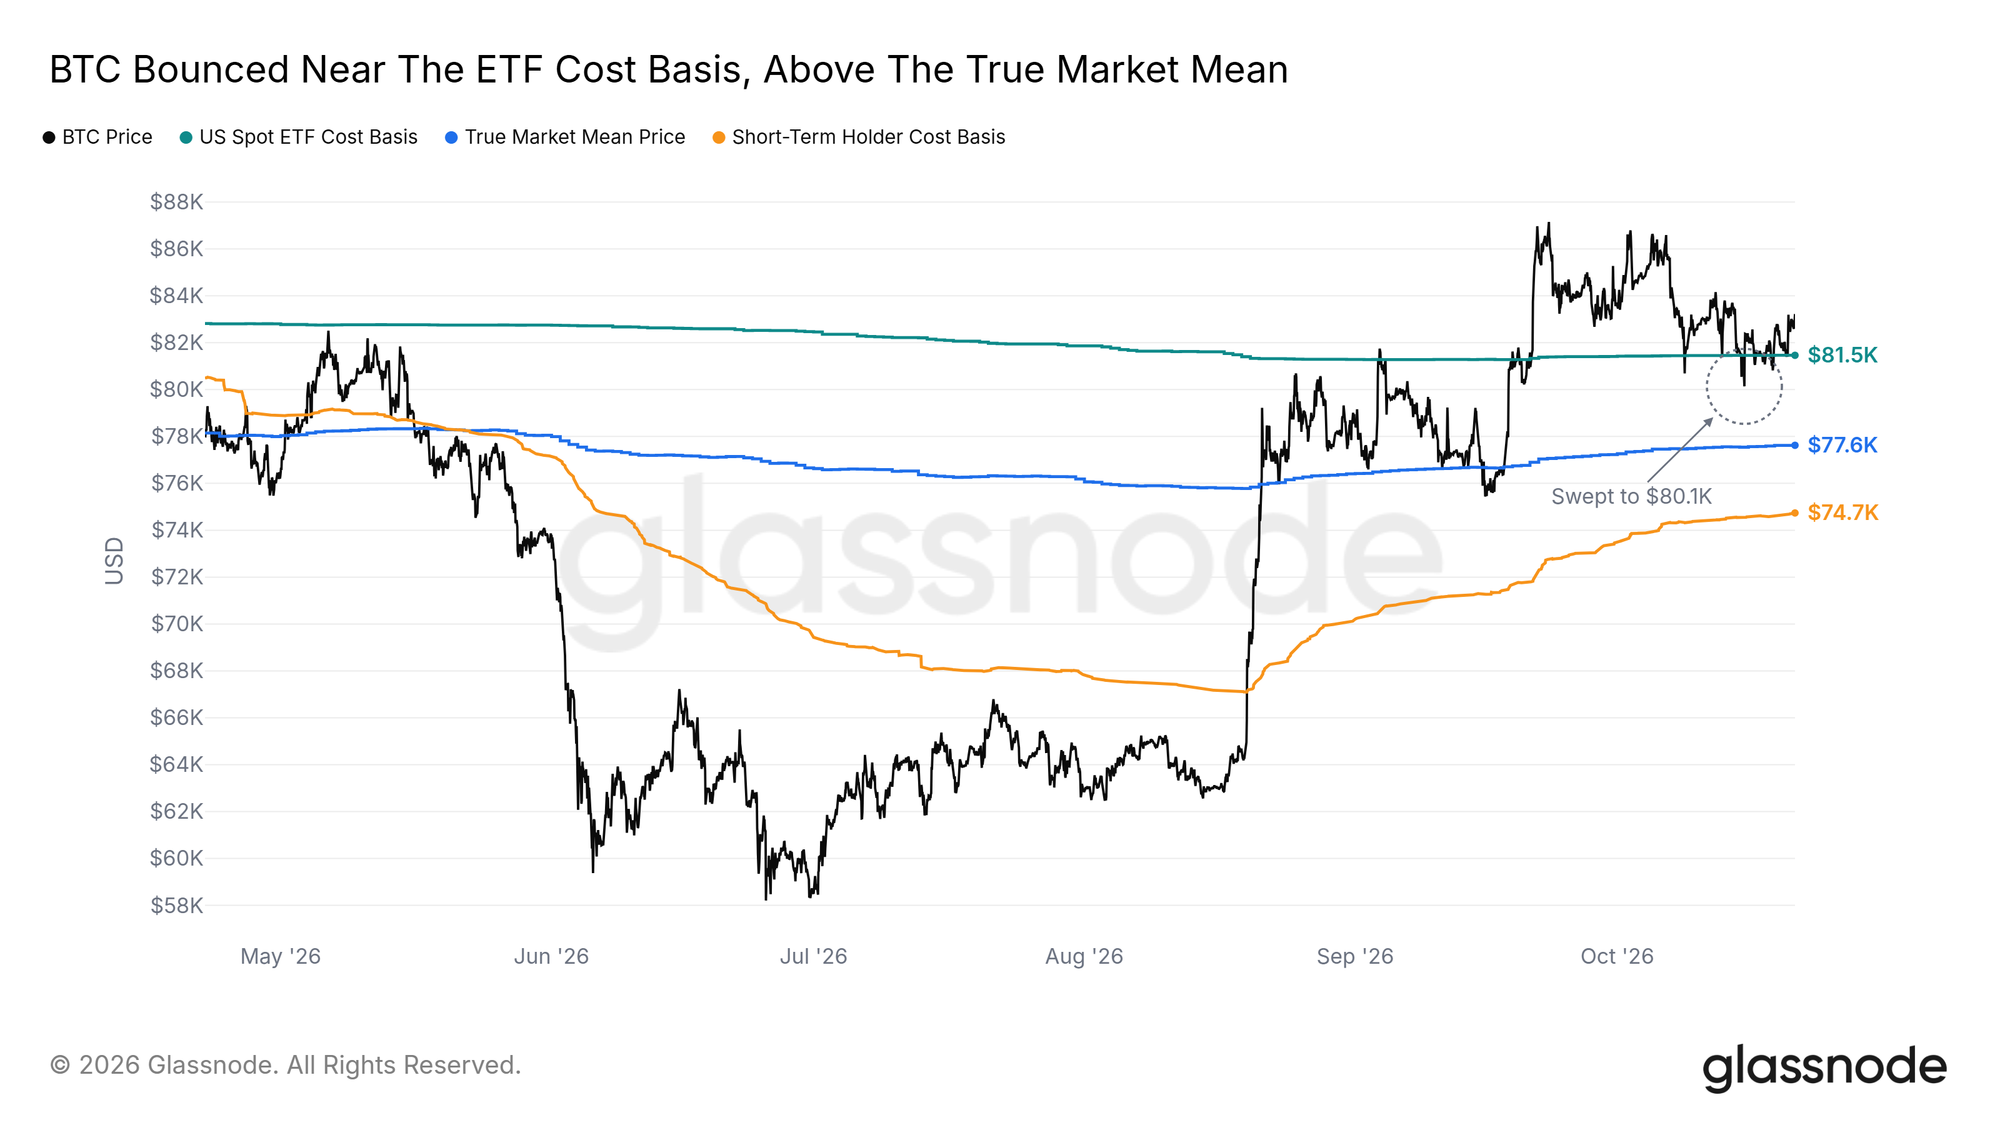
Last week, this report named the US Spot ETF Cost Basis, the average price the US spot ETFs paid for the coins they hold, as the nearest on-chain support. Bitcoin has traded around that line since October 8 and dipped under it several times. The deepest dip came on October 15, when the hourly close fell to $80.1K, and the next hourly close was back above the line.
The same line capped Bitcoin in the spring. Price stalled just under it in early May and did not close an hour above it until September 3. In October, it has acted as support. The True Market Mean, the average cost basis of active investors, sits lower, near $77.6K, and the sweep stopped well short of it.
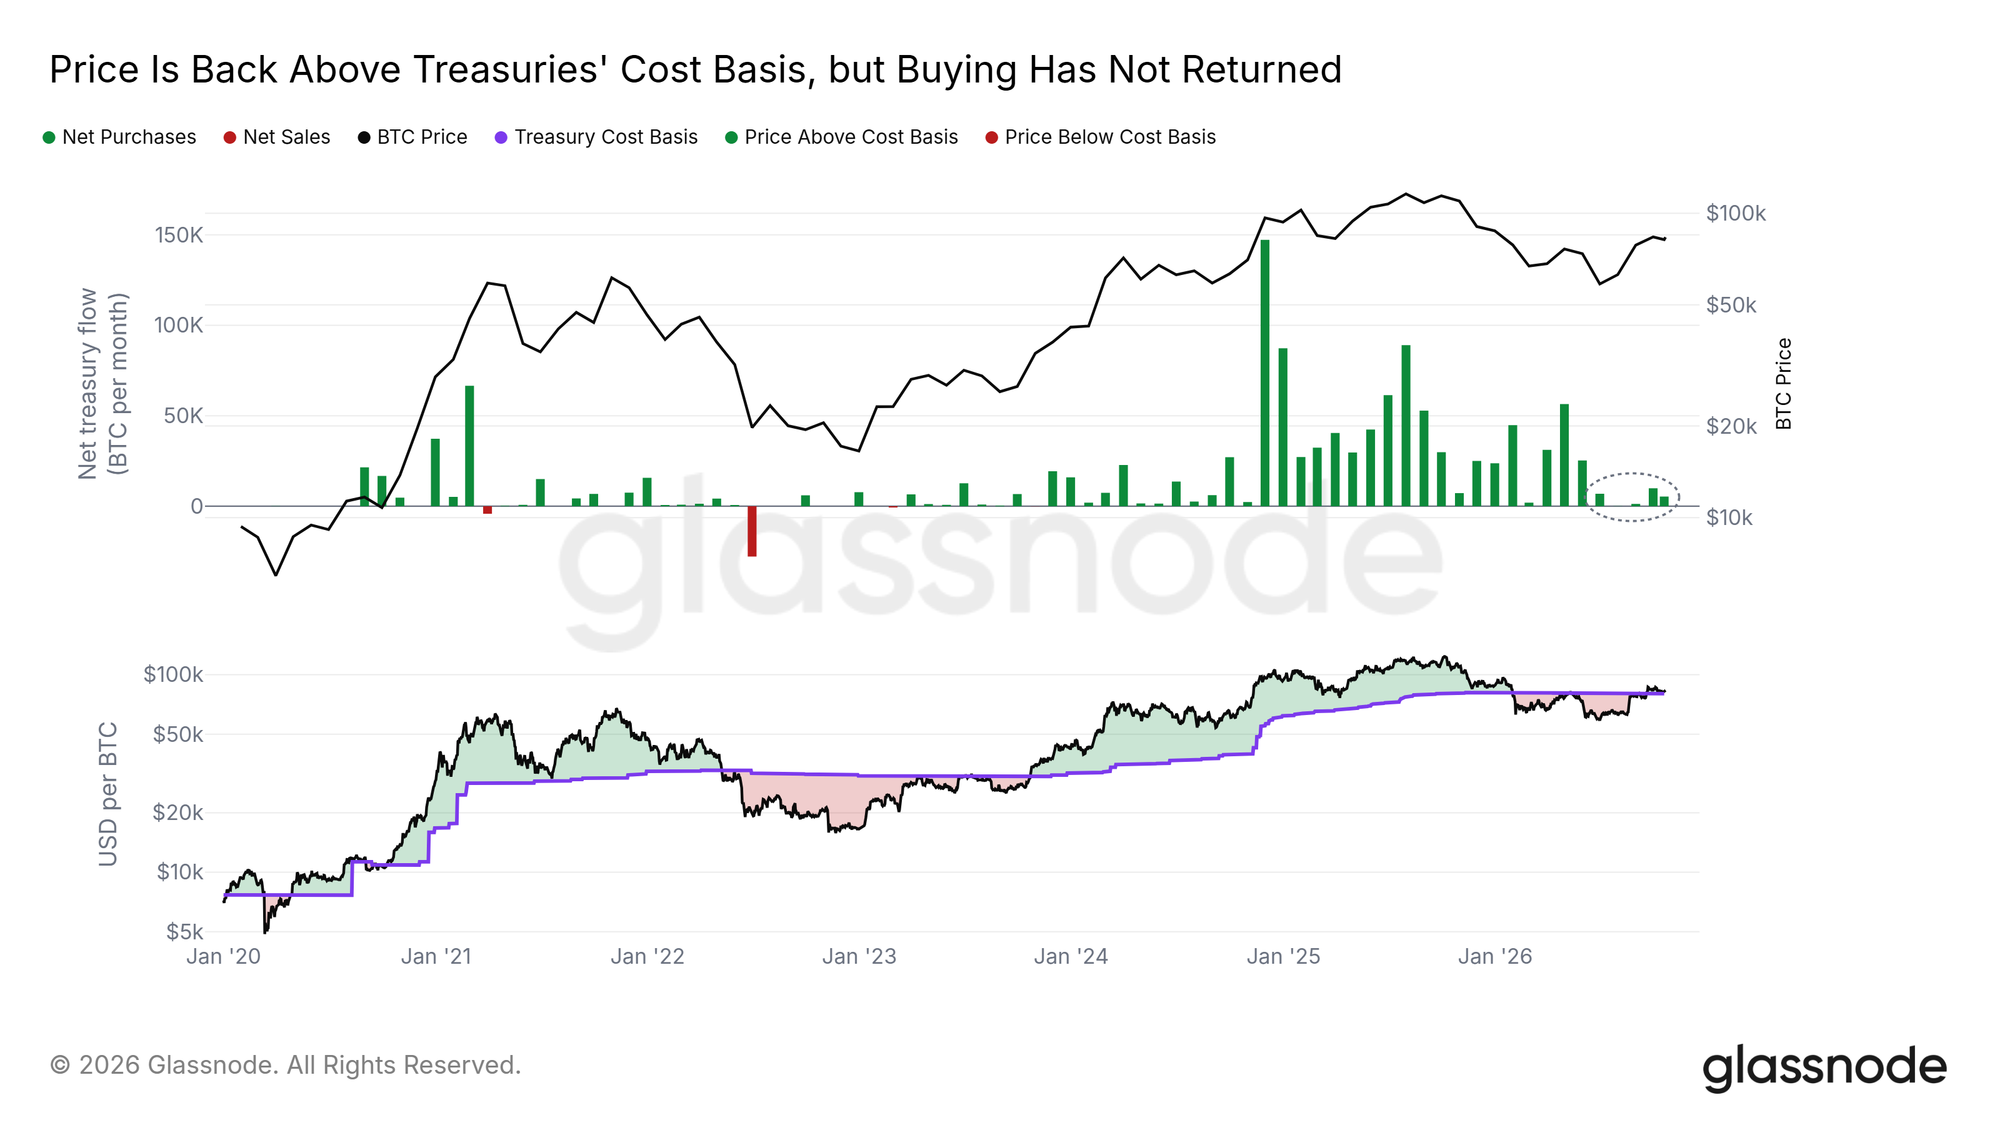
Treasuries Paid About $80K
By our estimate, derived from their holdings and unrealized profit, the treasury companies we track hold their Bitcoin at an average cost of about $80.2K, just under the ETF line. Price spent most of this year under it, falling more than a quarter below it at the end of June, and has closed above it every day since September 18.
Their buying has not returned with price. Every month since June has added less than a tenth of the peak month, November 2024. With both cost bases between $80K and $81.5K, the October 15 sweep tested two of the largest holder groups at once. A daily close below $80K would put both at a loss on average.
Bids Refilled at $80K
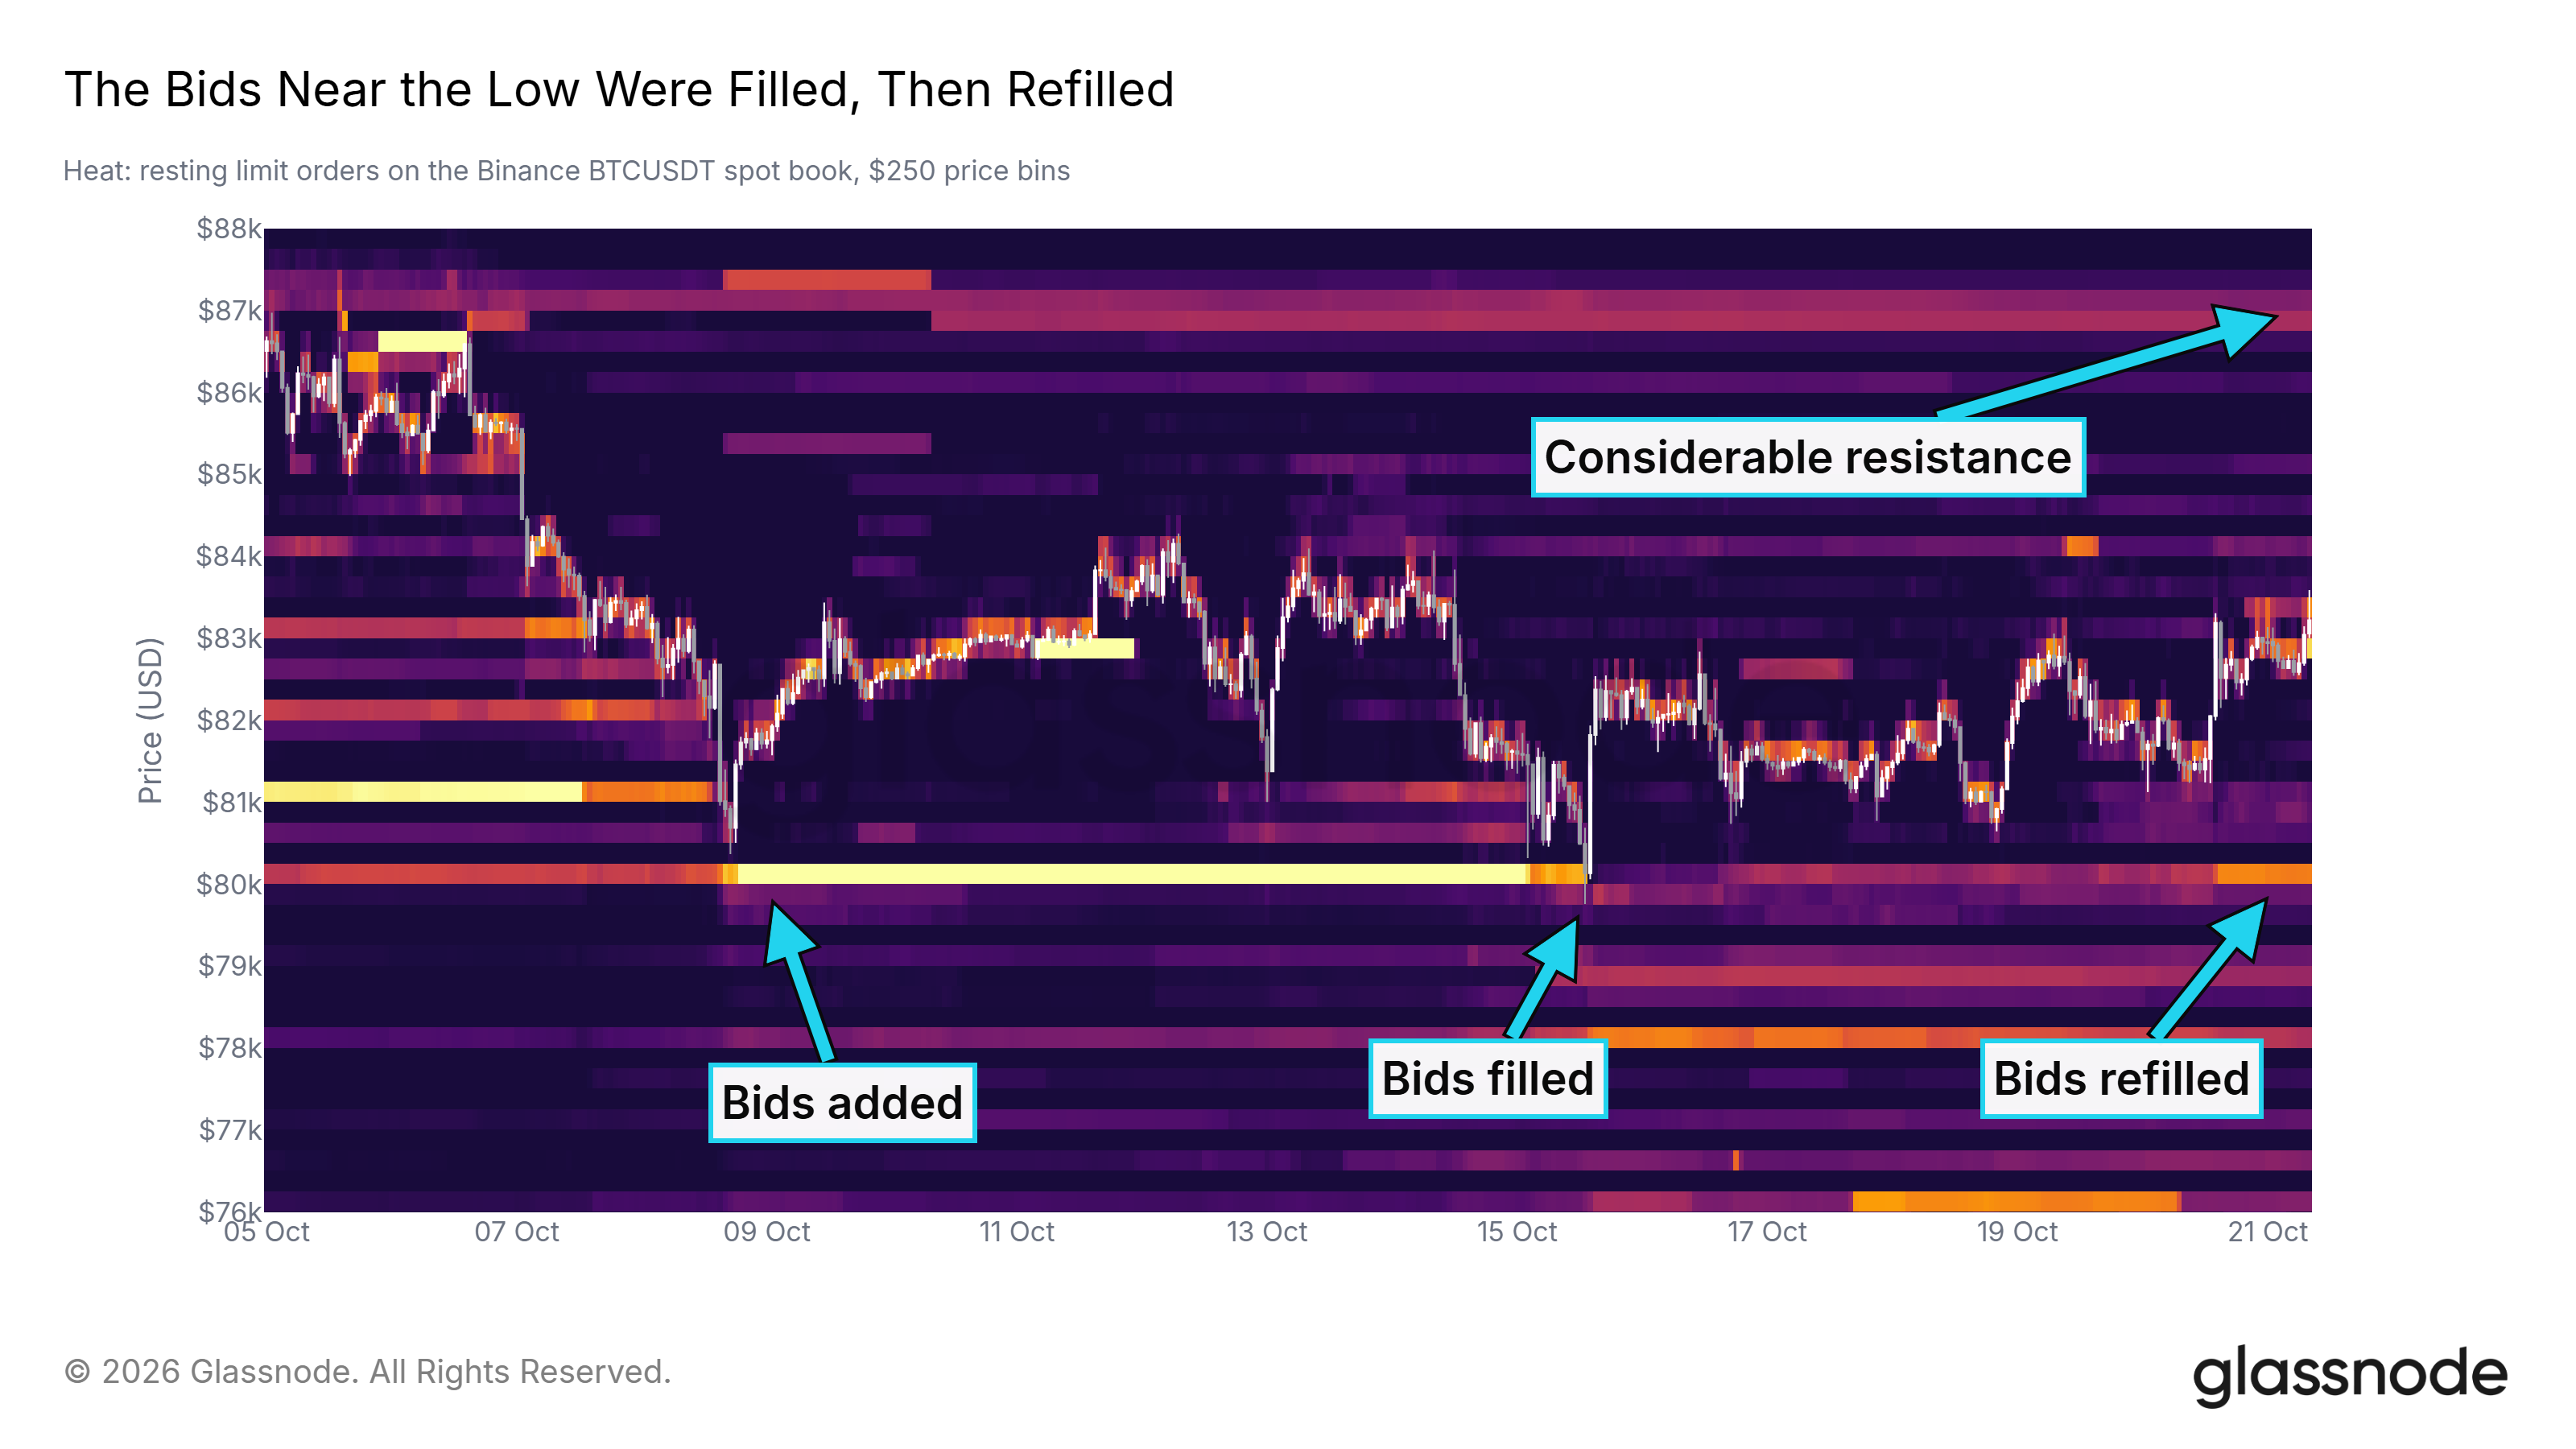
The largest block of bids on the Binance spot book, flagged here last week, sat at $80K, just under the ETF line. The October 15 sweep traded through it and took out most of the block. The bids came back by October 20. They are smaller than at their peak, but buyers still want Bitcoin at that price.
Above price, the main block of asks sits between $86.5K and $87.5K, the first heavy resistance on the book.
Clusters Shift Above Price
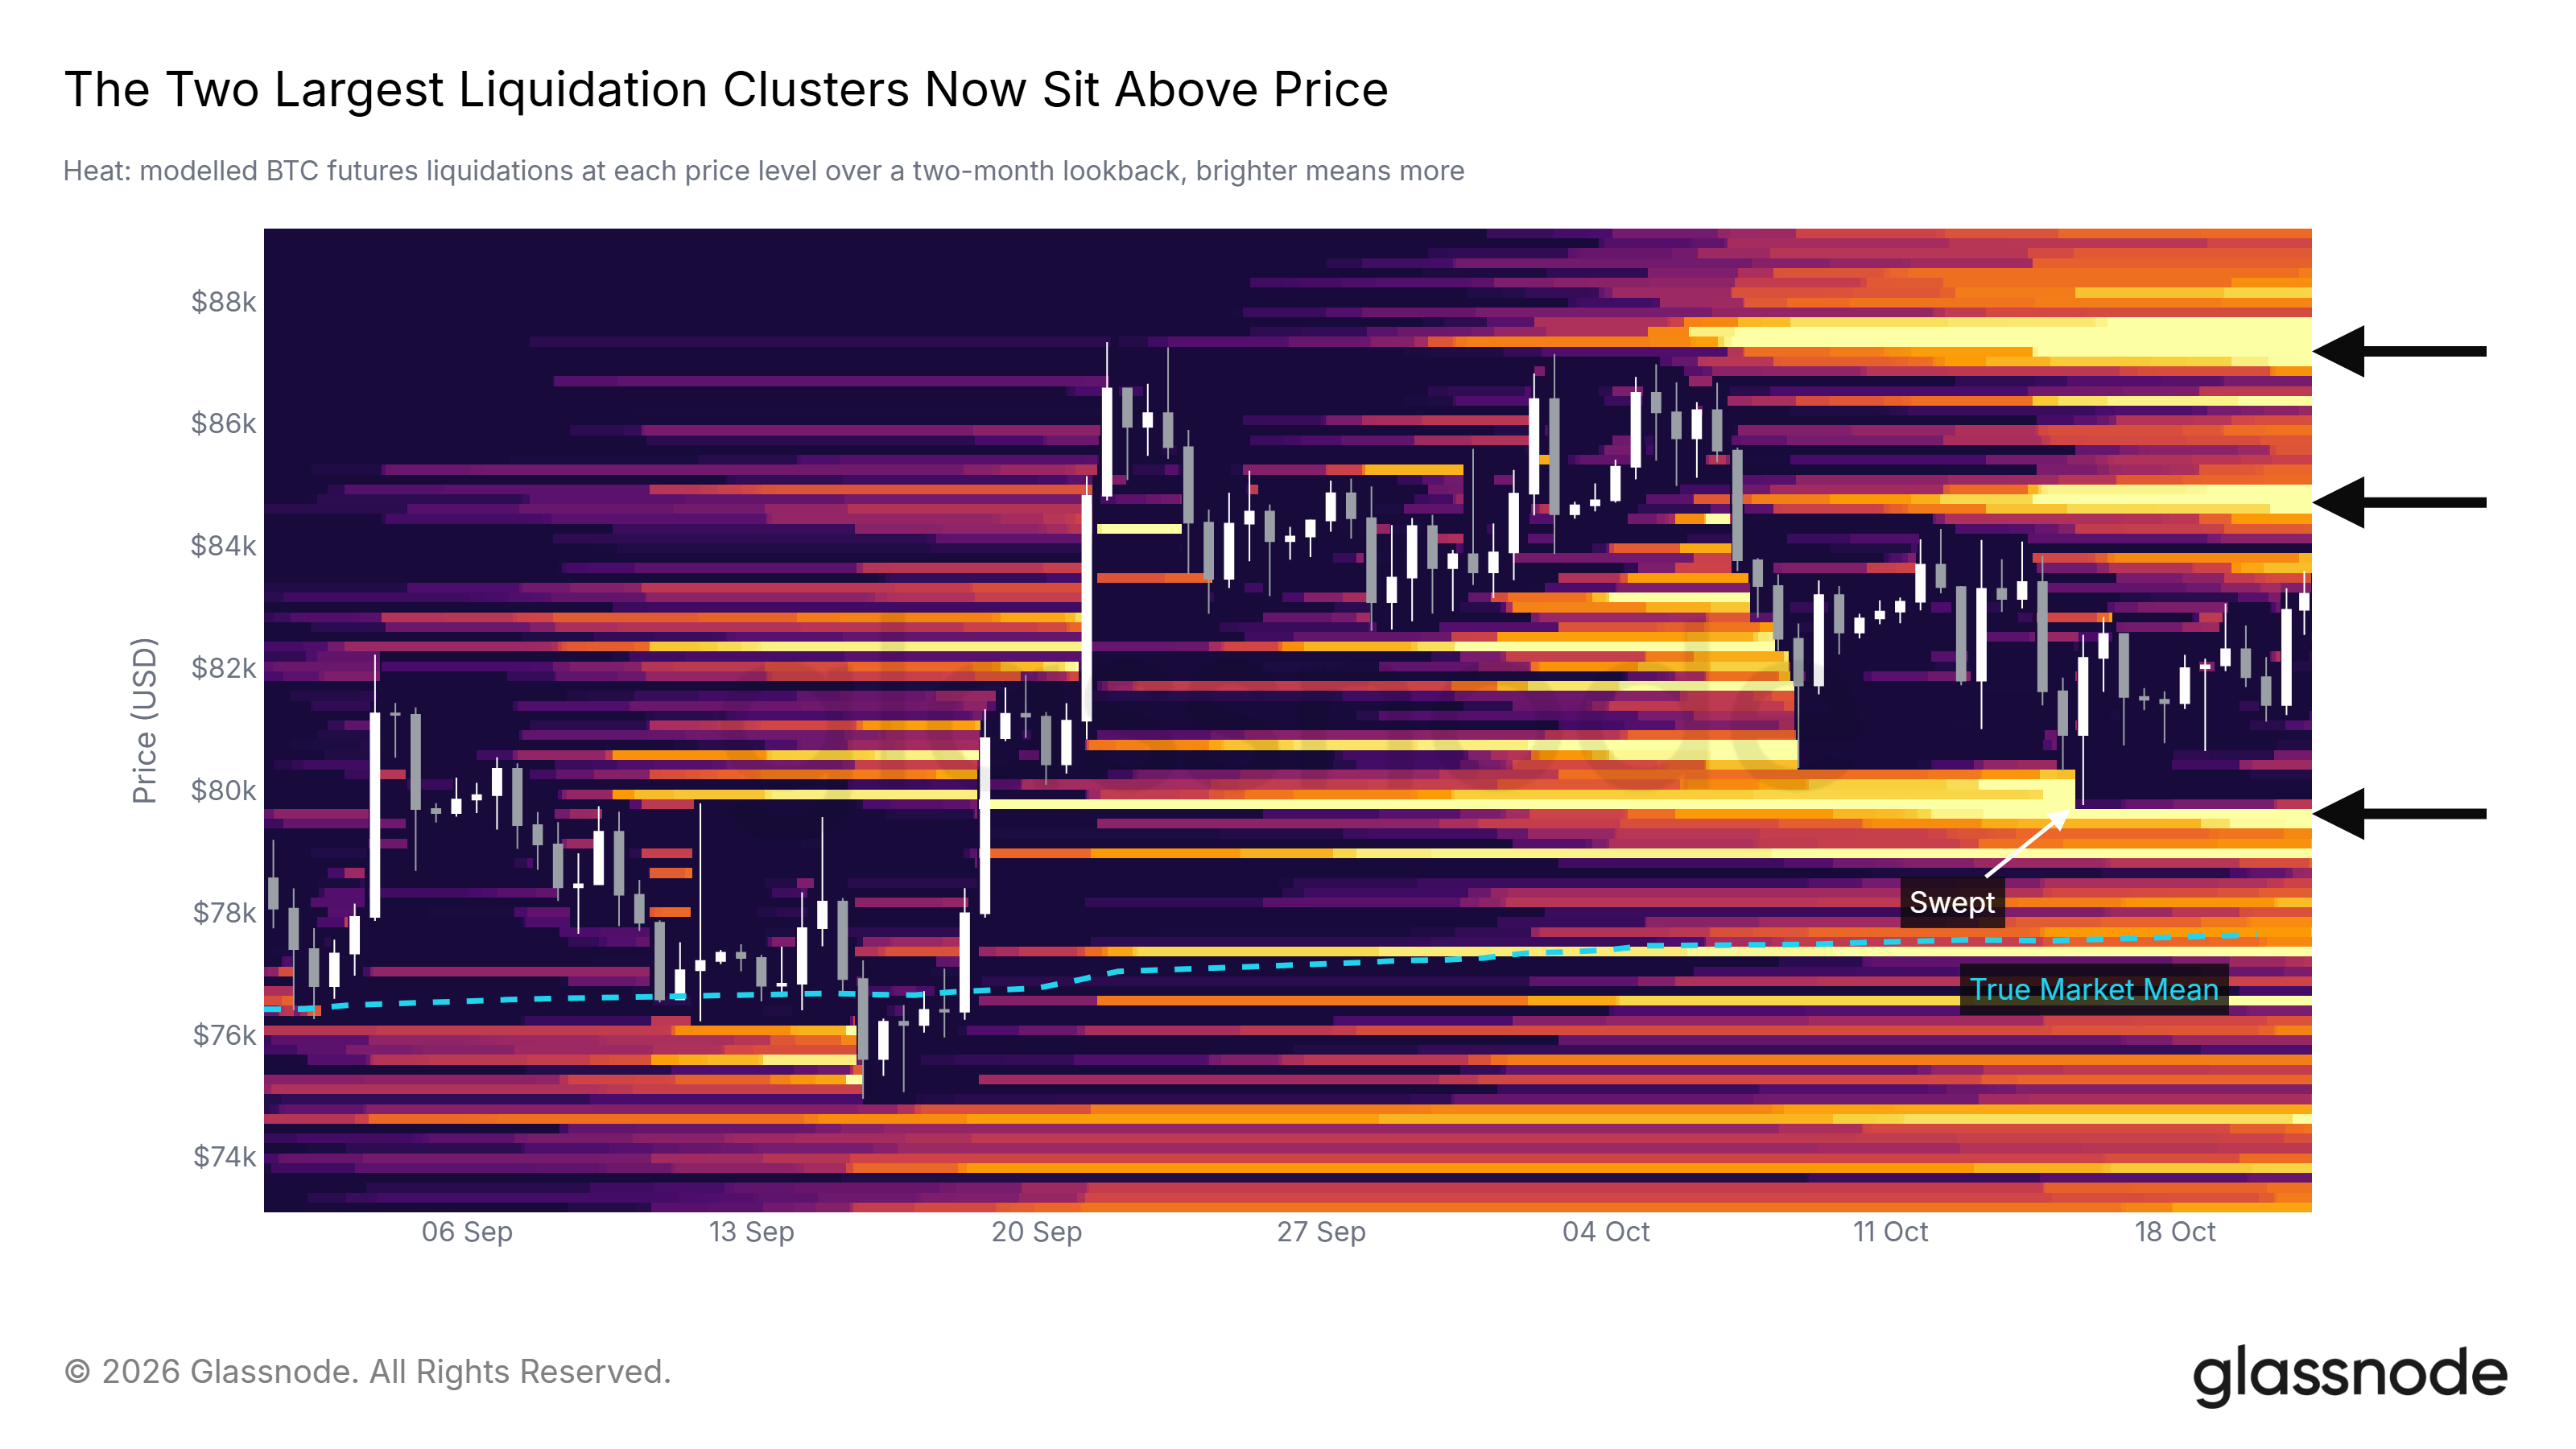
The liquidation heatmap models the prices at which leveraged futures positions would be forced to close. The October 15 sweep cleared the bright band near $80K, and the two largest clusters now sit above price, near $85K and $87K. Below price, a bright line remains near $79.6K, just under the October 15 low.
A move toward $87K could gain speed as short positions are forced shut, but it would meet the asks on the order book at the same price.
Still Under the Top Buyers
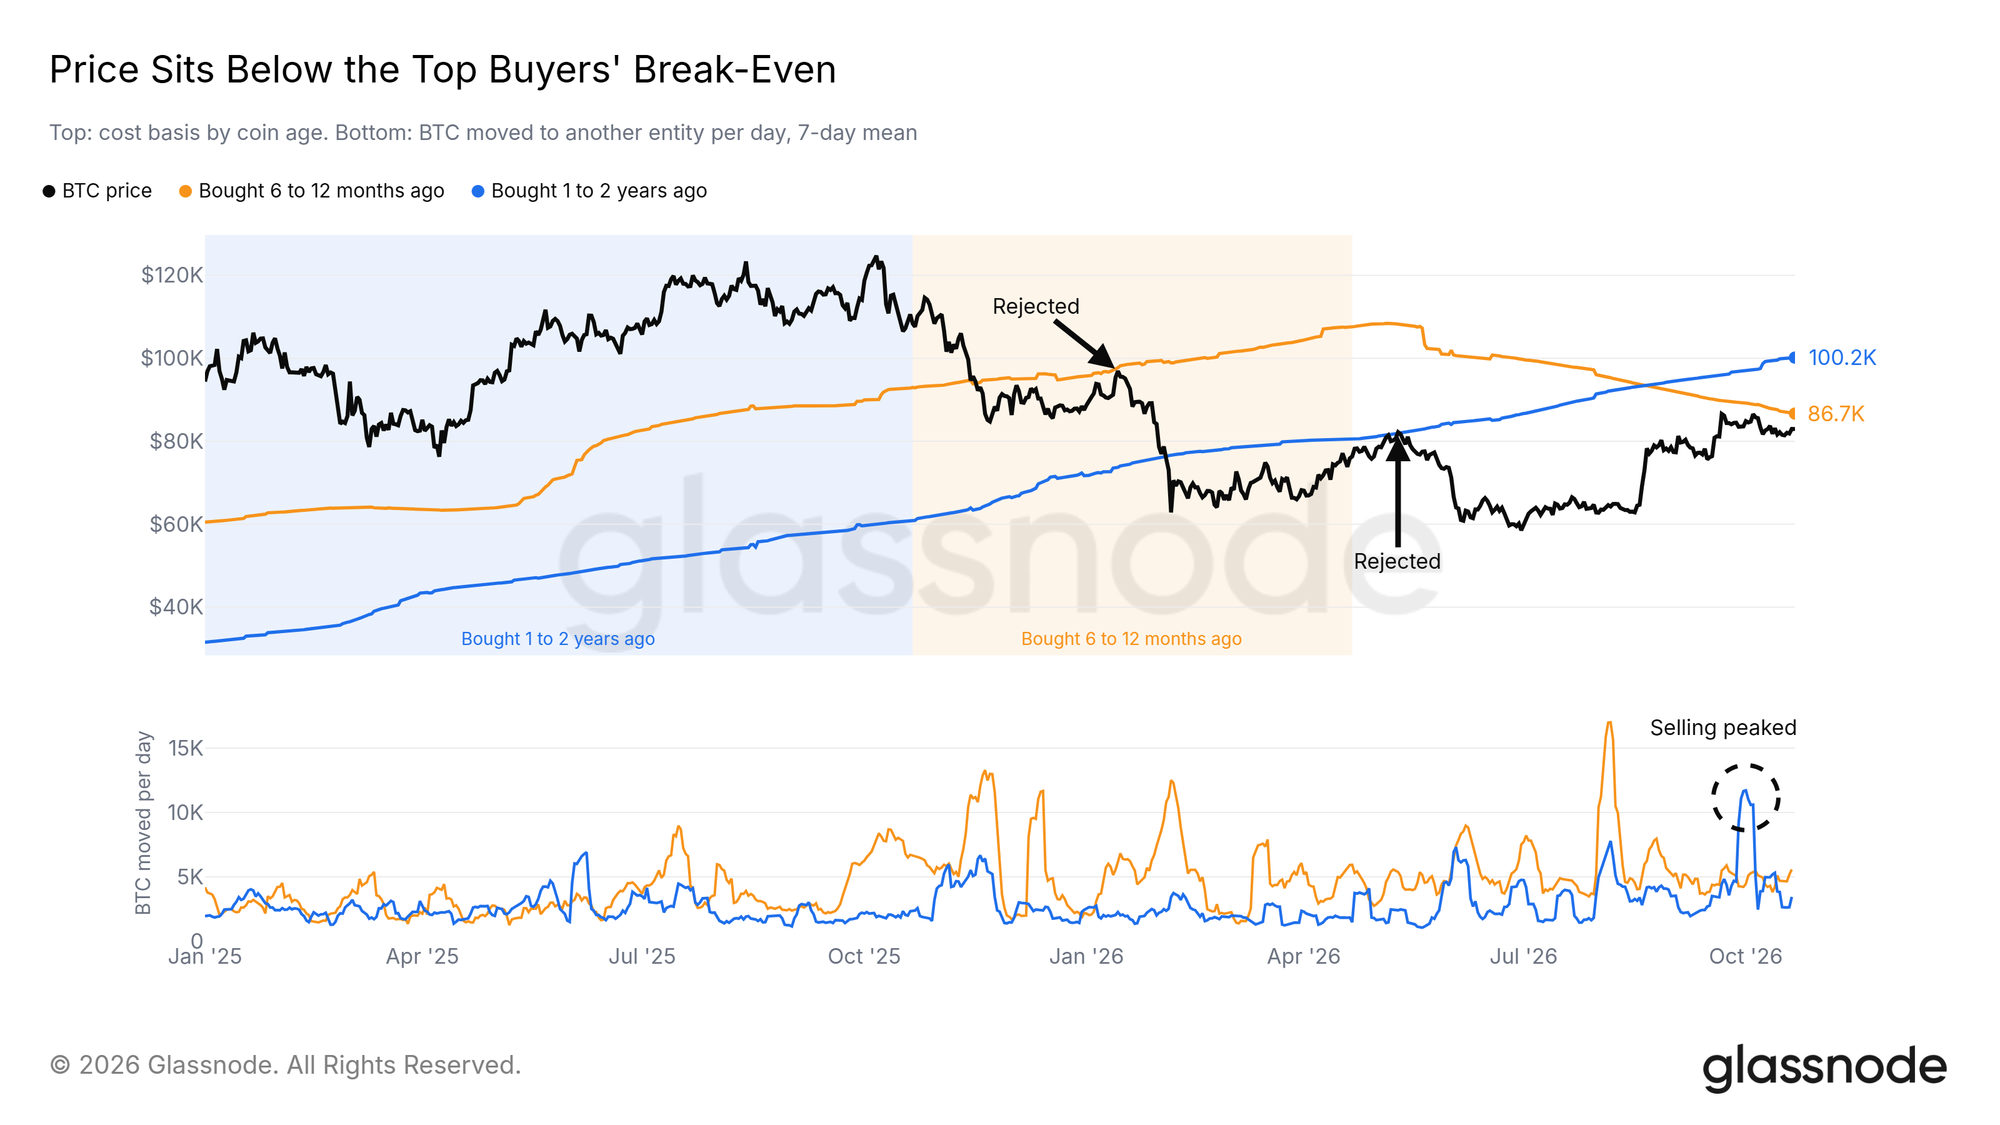
Last week, this report described Bitcoin as boxed in under the cost basis of the past two years' buyers. That ceiling still holds. Coins bought 6 to 12 months ago now have a cost basis near $86.7K, down from the $88K we cited last week, and coins bought 1 to 2 years ago sit near $100K. The first of these lines now sits inside the zone of asks and liquidation clusters near $87K.
The selling from these holders has eased. Selling by the 1 to 2 year group peaked at the start of October, after the September high, and the group now moves less than a third as many coins a day.
A daily close above $86.7K would put the 6 to 12 month buyers back in profit on average and clear the nearest band of supply overhead.
Inflows Return on Thin Volume
After a week of net outflows, the US spot ETFs took in about $653M on Monday, October 19, their largest day since September 22. That turned the weekly flow positive again.
Trading volume has not followed. The funds traded less that day than on a typical day of the past year, and their 30-day average volume is less than a quarter of its level a year ago.
Inflows that repeat on rising volume would show demand broadening beyond a single day.
Profit Taking Slows
On-chain, holders are taking less profit. Realized Profit, the gains locked in when coins move above the price at which they last moved, has slowed over the past week to about half its pace in the week of the September high. Realized losses have held steady, and the largest of the past week came in the 24 hours to the morning of October 15, as price slid toward $80K.
A renewed rise in profit taking near $87K would be the first sign that sellers are back at the top of the range.
MSCI Sets a Date
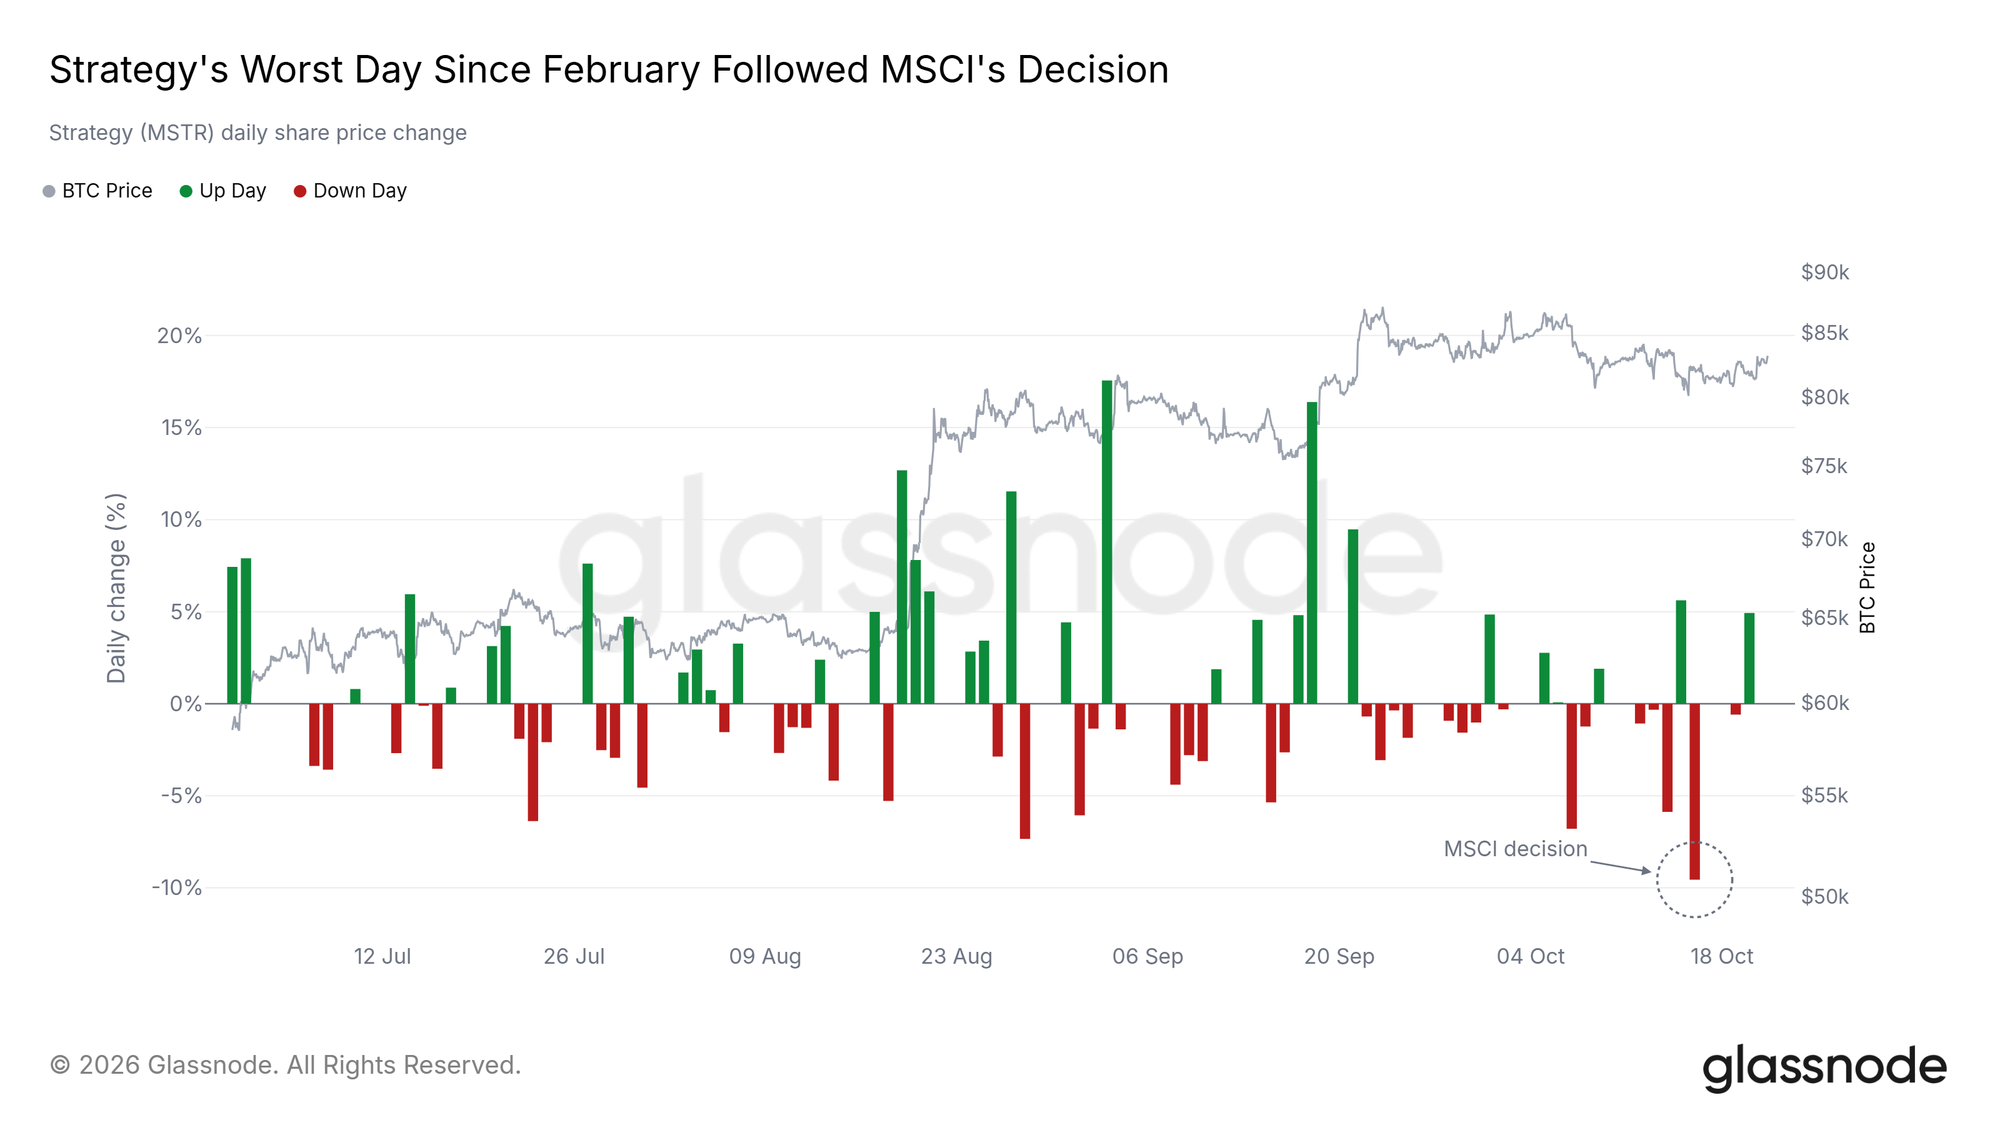
On October 15, after the US close, MSCI adopted new rules for what it calls non-operating companies. A test run on May data, published with the consultation in August, flagged Strategy and Metaplanet among them. A company already in MSCI's indexes is removed only if it fails the test in both of its two latest annual filing periods. MSCI will publish the final list on November 11, and the changes take effect at the close on November 30.
Strategy's shares fell nearly 10% on October 16, the first session after the decision and their worst day since February. Bitcoin barely moved that day.
A removal would force funds that track MSCI's indexes to sell the company's shares, at a time when treasury companies are already buying far less Bitcoin. Should Strategy appear on the November 11 list, its shares would come under pressure first, and the next question would be whether it keeps buying Bitcoin.
Oil and Yields Rise Into the Fed
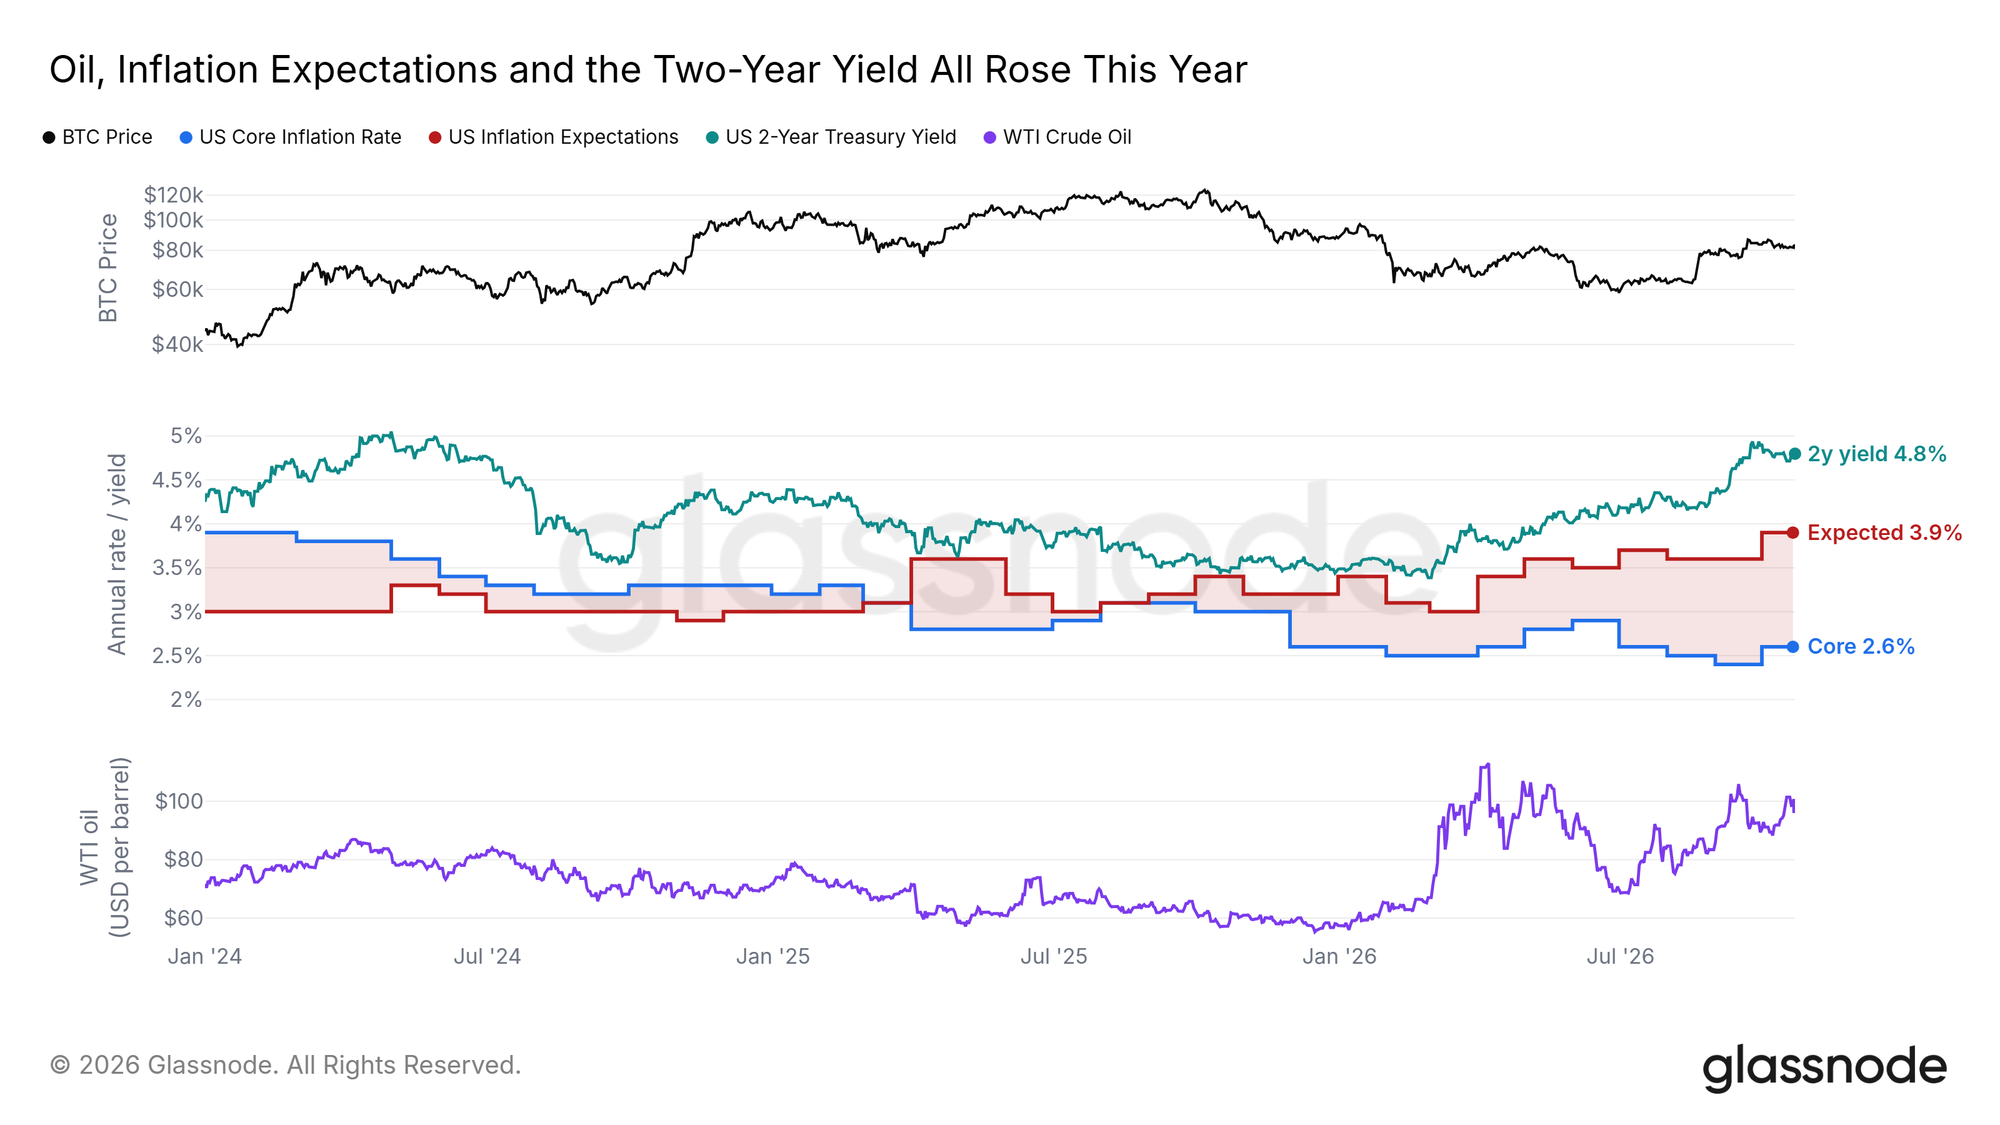
The Fed decides on rates again on October 28. Since the start of the year, WTI crude is up about 73%, and household inflation expectations have risen by half a percentage point. Core inflation sits where it started the year, but September's CPI, covered here last week, came in above forecasts on both the annual headline and core rates.
Yields have climbed too. The two-year Treasury yield, which tracks where traders expect policy rates to go, has risen by more than a full percentage point this year, to 4.8%. It now sits well above the 4% top of the Fed's target range, even after the hike on September 16.
Bitcoin is up about 10% since that hike. Should oil keep pushing inflation expectations higher, a second hike would be harder to rule out.
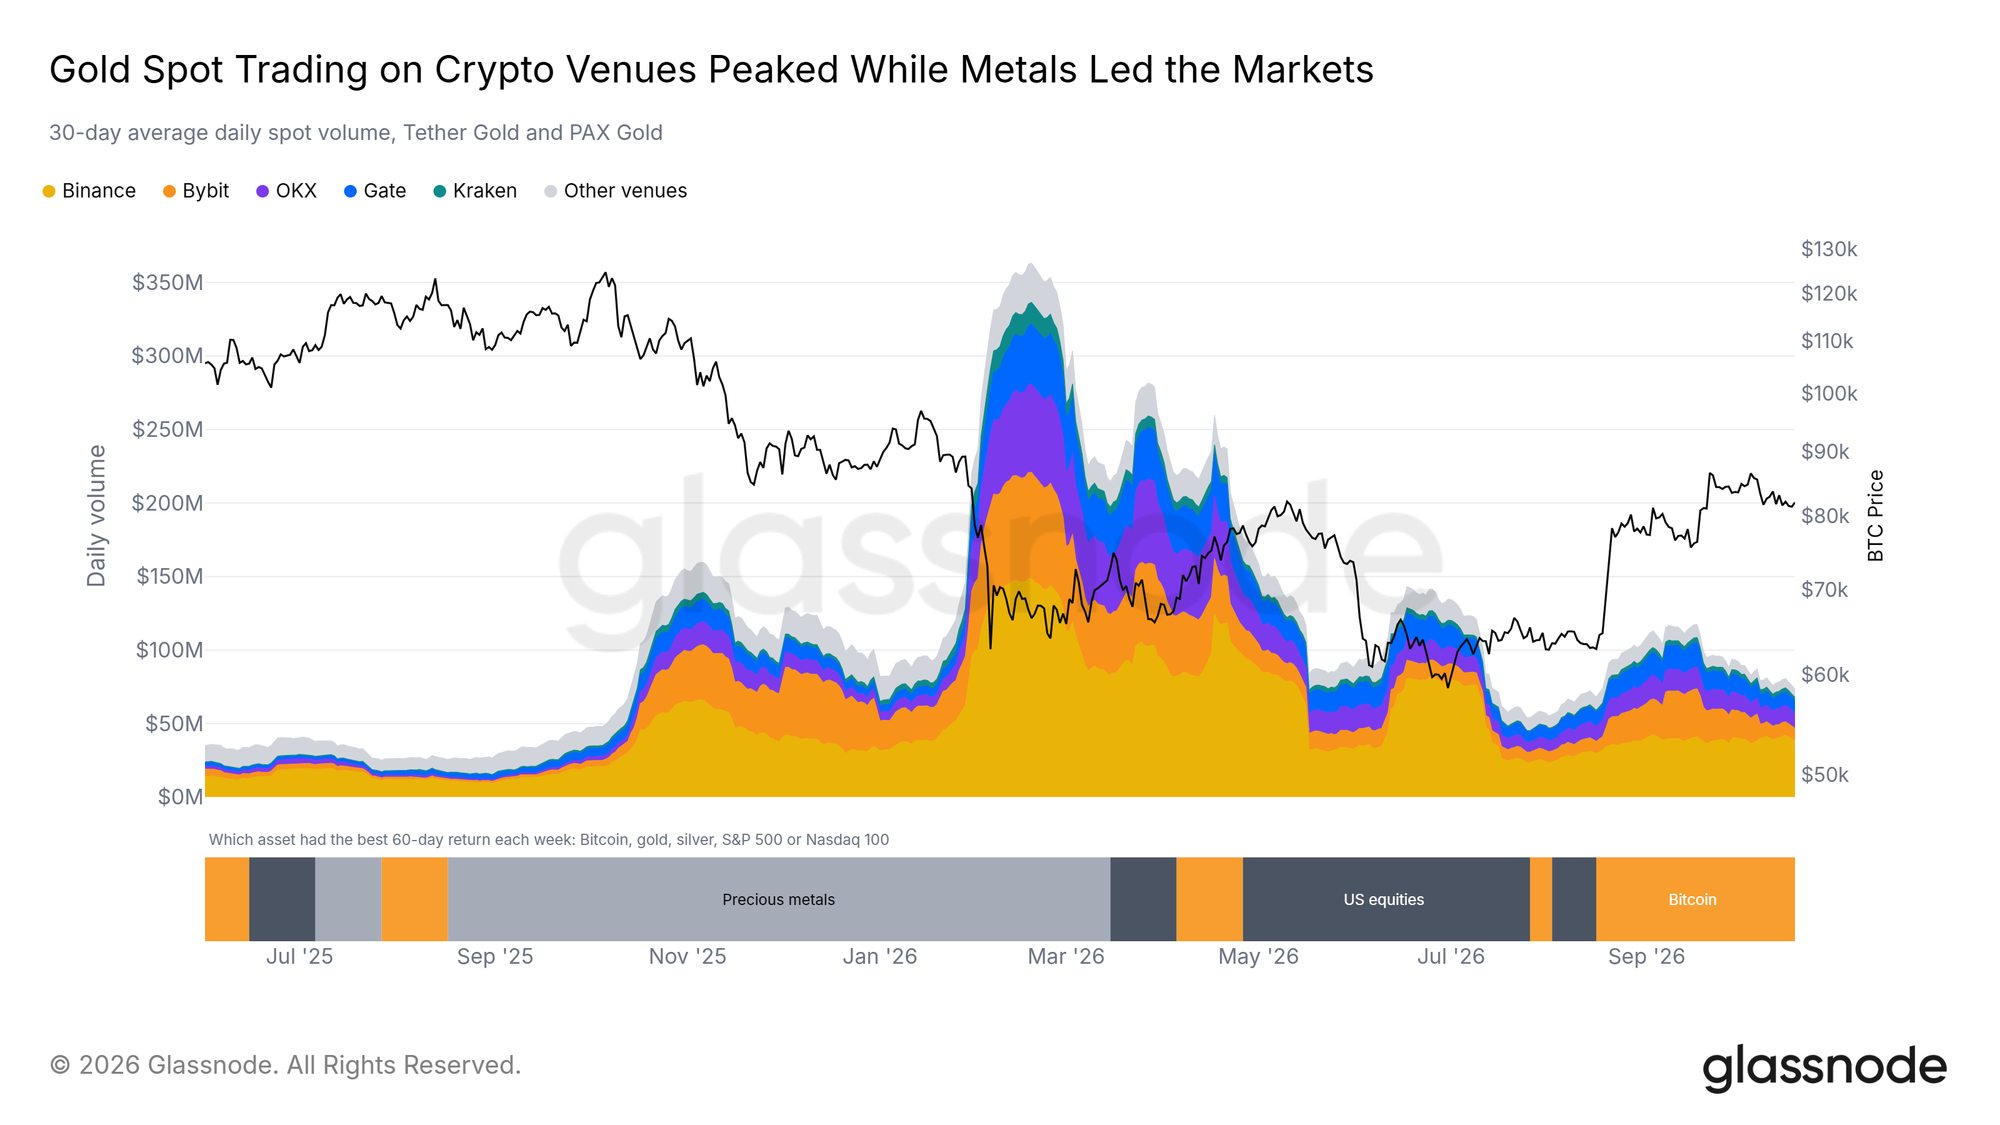
Market leadership has passed from metals to equities to Bitcoin this year. Measured by two-month returns across Bitcoin, gold, silver, the S&P 500 and the Nasdaq 100, gold and silver led through the first quarter and US equities through the spring and into July. Bitcoin has led for the past 10 weeks.
Crypto exchanges traded the metals rally as it happened. Spot Volume in tokenized gold (Tether Gold and PAX Gold, tokens backed by physical gold) peaked in mid-February while precious metals led, then fell to 15% of that level by late July. It more than doubled into mid-September, with Bitcoin in the lead, and has eased since to 20% of the February peak.
Binance still handles the largest share of this trading. OKX and Gate have gained the most share this year, and Gate's share has grown from 0.6% in 2024 to 12% so far in 2026.
Should precious metals retake the lead, the February pattern suggests gold trading on these exchanges would rise with them.
Positions Outlast the Trade
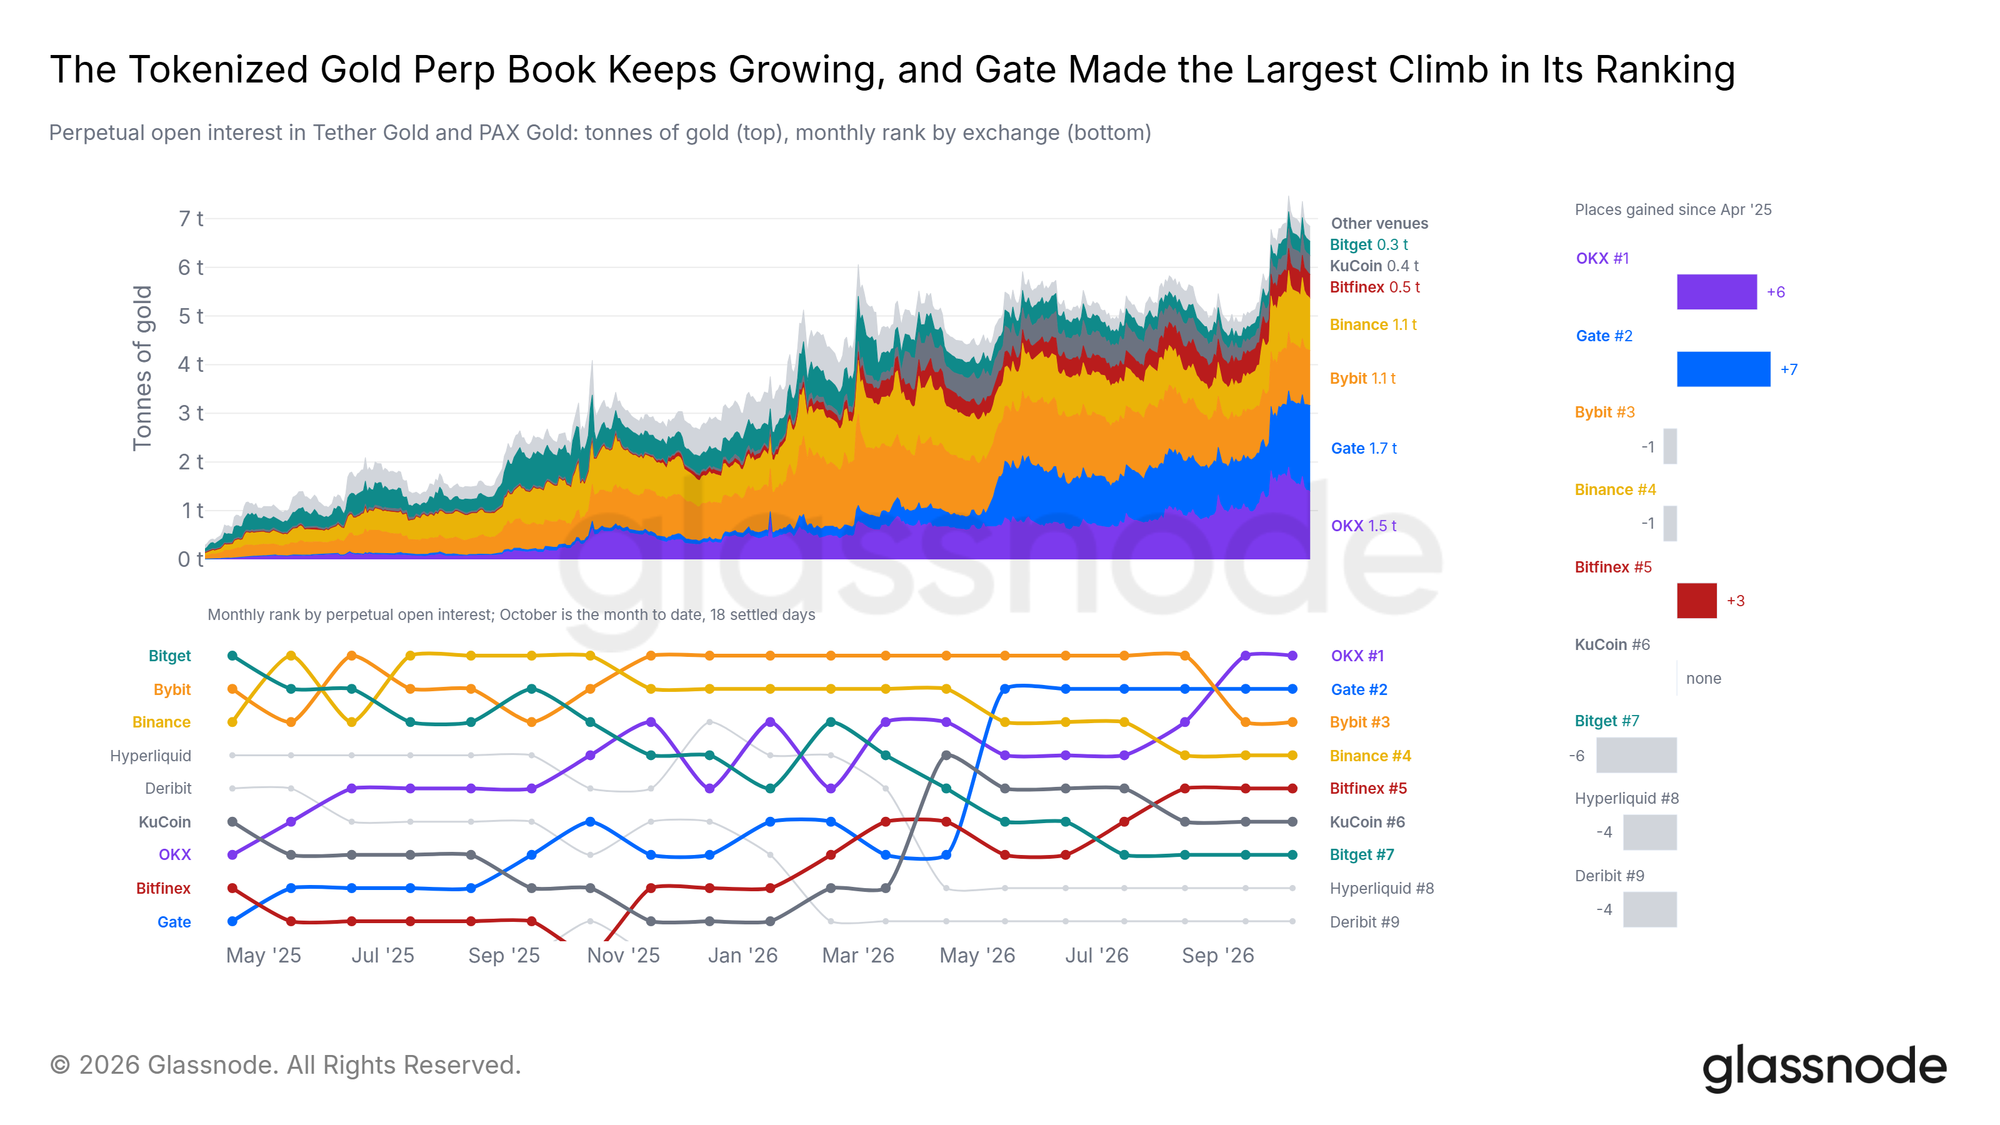
Traders kept their gold positions after trading peaked. Perpetual Futures Open Interest in tokenized gold, the size of all open futures contracts with no expiry date, now equals 7.0 tonnes of gold, 62% more than at the February spot peak. The book grew from 5.0 tonnes in mid-September while spot trading eased, which suggests traders are holding their gold exposure for longer.
This year Gate added more to that book than any other exchange: 42% of the net increase since January 1. Since April 2025 it has also made the largest climb in the ranking by open interest, from 9th to 2nd place; OKX, first on the October average so far, climbed 6 places. Averaged over the past week, Gate's book is now the largest of the exchanges Glassnode tracks: 1.7 tonnes, against 1.5 tonnes at OKX.
A sustained hold above 6 tonnes, with metals no longer leading, would show traders keeping gold exposure on crypto exchanges without a metals rally behind it.
Most Exchanges Hold Less
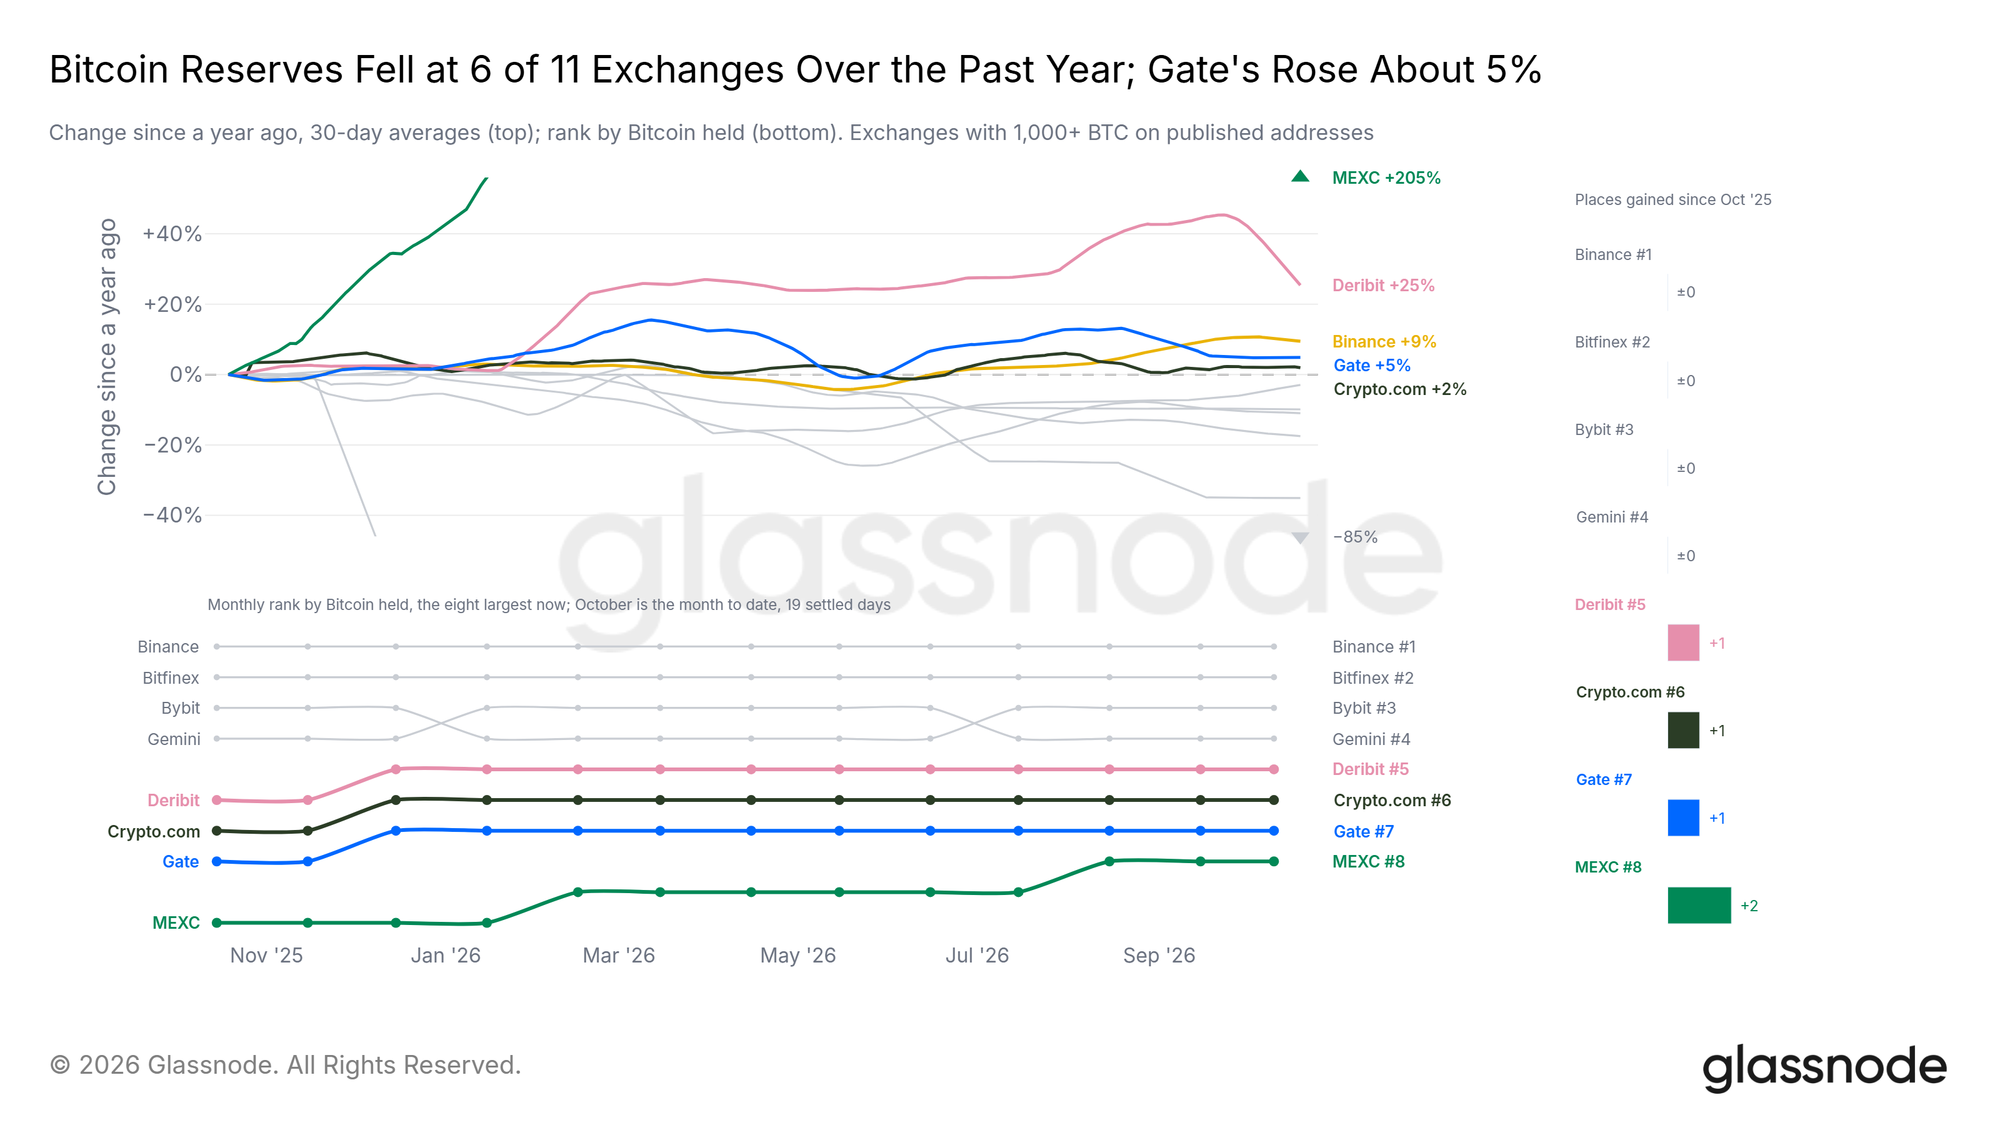
Bitcoin reserves have thinned at most exchanges over the past year. Our Proof of Reserves metric tracks the addresses exchanges publish to show what they hold. Among 11 exchanges with at least 1,000 BTC on those addresses, six hold less than a year ago. Of the five that grew, Deribit was among the fastest. Gate's reserves rose 4.9%, while the median of the other ten fell 6.4%.
The falls spread into the spring. At the end of November, four of these exchanges held less Bitcoin than in October last year; by the end of May, eight did, and six do now. Growth at the largest exchange kept the total from falling, but the other ten together hold about 10% less than a year ago.
Gate released its latest Proof of Reserves this week, a report that compares what the exchange holds with what its users have deposited. As of October 18, it reported about $1.4 billion more in reserves than its users hold. Bitcoin, Ether, stablecoins and every other major asset named in the report sit above 100%.
Should the falls keep spreading, the Bitcoin left on exchanges would gather at the few still adding to their reserves.
Altcoin Leverage Cools
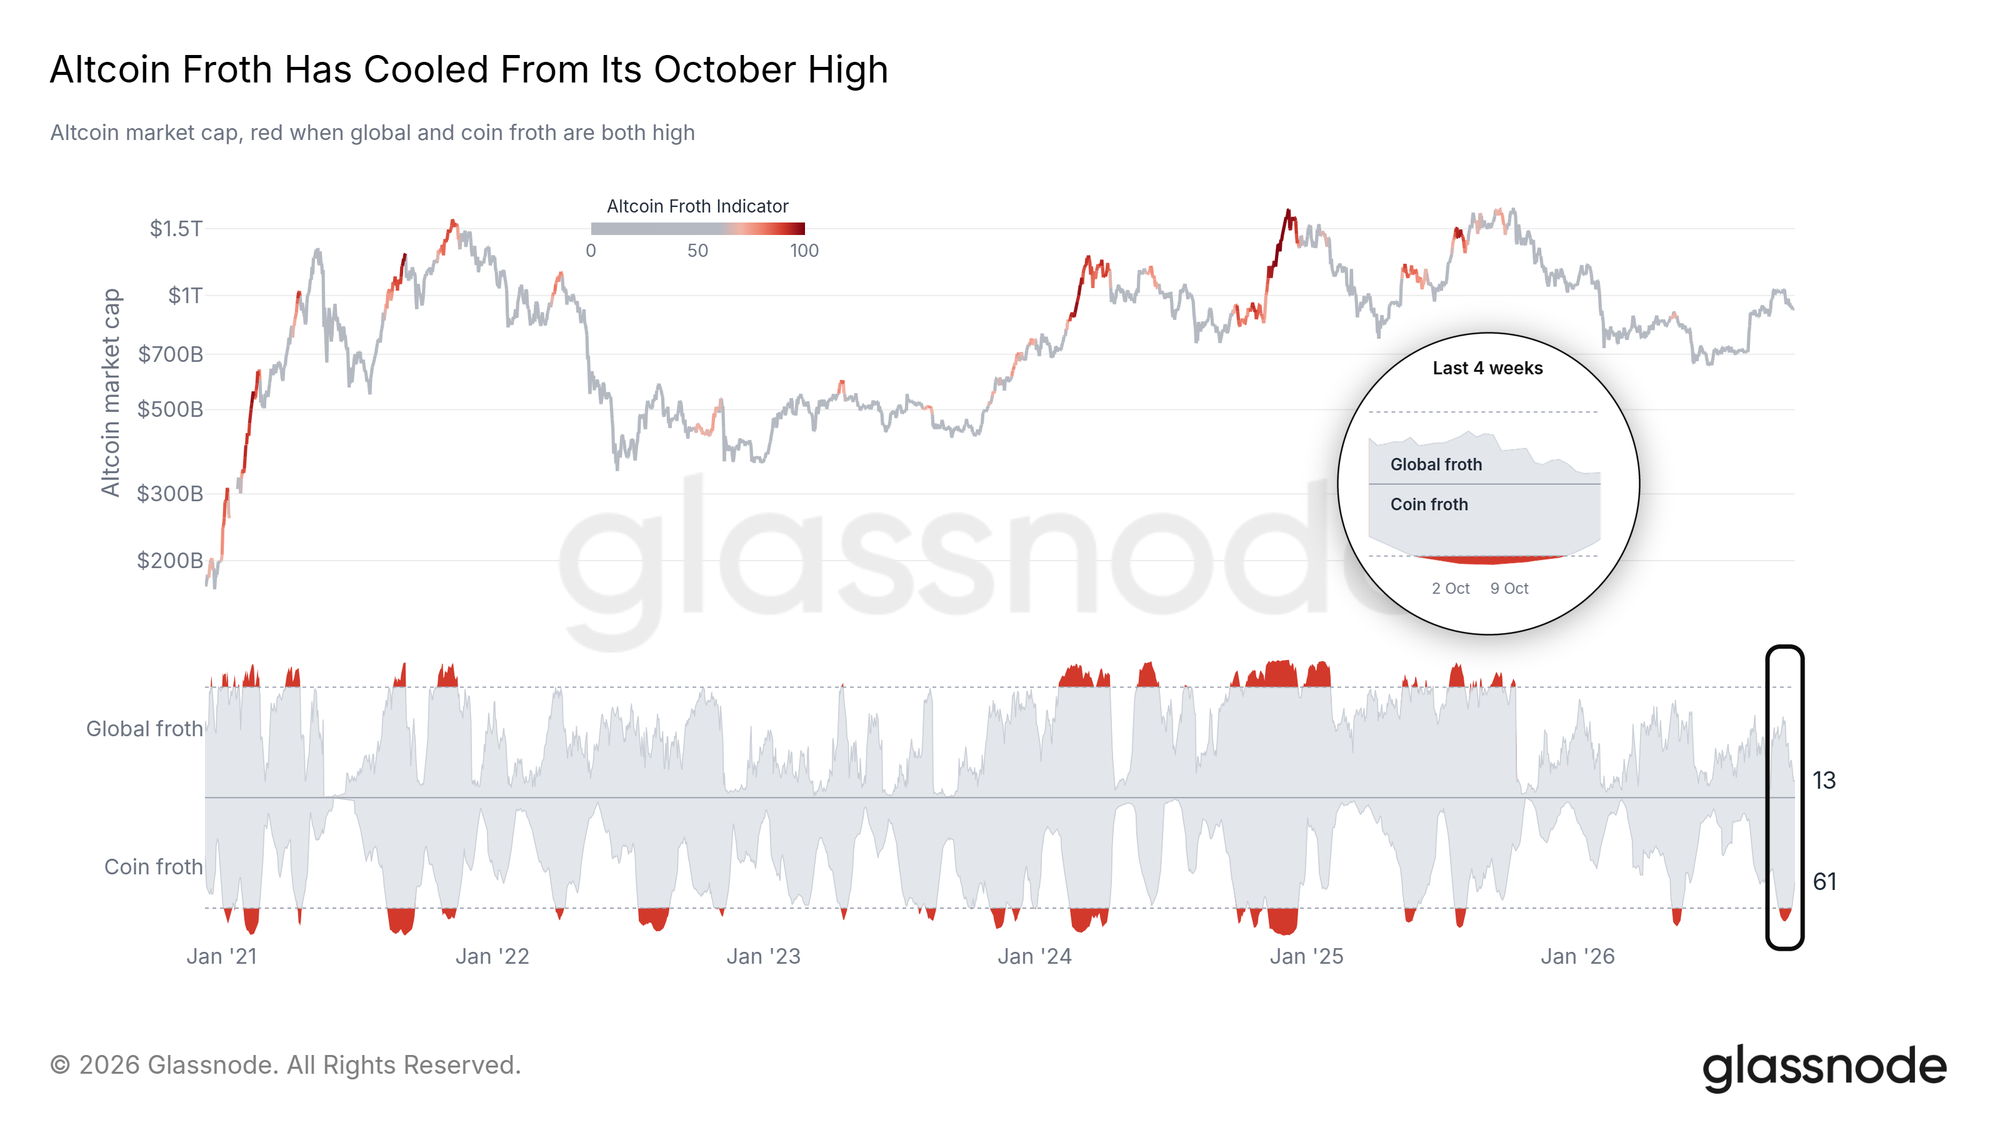
In last week's edition, we flagged crowded leverage inside single altcoins: coin froth, which tracks how many altcoins carry heavy leverage against their own past, sat in its high zone. Bitcoin slipped to the $80K bids on October 15, and over the following weekend the median altcoin fell about 4%, its largest weekend drop since May.
Coin froth peaked on October 7 and has since dropped out of its high zone. Global froth, the same test applied to the altcoin market as a whole, stayed below its high zone and has since fallen further.
Funding Back Near Its Lows
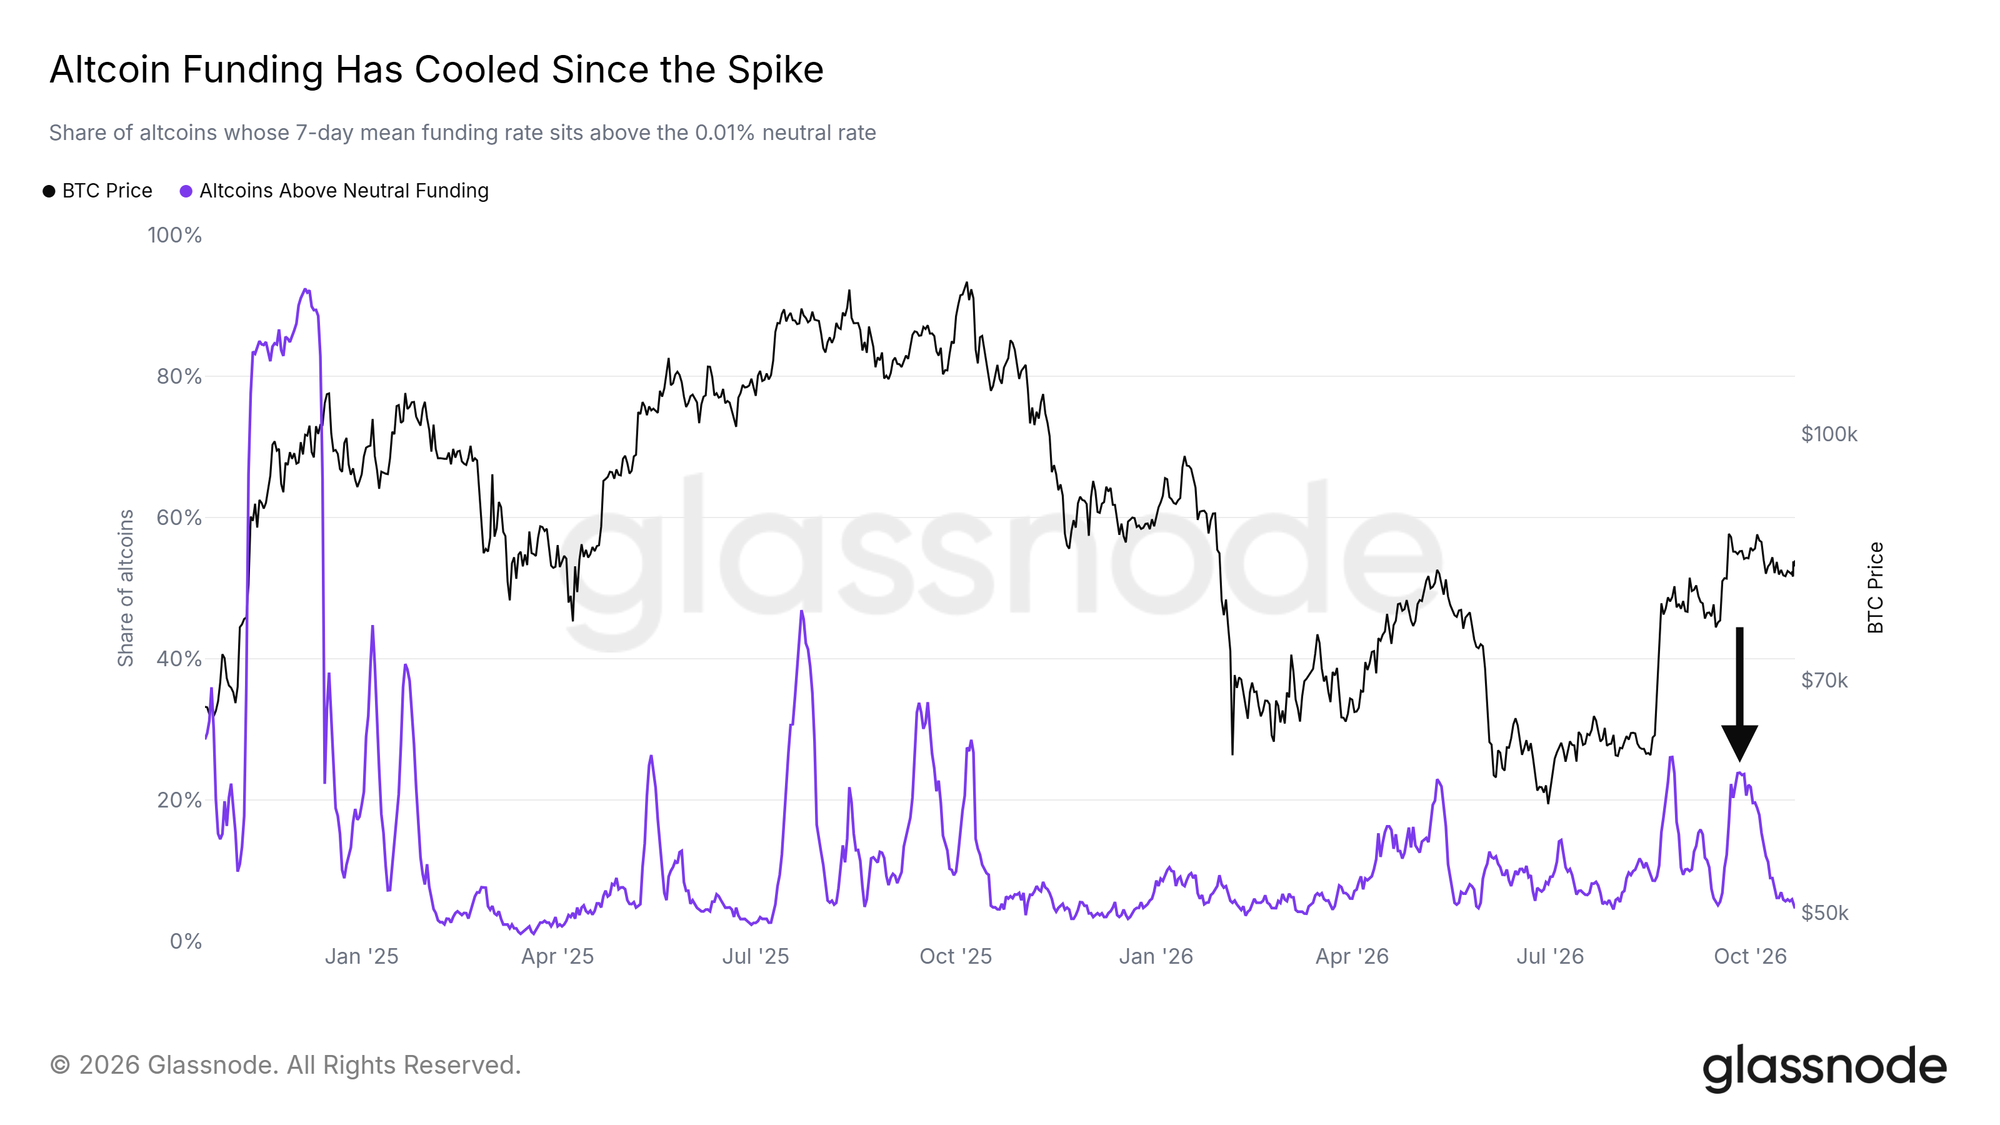
Funding rates show the same cooling. Funding is the fee that holders of long perpetual futures pay to shorts when demand for leverage runs hot. In late September, close to a quarter of altcoins paid more than the neutral rate. Fewer than 5% do now, near the bottom of the two-year range.
Note that open positions are only about 5% below their October peak at constant prices. With most of that leverage still open, a renewed rise in funding would be the first sign of fresh crowding.
Conclusion
Bitcoin is still boxed in. The October 15 sweep found buyers at the ETF and treasury cost bases between $80K and $81.5K, and profit taking has slowed since. Overhead, the 6 to 12 month cost basis, a block of asks and the largest liquidation clusters sit between about $85K and $87.5K.
A daily close above $87.5K, with ETF inflows repeating on rising volume, would show demand absorbing that supply. A daily close below $80K would put the average ETF and treasury holder at a loss and bring the True Market Mean near $77.6K into view. The Fed decides on October 28, and MSCI's list follows on November 11.
Data as-of October 21, 2026 for hourly price, realized profit and loss, the liquidation heatmap and the Binance order book; October 20, 2026 for daily on-chain metrics, altcoin froth, altcoin funding and macro series; and October 19, 2026 for ETF flows, the ETF cost basis, the True Market Mean and corporate treasury holdings. The September CPI print comes from the BLS release of October 14, 2026; the most recent daily points remain subject to revision.
Data through 2026-10-18, daily, and on-chain reserves through 2026-10-19. Tokenized gold is Tether Gold and PAX Gold across Glassnode's covered exchanges. The leadership strip compares trailing two-month returns. Exchange reserves are 30-day averages of the Bitcoin on each exchange's published Proof of Reserves addresses, for 11 exchanges holding at least 1,000 BTC there. Reserves, user balances and reserve ratios are as reported by Gate for its 2026-10-18 snapshot.
Disclaimer: This report does not provide any investment advice. All data is provided for informational and educational purposes only. No investment decision shall be based on the information provided here, and you are solely responsible for your own investment decisions.
Exchange balances presented are derived from Glassnode’s comprehensive database of address labels, which are amassed through both officially published exchange information and proprietary clustering algorithms. While we strive to ensure the utmost accuracy in representing exchange balances, it is important to note that these figures might not always encapsulate the entirety of an exchange’s reserves, particularly when exchanges refrain from disclosing their official addresses. We urge users to exercise caution and discretion when utilizing these metrics. Glassnode shall not be held responsible for any discrepancies or potential inaccuracies.