
What you build over a lifetime can carry meaning far beyond it. Thoughtful legacy planning can help ensure it continues to serve the people you care about for years to come.
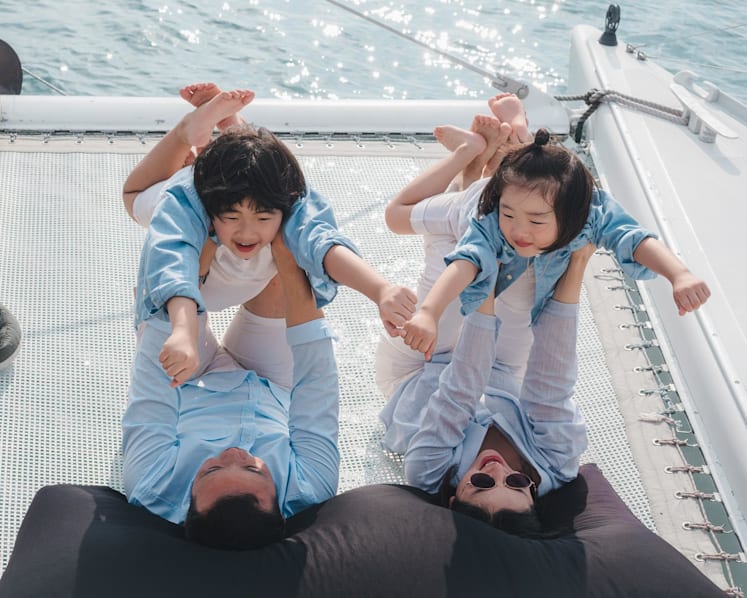
A legacy can help sustain what a family has built over time while creating new opportunities for loved ones. (Photos: Shutterstock)
New: You can now listen to articles.

This audio is generated by an AI tool.
20 Oct 2026 12:05PM
Your intentions may be clear at the outset: to provide for a spouse, support a child or preserve what you have built for the next generation. But over the decades, families rarely remain the same.
Children become financially independent. Grandchildren enter the picture. Family wealth may come to span businesses, investments and borders. Who needs support – and how you want to provide it – may also change.
For affluent families, legacy planning therefore goes beyond deciding how much to pass on. It can also mean considering how wealth is managed over time, how different needs are met and how a family’s wishes are carried forward.
Mr Lim Yuting, CEO of Prudential Financial Advisers Singapore, said clients increasingly want certainty that their legacy will reach the right people. “As families grow across generations, there’s also greater demand for plans that can adapt – such as changing who is protected or who controls the policy, instead of requiring a new policy each time.”
PruApex Legacy Index II (PALI II), an indexed universal life plan from Prudential, is designed with this longer horizon in mind. It combines legacy planning with market index-linked growth potential, while offering policyowners options to adjust how the policy is managed and paid out. For families planning across generations, four considerations can help shape how wealth is protected, grown and eventually passed on.
KEEPING YOUR LEGACY RELEVANT AS NEEDS CHANGE
Decisions made today may need to serve a family for decades. That means planning for current needs while leaving room for circumstances to change.
That long-term view can start early. PALI II can be purchased for a juvenile – what Mr Lim described as a “multi-decade play”. He said buying a policy when the life assured is young can mean lower insurance costs and more time for the account value to grow, while the death benefit can eventually support a subsequent generation.
As the years pass, the policy may also need to serve the family in new ways. A parent, for example, may initially take up PALI II with the intention of passing wealth to their child. If that child is later sufficiently provided for through other assets or policies, the policyowner can change the life assured to the child, allowing the policy to support the family’s legacy over another generation.
Continuity of ownership is another consideration. PALI II allows a secondary policyowner to be appointed two years after the policy begins.
“A typical scenario is a parent appointing their eldest child,” said Mr Lim. “Should the parent pass away, control of the policy transfers smoothly to the child, without the delays or disputes that can arise when a policy’s ownership is unclear. This helps to preserve both the value and intent of the legacy.”
BUILDING VALUE THROUGH DIFFERENT MARKET CYCLES
Family circumstances are not the only thing likely to change over decades. Markets will move through different cycles too, making the balance between growth potential and protection from market declines another consideration.
PALI II offers a fixed account, as well as an index account linked to a range of market indices. For the latter, policyowners can select up to three from a suite of seven. “These span different regions, asset classes, levels of volatility and complexity, giving policyowners options that align with their investment preferences,” added Mr Lim.
The suite includes standard market indices with capped returns and volatility-controlled indices with uncapped returns, subject to the prevailing participation rate. Policyowners who select a volatility-controlled index also receive a guaranteed additional crediting rate of 0.25 per cent per annum – a feature Prudential says is unique to PALI II.
The index account has a guaranteed floor rate of 0 per cent per annum, meaning negative index performance will not result in negative index crediting. Policyowners can also switch indices, subject to the policy’s switching conditions, if their investment preferences change.
FUNDING YOUR LEGACY AROUND YOUR PRIORITIES
A long-term plan also has to fit alongside financial needs in the present. How much you commit – and when – can affect the liquidity available for other priorities. To address this, PALI II offers single premium and multi-pay options.
“Single premium policies may sit well with individuals who have accumulated sufficient capital, but may be less suitable for those who need that liquidity for other purposes,” explained Mr Lim. “Having different payment terms allows one to decide on a payment term that addresses their needs and circumstances.”
Fully paid multi-pay policies also receive a one-time bonus crediting rate of up to 6.5 per cent on the total account value at the end of the premium term – a feature Prudential says is unique to PALI II. This rewards policyowners for maintaining their premium commitments, with the potential to boost their returns over time. The applicable rate depends on the multi-pay sum assured and premium term.
DECIDING HOW YOUR LEGACY REACHES LOVED ONES
Eventually, what has been built and planned needs to reach the people it was intended for. How that happens can matter as much as how much is passed on.
For some families, a lump-sum death benefit may provide immediate liquidity – for instance, to meet financial obligations or help balance what different beneficiaries receive. Others may prefer support spread over several years, particularly when providing for a dependant with ongoing care and financial support.
PALI II allows the death benefit to be paid in instalments over two to 10 years, so support can be provided progressively rather than all at once.
There is no single way a family’s needs will unfold over decades. Building flexibility into a legacy plan can help it adapt alongside them – while keeping sight of who the wealth is ultimately intended to support.
Learn more about PruApex Legacy Index II.
This article is intended for information only and does not consider specific investment objectives, financial situation or needs. You are recommended to seek advice from a Prudential financial representative before making a commitment to purchase a policy.
As buying a life insurance policy is a long-term commitment, an early termination of the policy usually involves high costs. The surrender value payable to you, if any, may be zero or less than the total premiums paid.
This policy is protected under the Policy Owners’ Protection Scheme, which is administered by Singapore Deposit Insurance Corporation (SDIC). For more information on the benefits covered and the limits of coverage, contact your insurer or visit the General Insurance Association of Singapore/Life Insurance Association Singapore or SDIC websites.
This advertisement has not been reviewed by the Monetary Authority of Singapore.