This article is taken from the June 2026 issue of The Critic. To get the full magazine why not subscribe? Find our subscription offers here.
The age-old trope that Christie’s are gentlemen trying to be auctioneers and Sotheby’s are auctioneers trying to gentlemen, has rarely been true, but I wonder if the major auction houses are really coming to terms with what it means to grow the business of art sales in today’s big-data world.
During my year off after A-levels in 1992, I spent a month interning at Christie’s. Like all art history students I was itching to get into a department to look at and handle art. Somewhat dismayed, I was instead sent to work in the basement, to Muniments.
Christie’s in the 1990s was on the cusp of becoming a serious art business. It was profitable, but was being dragged into the modern business world by the bouffant-coiffed Christopher Davidge — who brought modern business practices and commercial savviness to the club-like and occasionally rather fusty aroma of entitlement which pervaded 8, King Street in those days.
The archives were overseen by the eccentric and rather sweet Jeremy Rex-Parkes. He was about as far removed as it was possible to be, in both appearance and geography, from the smooth-suited aristocrat-aping specialist of the art departments above ground.
His lazy eye and ambulatory restriction were natural physical constraints, but he was kind and funny with a dry sense of humour. Disarmingly, he was sharper than his appearance suggested, with an encyclopaedic knowledge of sales, stock numbers, consignments and personalities.
From the basement, I settled for reconnaissance instead of full contact with art, and what a remarkable place it was. The entire archive of all Christie’s London sales, stretching back to 1766, historic sale catalogues and day books with all stock numbers, client information, consignment and sale details, were all meticulously stored on rolling shelves there.
I quickly learned the system and was able to resolve stock number queries, or “look-ups” as they were known. Essentially, the auction sale system has remained unchanged since the 18th century, which means useful data points reach back over two centuries.
Now we are in the era of big data, one would expect the two great auction houses to have digitalised their sale records, but they have not: death, debt & divorce drive consignments, sometimes resulting in price growth, but there has been no dramatic change in profit or trading volume.
The big annual global art market sale total remains about $60bn and has remained around that level for about a decade. In spite of the enormous transformation of computing skill and access to data available to the whole world, the art market sales model and its analysis remains moored to the ancient strategy familiar to James Christie and Harry Phillips.
The next and perhaps more important step is the standardisation of the classification of works of art
Over the summer I read a fascinating polemic, Art as an Asset in the 21st Century by David Kusin, a former curator at the Metropolitan Museum of Art, New York and since 1998 an art market economist.
Kusin’s thesis is that the art market, unlike every other sector that connects with wealth, has failed to create what he calls “actionable knowledge” by investing in the digitalisation of the data points that sit below the pavement of 8, King Street and elsewhere.
His claim is that an “unbroken data span can also power new methods to equalize disparate and contemporary price levels in relevant ways” and that major operators in the art markets (there are, he says, 150 submarkets, all with their own idiosyncrasies) need to hire staff who blend skills of numeracy, coding and connoisseurship in order to compete with the other wealth management companies, such as private offices.
Naturally the digitalisation of the data points is only the first step. The next and perhaps more important one is the standardisation of the classification of works of art. Trying to find a work of art either online or in a car index currently depends entirely on how that work was first indexed.
When I was a curator grappling with half a million objects, it was the indexing that saved us: simple but robust cataloguing/classification rules allowed for accurate and powerful searches to be effective within the context of that collection.
Applying the same rules to all works handled by art dealers, auction houses and any other operator would be a phenomenal task. The Getty Vocabularies art databases are a major start in the museum world but have been overlooked by the commercial market.
Whoever builds a commercial version would have the framework to sell actionable marketplace data: if sound principles are followed, the recent merger of Artnet and Artsy may create a Bloomberg for art.
Kusin writes that “the current chaotic state of nomenclature means that it is impossible to sort data”. This is, he reckons, the factor currently limiting sales growth.
Because of this data deficit, “financial intermediaries cannot apply their necessary standards to calculate risk, transaction costs and provide partnerships with principals in the buying and selling of art”.
If this sounds like an excessively financialised future for the art market, there is hope: Kusin’s clarion call is for “connoisseurs, applied mathematicians routinely working side by side” allowing “art price futures [to] trade constantly, lowering transaction costs and hedging the ownership risks of owning collections”.
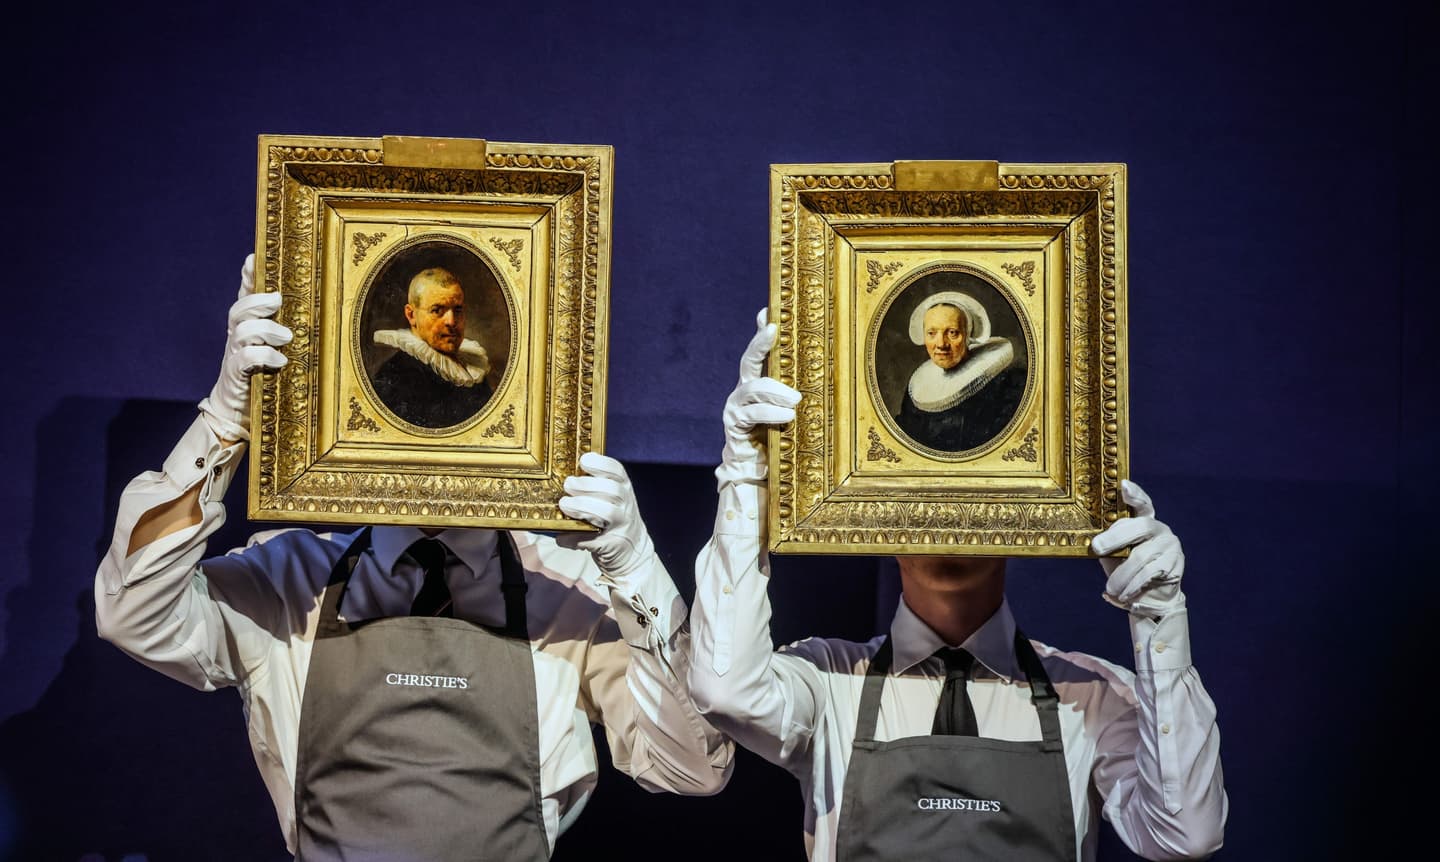
Futures in Rembrandt, anyone?