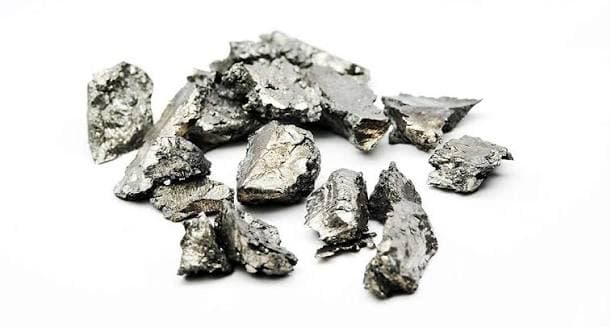
Japan is warning that it could run out of yttrium within months as Chinese export restrictions tighten supplies of the critical mineral, raising questions about whether Africa’s rare-earth deposits could help diversify a market dominated by China.
- Japan faces a potential shortage of yttrium within months due to tightened Chinese export restrictions, causing concern over supply security.
- Japanese officials have asked the US to help convince China to ease export controls as manufacturers struggle with dwindling stocks.
- Africa holds significant rare-earth deposits, but moving projects from development to commercial production is necessary to address Japan's immediate needs.
- Malawi's Kasiya project stands out for its notable yttrium content, but is still in development and not yet a commercial source.
According to the Financial Times, Japanese officials have asked the United States to help persuade China to ease its rare earth export curbs as manufacturers face dwindling supplies.
Yttrium is used in specialised industrial applications, including heat-resistant coatings for jet-engine components, electronics and semiconductor manufacturing equipment.
According to an analysis by Rare Earth Mining News, yttrium is among the rare earth elements most dominated by China. The US Geological Survey estimates global mine production at 10,000 to 15,000 tonnes of yttrium oxide equivalent in 2025, with China accounting for most output.
The US lacks a fully commercial facility to separate or refine yttrium, underscoring the supply concentration. US imports of yttrium oxide fell to zero in May and June 2026 before Reuters reported that a further 29 tonnes had been approved for July.
Africa’s rare-earth deposits could offer an alternative source over time, but their impact will depend on projects reaching commercial production and developing processing capacity.
Malawi’s yttrium potential puts its mineral resources in focus
Malawi’s Kasiya project, developed by Australian-listed Sovereign Metals, stands out because its mineral concentrate has shown a notable yttrium content.
The project is primarily known for its rutile and graphite resources, but its monazite-bearing mineralisation could also provide rare-earth elements as a by-product.
Sovereign Metals’ project studies have reported yttrium oxide accounting for about 11.9% of the total rare-earth oxides in Kasiya’s monazite concentrate. That figure refers to the composition of the rare-earth oxides, not the proportion of yttrium in the entire deposit. The company’s plans remain developmental, meaning the project is not yet a commercial source of yttrium.
According to Investair, the heavy rare earth content is highest in near-surface weathered zones. Sovereign Metals said the ratios of dysprosium-terbium and yttrium in the project’s total rare earth oxide basket are approximately seven times higher than those of the world’s five largest rare earth producers.
South Africa offers another point of comparison. Its Phalaborwa project aims to recover rare earths from phosphate-industry waste, with reported yttrium oxide representing about 2.3% of total rare-earth oxides in the relevant concentrate.
Tanzania’s Ngualla deposit is also among Africa’s major rare-earth projects. However, its overall rare-earth resource should not be treated as proof of a large, commercially recoverable yttrium supply without a project-specific breakdown.
For Japan, these projects represent potential longer-term alternatives rather than an immediate replacement for Chinese supplies. Producing usable yttrium requires more than extracting ore: companies must establish commercially viable recovery processes, build processing capacity and qualify products for industrial customers.