Last month, Burkina Faso President Ibrahim Traore inaugurated the country’s first national gold refinery, Raffinor-BF in Ouagadougou, with a promise to bring gold processing under government control. The plant’s first phase is designed to refine 164 tonnes annually, with a planned expansion to 515 tonnes. Burkina Faso reported 94 tonnes of total gold output in 2025, including industrial and artisanal production, and gold seized by the state.
Initial refinery capacity is roughly 1.7 times the country’s reported output, and the planned expansions would exceed it more than fivefold. The gap between mine production and processing capacity raises the question: Where will the additional gold come from, and who will control its passage through the plant?
Mali is building along a similar line. In June 2025, the military-led government broke ground on a refinery designed for 200 tonnes a year, developed with Russia’s Yadran Group and a Swiss investment company, with the state retaining a controlling interest.
Elsewhere, Ghana offers a civilian-government version of the same centralizing impulse. Since April 2025, the Ghana Gold Board, has held exclusive authority to buy, assay, and export gold from the artisanal and small-scale mining sector, pushing foreign traders out of the domestic market. The countries differ politically, yet each is moving to concentrate authority over the channel between mine and international buyers.
When governments become gatekeepers between the mine and the buyer, it becomes crucial to know how much discretion they acquire
Hafed Al-Ghwell
The sovereignty case does have some intuitive appeal. Gold dug from local soil should help pay for local roads, schools, power, and jobs; exporting it in rough form might seem like surrendering a valuable step to foreign processors. Refining does create technical capacity and can improve testing and traceability. However, refining itself captures only a thin slice of the gold value chain: Estimates put purity-refining margins around 0.2 to 0.8 percent, while much larger opportunities lie in extraction and in downstream activities such as jewelry manufacture and retail. A furnace can make a bar purer without creating the suppliers, skilled workforce, or customer base that turn a refinery into an industrial ecosystem.
Access to global markets brings another hurdle.
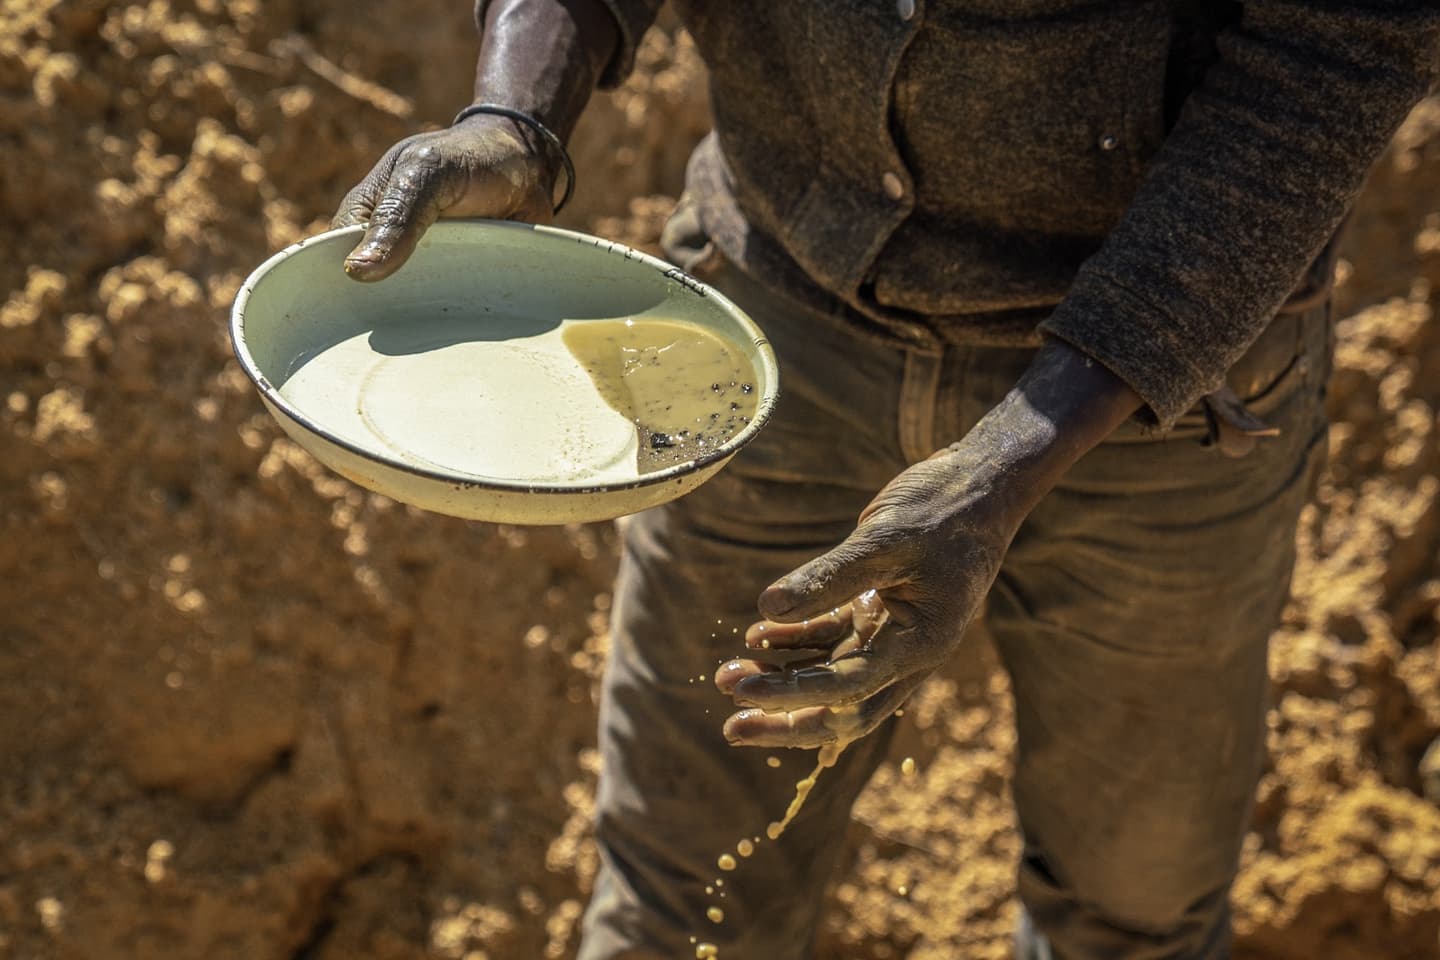
International bullion trading depends on trusted provenance and recognized standards as well as purity. The London Bullion Market Association’s Good Delivery status is a key credential for bars traded through the London market. As of this month, South Africa’s Rand Refinery remains the only African refinery on that gold list. Meanwhile, estimates place 72-80 percent of African artisanal and small-scale gold production outside formal declarations at the mine stage in 2022.
A state refinery cannot certify away hidden origins, nor can a monopoly guarantee that miners will use official channels if prices or payment terms are unattractive. What remains to be seen is whether new facilities expand the share of gold revenues reaching workers and public budgets — or simply move the gatekeeping closer to the mine.
When governments become gatekeepers between the mine and the buyer, it becomes crucial to know how much discretion they acquire. Burkina Faso’s July 2024 mining code increased the state’s automatic, free equity participation in new mining projects from 10-15 percent, while allowing the government and domestic investors to subscribe for at least another 30 percent. The legislation also established a Mining Development Fund for community projects and national security, promising a larger public return from mineral extraction.
Without transparent accounts showing disbursements, and beneficiaries, citizens cannot determine how much mining wealth reaches villages
Hafed Al-Ghwell
However, it also places development spending and security financing within the same revenue architecture. Without transparent accounts showing allocations, disbursements, and beneficiaries, citizens cannot easily determine how much mining wealth reaches villages and how much finances the state’s coercive priorities.
Mali offers another example of the distinction between acquiring ownership and generating public wealth. In October 2024, the government completed its acquisition of the Yatela gold mine, which had been inactive for eight years, from AngloGold Ashanti and Iamgold. The acquisition carried considerable symbolic weight: a government reclaiming a strategic asset from foreign corporate ownership. Yet any returns depend on the mine’s condition, rehabilitation expenses, remaining reserves, and the investment required to resume production. National ownership therefore creates an opportunity for future income while also transferring operational risks and closure obligations onto the public balance sheet.
Security financing, meanwhile, adds another concern. For instance, Russia’s Wagner Group became deeply associated with the military government’s search for security assistance after relations with Western partners deteriorated. The Kremlin subsequently expanded its role through Africa Corps, which assumed former Wagner operations in Mali in 2025. Public reporting on the Russian security relationship has described substantial costs and opaque payment arrangements, with claims that gold concessions directly financed every contract.
It exposes a wider institutional problem, especially when governments control mining rights, purchasing channels, and strategic mineral assets while operating under weak civilian oversight. Tracing the destination of every dollar becomes substantially harder. After all, gold revenues are fungible; money entering a state account can release other funds for security expenditure even without a direct transfer between a mine and a military contractor.
Ghana, on the other hand, demonstrates how the same concentration of authority can emerge without military rule or state coercion. During the second quarter of 2025, the Ghana Gold Board reported purchases of about 26 tonnes of artisanal and small-scale mining gold, valued at $2.62 billion, showing how a centralized purchasing system can bring sizeable foreign exchange flows under official management.
However, the figures cannot establish, by themselves, whether miners received competitive prices; politically connected illegal operators lost their protection, or environmental destruction declined. Those outcomes require independent audits, published purchasing prices, traceable concessions, and prosecutions reaching influential offenders.
In the absence of such safeguards, formalization risks becoming a contest over who controls the rent. Miners excluded from attractive legal markets still have strong incentives to seek alternative buyers, carrying the argument beyond the refinery gate and into West Africa’s persistent underground trade.
Gold sovereignty will be measured by what citizens can see: fair prices for miners, clean water for communities, accountable spending, and services paid for by mineral wealth. Until those gains reach beyond state offices and furnace walls, the gold may still change hands while poverty remains.
Hafed Al-Ghwell is senior fellow and program director at the Stimson Center in Washington and senior fellow at the Center for Conflict and Humanitarian Studies.
X: @HafedAlGhwell