
ET Intelligence Group: The Fairfax deal will bring fresh capital and new management to IDBI Bank, but turning around the lender will not be without challenges. Its success will hinge on the new management's ability to navigate employee resistance and operational hurdles.
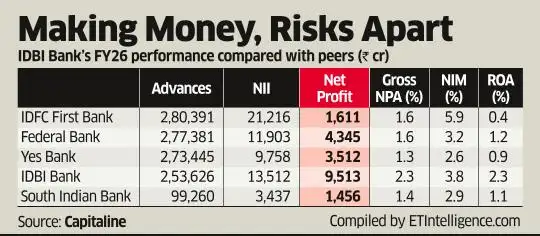
In addition, though asset quality has improved over the past few years, the gross non-performing asset ratio (GNPA) ratio remains higher than that of comparable private sector peers. On profitability front, the bank ranks above peers considering net interest margin (NIM) and return on assets (RoA). For the new management, the task therefore will be to preserve the bank's strong profitability while improving asset quality and sustaining earnings growth.
 ET Bureau
Opposing the government's divestment plan, the United Forum of IDBI Officers & Employees has demanded to suspend the stake sale process. Another key challenge will be to transform the bank's public-sector legacy into a more agile, private-sector entity without disrupting employee morale and business continuity.
Also Read: Private banks' margins fall as FCNR deposits raise funding costs
The Cabinet Committee on Economic Affairs, last week, approved the sale of a 60.7% stake in IDBI Bank to Canada-based Fairfax Financial' subsidiary for ₹52,878 crore. The deal has raised the prospect of a valuation re-rating for IDBI Bank, which depends on the efficiency of execution.
Improving asset quality will remain one of the bank's key priorities. While it has made significant progress in cleaning up its balance sheet, its asset quality still lags that of many peers. Its GNPA declined to 2.3% in FY26 from 3% in FY25. Federal Bank's GNPA was 1.6%, IDFC First Bank's was 1.6% and Yes Bank's was 1.3% while South Indian Bank was at 1.4% in FY26, indicating scope for IDBI Bank to further improve its asset quality.
Also Read: Banks also count cost of insurance payout curbs
IDBI Bank's RoA of 2.3% was higher than that the peers as of March 2026. Federal Bank's RoA was 1.2%, South Indian Bank at 1.1%, Yes Bank at 0.9% and IDFC First Bank at 0.4%, reflecting IDBI Bank's higher profitability relative to its asset base.
With a 3.8% NIM, the bank ranks at the higher end of its peer set, trailing only IDFC First Bank's NIM of 5.9%.