
Mumbai: International investors have voiced their concerns to Indian tax authorities over the use of the 'judicial anti-avoidance rule' by Income-tax officials to deny reliefs.
They have sought government intervention in tackling the issue which has become a bee in the bonnet for several foreign direct investors like MNCs, private equity houses and venture capital funds.
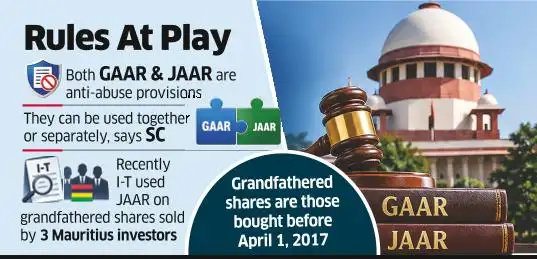
The rule, commonly known as JAAR, was invoked to reject tax benefits claimed by at least three Mauritius investors on the sale of 'grandfathered shares' - stocks that were acquired before April 1, 2017. ET reported this on September 17. Most foreign investors and tax practitioners believe that this goes against New Delhi's intent and should be resolved quickly.
 ET Bureau
International investors, belonging to the Asia Securities Industry & Financial Markets Association (ASIFMA), met Central Board of Direct Taxes (CBDT) officials about a week ago to put across the point, two persons aware of the meeting told ET.
An influential industry body, ASIFMA, has positioned itself as the unified voice for discussing policy matters with regulators, central banks and governments. "It may, however, be difficult for CBDT to address the JAAR issue through a circular as such a notification may run into legal hurdles. So, it has to be taken up with the government for legal amendment," said one of the persons.
Now, here's the bone of contention in the use of JAAR: Under the amended India-Mauritius treaty, profits from the sale of grandfathered shares are spared from capital gains tax; further, in March, CBDT said gains from such share sales would not be impacted by the General Anti-Avoidance Rules (GAAR), which have been used by the I-T department to disallow treaty benefits where it suspected that the entity set up by the foreign investor in a treaty jurisdiction (like Mauritius or Singapore) lacked 'commercial substance'.
"Investors conveyed the point that both GAAR and JAAR are anti-abuse provisions that are invoked to tax investors which resort to artificial structures to avail tax benefits. So, using JAAR after CBDT prohibited the use of GAAR for grandfathered shares is a somewhat retrograde step," said another person.
CBDT, sources said, is of the view that any regulatory change to ensure that JAAR cannot be invoked in matters that are protected from GAAR should ideally be done through a change in law. This is because the Supreme Court, in its January 2026 landmark decision on the American investment firm Tiger Global, held that both GAAR and JAAR can be invoked together or separately by tax authorities.
"Under the circumstances, foreign investors were told that an executive decision to extend the protection on grandfathered shares from JAAR could be construed as going against the Supreme Court," said a senior tax professional.
GAAR, applied when tax benefits exceed ₹3 crore, is a codified law while JAAR emanates from case law. However, the stand in English common law, which endorses taxpayers' right to arrange their affairs to reduce tax, was famously questioned by the Indian Supreme Court in 1985.