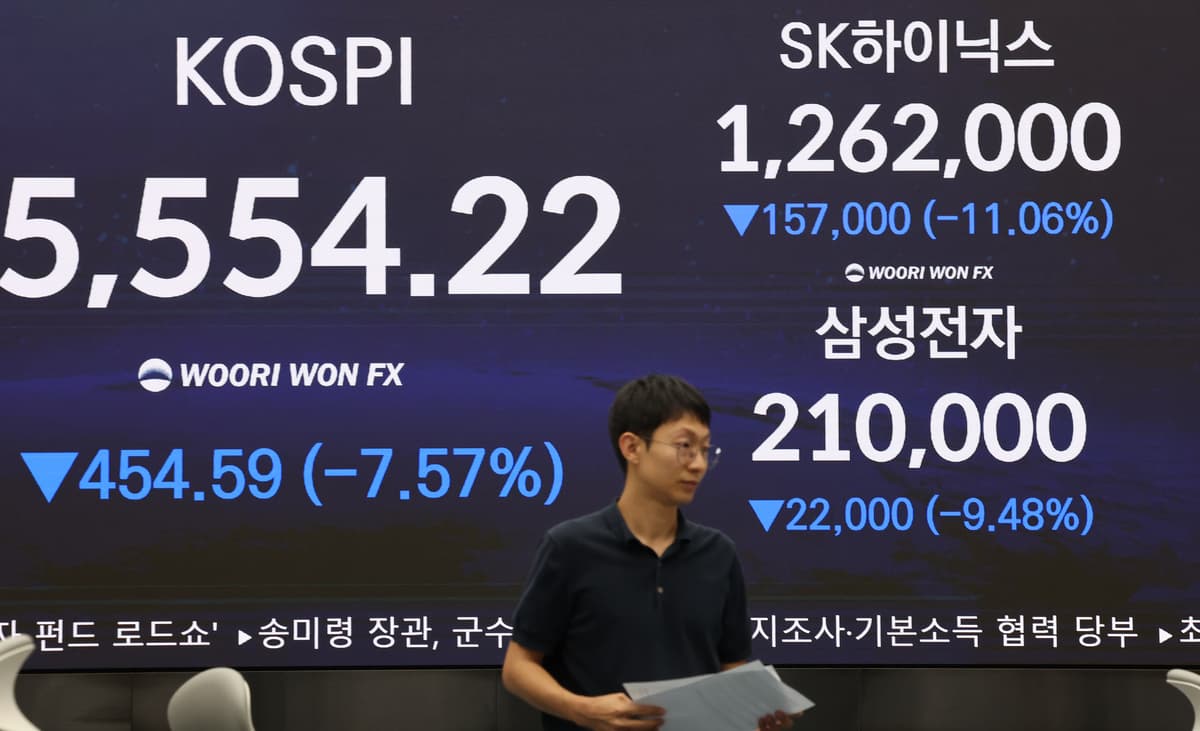
South Korea's KOSPI index plunged again as Chinese memory chipmakers closed the technology gap, borrowing costs stayed high and credit risks mounted around artificial intelligence, reviving memories of the market rout in July. As in July, large-cap chip stocks including Samsung Electronics (005930.KS) and SK hynix (000660.KS) led the index lower amid aggressive foreign selling. This time, however, there is little sign of a rebound trigger: in July, bargain hunting by retail investors and massive share buybacks propped up the market, while now there are few buyers willing to absorb what foreigners are selling. With doubts over the durability of chipmakers' medium- and long-term earnings, a vacuum in buying support and mounting funding pressure across the AI industry, retail investors have turned to panic as the market slides once more.
The KOSPI fell for a seventh consecutive session to 5,554.22, according to the Korea Exchange on the 15th, tracing a path similar to the July selloff. In July, the index tumbled 32.64% from 8,303.41 on the 1st to 5,593.56 on the 30th. In both episodes, selling spread first through large-cap chip stocks such as Samsung Electronics and SK hynix, dragging the broader index down.

The common shock in both the July and October selloffs is the technological advance of China's ChangXin Memory Technologies (CXMT) and concerns over expanding memory supply. In July, reports that CXMT was pursuing an initial public offering and planning to expand production capacity stoked fears of intensifying supply competition in the global memory market. This time, news of CXMT's new technology development and plans to launch server DDR5 products has raised anxiety that the dominance of Samsung Electronics and SK hynix could be broken.
High borrowing costs have also returned. In July, rising interest rates at home and abroad pressured equities, while in October, U.S. consumer price index data released on the 14th came in above market expectations, raising the odds of a rate increase. Slowing revenue growth at Anthropic has drawn attention as well, deepening doubts about the sustainability of AI infrastructure investment.
Lee Jin-woo, head of the research center at Meritz Securities (008560.KS), said the nature of the debate has shifted. "Three months ago, the core question was whether companies could recover the money they had invested in AI and turn a profit. Now the question is whether they can keep investing at all, with funding costs higher," he said. "The underlying issue of whether the investment can continue is the same, but there is growing concern that the funding burden could lead to a broad pullback in AI investment."
A shortage of buyers to absorb foreign selling is another weight on this selloff. Foreign investors appear to be shifting money out of Korean equities and into U.S. assets as risk aversion builds in an uncertain macroeconomic environment. Share buybacks of 15 trillion won ($10.5 billion) by Samsung Electronics and 40 trillion won ($28 billion) by SK hynix had supported the market in August and September, but the vacuum in buying support deepened this month as both programs effectively wound down.
Retail sentiment has also weakened, in contrast to July, when individual investors stepped in to buy on the dips. Jang Mun-soo, head of the research center at Hyundai Motor Securities (001500.KS), pointed to that difference. "In July, individual investors bought aggressively on expectations of a rebound, but in October sentiment is weak and the market cannot find a trigger for a rebound," he said. Eun Chi-kwan, head of equity management at Korea Investment Management, added, "Trading value from individuals has plunged and institutional money is unlikely to flow in, so there is not enough domestic demand to absorb what foreigners are selling."
Technical indicators are also fueling concern about a downtrend. Based on the closing price on the 13th, the KOSPI stood 5.5% below its 200-day moving average of 6,385.43, breaking below the long-term trend line for the first time since July 29-30. On the 14th, the gap with the 200-day line of 6,395.03 widened to 6%. Still, in 91 of 124 cases since 1995 in which the KOSPI fell below its 200-day line, or 73.4%, the index recovered the level within two weeks. In July, it regained the line in two days. Whether the 50-day moving average falls below the 200-day line, a pattern known as a dead cross, is another variable in gauging the risk of a prolonged decline.
Lee Young-gon, head of the research center at Toss Securities, said the two episodes share key features. "In both July and October, leading chip stocks dragged the market down, foreign selling continued and concerns over the durability of AI companies' earnings went unresolved," he said. "Investors should refrain from panic selling, but rather than expecting returns right now, they should manage risk and maintain a stable portfolio."