Getting vehicle finance in Namibia is not simply about finding a car you can afford each
month.
Banks and finance providers assess your income, existing debt, credit history, banking behaviour, the vehicle being financed and whether the overall loan fits your financial position.
That is why two people earning similar salaries can receive different finance decisions.
If you are searching for vehicle finance requirements in Namibia, the key is to understand what lenders assess before applying.
What do banks look at when you apply for vehicle finance?
The main issue is affordability. A lender needs to establish whether you can realistically repay the vehicle finance without becoming overextended.
The Bankers Association of Namibia’s Code of Banking Practice states that credit assessments may consider income and expenses, the dependability of income, previous financial behaviour, credit information, existing accounts, age, security and assets and liabilities.
In practical terms, lenders commonly look at:
- Your monthly income
- Your existing monthly debt repayments
- Your normal household expenses
- Your credit history
- How you manage your bank account
- The stability of your income
- The vehicle’s age and value
- The deposit being paid
- The proposed repayment period
- The documentation supporting your application
There is no single publicly published formula that determines every vehicle-finance approval in Namibia. Each lender applies its own credit policies.
YOUR DISPOSABLE INCOME MATTERS
Your salary alone does not determine how much you can borrow.
A lender looks at what remains after considering your existing financial commitments and expenses. This remaining amount is often referred to as disposable income.
For example, someone earning N$20 000 per month may appear able to afford a N$5 000-vehicle instalment.
However, if that person already has substantial loan repayments, credit-card commitments and other expenses, the available income for another loan may be much lower.
This is why a vehicle instalment that looks affordable on a calculator can still be declined by a bank.
THERE IS NO UNIVERSAL “25% RULE” YOU SHOULD RELY ON
You will often see people online claim that a bank will approve a vehicle if the instalment is below a particular percentage of your salary.
Treat these rules cautiously.
Banks assess the complete financial picture rather than applying one publicly advertised percentage to every applicant. The important point is that income is only one part of the assessment.
VEHICLE AGE CAN CHANGE THE FINANCE STRUCTURE
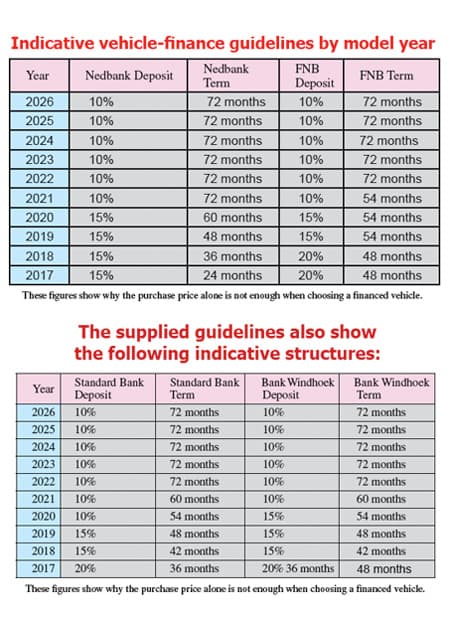
The age of the vehicle can make a significant difference to the deposit and repayment period.
The vehicle-finance guidelines supplied for this article show different requirements across Nedbank, First National Bank (FNB), Standard Bank and Bank Windhoek.
The figures on this page should be treated as indicative guidelines rather than guaranteed approval terms.
The final terms offered to a customer depend on the lender’s assessment and the specific vehicle.
A cheaper older vehicle may require a larger deposit and a shorter repayment period.
That can produce a higher monthly instalment than a buyer expected.
The differences are important because the same vehicle can have a different finance structure depending on the lender.
Always confirm the actual terms available for the specific vehicle before assuming that a particular deposit or repayment period applies.
The post Why Banks Reject Applications appeared first on The Namibian.