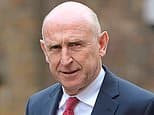
The Chancellor is set to hike taxes on banks at this month's Budget, as he scrambles to raise enough cash to cover a multibillion-pound shortfall.
Lenders fear John Healey will not spare the sector from tax rises like his predecessor Rachel Reeves did, and raise the bank levy from the current level of 3 per cent to 8 per cent.
For many, the prospect of tax hikes on banks makes sense after the top four collectively made about £15billion profit in the first six months of the year thanks to rising interest rates.
It may win him praise from the Labour backbenches and the unions, who argue that the banks should be taxed on their higher profits to fund energy bill support.
However, industry figures warn it will hit investment and the economy, with fears it will drive up business and mortgage costs.
John Healey is set to raise the bank levy as the sector posts bumper profits
Would higher bank taxes hit the economy?
The Chancellor faces a borrowing headache as the Middle East conflict is driving borrowing costs higher and therefore limiting his headroom.
He needs to find extra cash to meet the fiscal rules and fund increased defence and welfare spending.
Despite declaring banks a 'jewel in the crown of the British economy,' he's now looking to tap them for additional revenue.
An increase in the bank levy to 8 per cent is expected to bring in an extra £2billion a year.
It is one of the few revenue raisers left that sit outside Labour's manifesto pledges not to raise general income tax, VAT, National Insurance or baseline corporation tax.
Targeting the financial sector with higher levies comes with trade-offs, though.
Banks already pay the surcharge on qualifying profits on top of 25 per cent corporation tax.
They argue that even higher taxes risk making the UK uncompetitive and would encourage international banks to shift their London and UK bases overseas.
A typical corporate and investment bank operating in London pays a total tax rate of 46.5 per cent, compared with 42.2 per cent in Amsterdam, 39.1 per cent in Frankfurt and 27.9 per cent in New York.
The boss of JP Morgan, Jamie Dimon, has previously said he would scrap the bank's plans to build a £3billion HQ in Canary Wharf.
It comes at a time when the Government is banking on growth and fresh investment to lift Britain's fortunes.
Trade body UK Finance has warned further increases to bank taxes 'would weaken the UK's competitiveness, discourage investment and job creation, and work against the government's ambition to deliver growth in every postcode'.
Banks have aggressively lobbied the Chancellor to keep the sector out of any potential tax rises in his maiden Budget.
A coalition of business groups warned Healey that a tax raid could backfire by sparking an exodus from Britain, therefore threatening growth.
In a letter to the Chancellor, they said: 'As well as weakening investor confidence and damaging UK attractiveness, a higher tax burden may not necessarily generate higher tax receipts if capital, people and businesses move elsewhere.'
How will it affect mortgage rates?
A looming tax raid on the banking sector may seem distant for the average household, but experts warn it could drive borrowing costs higher.
Any increase to the banking surcharge could be passed on to consumers through higher mortgage rates and other loans, trade body UK Finance warned last month.
To protect their profit margins, domestic banks could raise their mortgage prices or offer less competitive rates on new deals.
There is also a risk that reducing the share of profits banks retain could affect their ability to invest in new products and services.
A higher surcharge may limit flexibility and therefore lead to tighter lending criteria, making it more difficult for prospective buyers to secure a mortgage approval.
The extent to which any of the tax hike is passed on will depend on competition between lenders and the strength of demand for borrowing.
Fixed-rate mortgages, which are particularly influenced by market expectations for future interest rates, will not automatically increase.
However, if banks respond by charging more for new mortgages, borrowers could face higher rates when buying a new home or remortgaging.
How will it affect savers and investors?
If the government goes ahead with raising taxes on banks, savers will also be punished.
Lenders may cut interest rates on savings accounts to try to recoup the lost revenue caused by higher taxes. Lower rates while inflation is rising means reduced real returns for savers.
Savers who rely on dividend income from UK banks may also take a hit after the Budget if banks reduce shareholder payouts to cover the tax bill.
Neil Wilson, UK investor strategist at Saxo said: 'Any percentage increase in the surcharge would likely hit earnings per share by a similar or slightly greater level, lowering profits, return on equity and potential dividends or buybacks.'
Russ Mould, investment director at AJ Bell, added: 'The government might argue that banks are doling out significant amounts of money in dividends to shareholders, implying there is plenty of scope for them to pay a little bit more tax.
'The flipside is that any hit to dividends to offset higher taxes would penalise the large number of people in retirement who invest in banking shares for income.'
And bank shares could become less attractive to investors. Millions of investors who invest through stocks and shares Isas are already seeing their investments fall.
Major banks, including Lloyds and Barclays, saw shares slip this morning, which will also affect investors holding funds tracking the FTSE 100.
Kathleen Brooks, research director at XTB, said: 'The risk is that downward pressure will now build, and this will dim the attractiveness of the entire index.
'We will need to wait for the Budget to get the details of this tax, afterall, this is the Labour Party and they are well known for their U-turns.
'The Chancellor may need to water down plans for a tax if he wants to avoid denting both the economy and the FTSE 100.'
DIY INVESTING PLATFORMS
AJ Bell
AJ Bell
Easy investing and ready-made portfolios
Hargreaves Lansdown
Hargreaves Lansdown
Free fund dealing and investment ideas
interactive investor
interactive investor
Flat-fee investing from £4.99 per month
Freetrade
Freetrade
Investing Isa now free on basic plan

Trading 212
Trading 212
Free share dealing and no account fee
Affiliate links: If you take out a product This is Money may earn a commission. These deals are chosen by our editorial team, as we think they are worth highlighting. This does not affect our editorial independence.
Compare the best investing account for you