CFR President Michael Froman analyzes the recent European protests ahead of upcoming elections and changing U.S. relations.
By experts and staff
Greetings from Europe (or, at least, London), where the mood, like the weather, has turned decidedly foul in recent days.
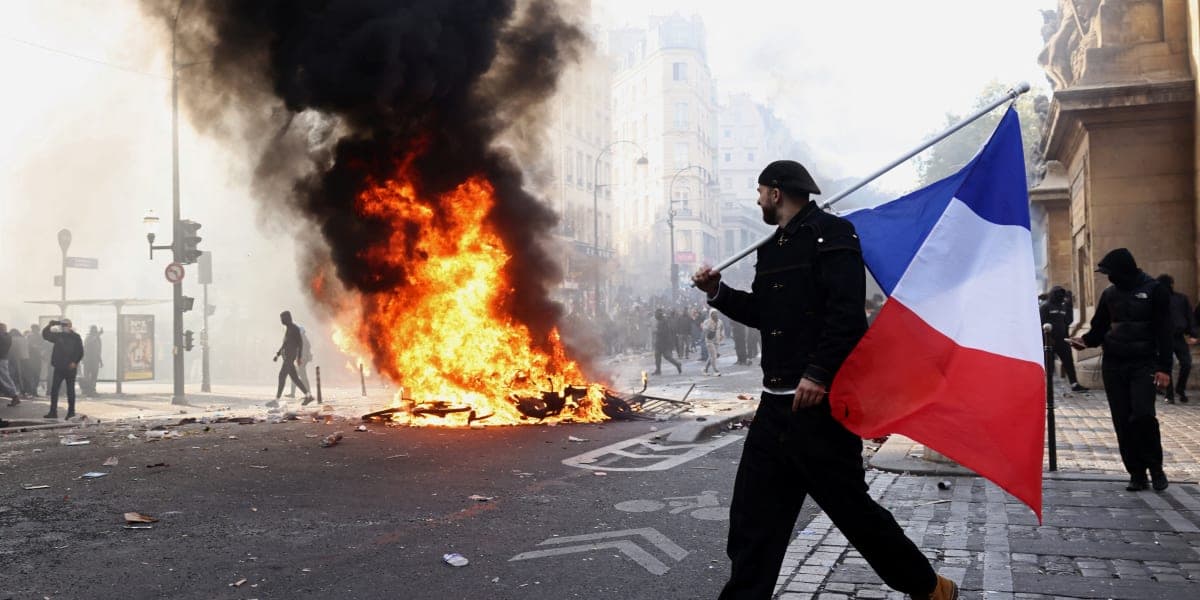
Top of mind are the protests in France, which could well be the canary in the coal mine of a broader political and economic crisis in the works. France, of course, has a long tradition of taking to the streets, from farmers to the Yellow Vests.
But what we have witnessed in recent weeks seems to be of a categorically different character. These protests stem from a fundamental collapse of the French social contract: the government is failing to invest effectively in its education system, sends an ever-increasing share of its money to pensioners, relies on an ever-shrinking pool of young workers to pay for them, subjects its people to years of anemic growth, and, crucially, offers no viable path to prosperity and growth, all while facing an affordability problem. In this context, it should come as no surprise that the streets are filled with France’s young: one in five of them is unemployed.
The protests are also noteworthy because they are taking place against the backdrop of an ascendant political far right. Those parties, heading into France’s April 2027 election (not to mention Germany’s rolling election schedule), will seek to capitalize on the resentment that the violence of these protests has fostered and, if successful, to implement their anti-immigrant policy agenda.
Downstream from breaking the social contract is a potential debt crisis with no obvious escape mechanism. Economic growth is already so depressed that the government cannot tax its way out of this hole; the demonstrations show that no party will long survive if it attempts broad cuts to government spending; and Paris has committed itself to doubling its defense spending from 2017 levels by next year, given the combined pressure of Moscow and Washington.
Investors are skeptical whether France can solve these problems, given its political sclerosis, pushing up borrowing costs further. The public sector eats up about 57 percent of France’s GDP. (The equivalent measure in the United States, including state and local governments, is 37 percent.) According to a report commissioned by the French government, France’s annual interest payments are on track to rise by 59 percent by 2030.
France and the United Kingdom (UK) both face the challenge of payments they cannot afford fiscally, cuts they cannot afford politically, and spending they cannot afford to ignore geopolitically. The UK has managed to avoid an economic crisis so far through somewhat stronger growth and moves from its own central bank to backstop its debt. France doesn’t have all of the same tools at its disposal. Nor does Italy or Belgium, where protests have also sprung up this month.
This is all coming to a head in the context of an abrupt shift in the United States’ approach to Russia, with major implications for Europe and its security. Over the last few weeks, U.S. President Donald Trump waived a new bipartisan law imposing new secondary sanctions on Russia and cut a deal to purchase Russian diesel. In addition, Trump continued to voice his displeasure with Ukrainian President Volodymyr Zelenskyy and said, “Russia, frankly, has been fine on Ukraine,” seeming to discount the near-constant missile and drone attacks on major Ukrainian cities and infrastructure. U.S. Special Envoy Steve Witkoff added praise of Russian President Vladimir Putin as a “humanitarian” for releasing U.S. citizen Stephen Hubbard, a seventy-four-year-old retired schoolteacher from Michigan who was sentenced to six years in a Russian penal colony and charged with being a Ukrainian mercenary.
These actions and comments have brought us to the lowest point in the U.S.-Ukraine relationship since the infamous “you-don’t-have-the-cards” Oval Office meeting in early 2025. The upshot of this for Europe is the realization again that the United States still wields outsized influence on the course of this war even though it is not directly providing packages of military assistance. All the talk of European rearmament is, at this stage, fundamentally talk. It will be years before these investments produce results that can take the place of a reduced U.S. commitment. Until that day comes, the United States remains the only outside power that can meaningfully affect the outcome of the war.
Will this perfect storm of economic, political, and national security challenges finally be enough to incentivize European leaders to do the things that they have long known they need to do—including to implement economic reforms (à la the Draghi or Letta reports), consolidate Europe’s military industrial base, and operate effectively together with a degree of autonomy? This will turn, in part, on whether these Western democracies can address their political dysfunctionality. The UK is on its sixth prime minister in ten years; French President Emmanuel Macron is on his seventh.
For its own sake as well as ours, Europe needs to address the structural weaknesses that are fueling both the protests and the geopolitical dependencies. Until they get their houses in order, we are all in for a long winter.
Let me know what you think about the developments across Europe and what this column should cover next by replying to [email protected].