
Number 116 on Rue Réaumur in Paris sits at the crossroads of the two worlds that define Revolut. On one side lies the historic financial district centered around the stock exchange; on the other, the Sentier neighborhood, home to much of the French capital’s technology ecosystem. It is at this intersection of finance and technology that the bank is preparing its new headquarters for Western Europe.
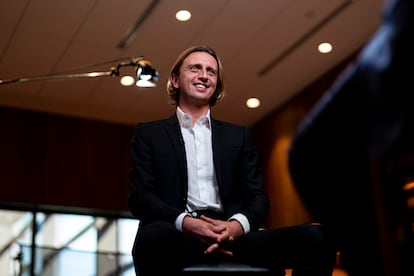
Inside, the building is still under construction: plastic sheets cover the floors, protective tape lines the walls and the air smells of fresh paint. The offices are still months away from being completed, but on this particular day the atmosphere has the feel of a stage being readied for a special guest: the bank’s founder and chief executive officer, Nik Storonsky.
The man who has upended the banking industry bears little resemblance to the traditional banker stereotype. Born 42 years ago in Dolgoprudny, on the outskirts of Moscow, and later naturalized as a British citizen, he did not spend decades climbing the ranks of a major financial institution, nor does he come from the classic mold of banking leadership. He also doesn’t speak like someone concerned with pushing whichever product delivers the highest sales.
His focus is on identifying problems and finding the most efficient way to solve them. Trained in mathematics, physics and economics, his way of thinking and speaking still reflects that quantitative background: spot the flaw, measure it and find the most direct route to fixing it. Speed and competition have been recurring themes throughout his life. As a young man, he competed as a swimmer in Russia before channeling that same drive into a banking industry he regards as full of flaws.
Storonsky did not invent credit cards, savings accounts, loans, insurance or investment funds. What he did change was the way those products are delivered, bringing some of the principles of the world’s largest technology companies into banking: a simple app that gives customers access to the full range of services, a subscription-based model, constant product launches and an experience designed around the user.
Nor does he fit the mold of the tech visionary who claims to have known from day one what a bank for the digital age should look like. His original ambition was far more modest: to solve a problem he faced while traveling, namely how to pay in foreign currencies without losing a chunk of money to fees. Once that problem was solved, he went after the next one.
Question. What problems do you still see in the banking industry that you would like to fix?
Answer. Many; there are lots. But one thing we still need to solve is private banking. Right now fees are very high, products are pretty poor and there is still a lot of manual interaction with clients. You need a private banker to call you, you tell them what you want to do and then they execute it. In general, the experience is expensive, not transparent at all and I’m not sure if it is adding that much value to customers.
Q. Your ambition is to build the first truly global bank. Why has no one achieved that so far?
A. One of the main problems of traditional banks is that they were built a long time ago on legacy systems. In addition, many didn’t even own their systems but outsourced them. As a result, they were set up to operate in a single country. And then, when they wanted to enter another market, instead of scaling their systems, they bought another bank. In the end, many large groups are made up of smaller banks, each with different systems that don’t talk to each other. Our advantage is that we have centralized systems that we can scale in each country simply by adapting them to the local market, which other banks can’t do.
Q. What sets Revolut apart from a traditional bank when it comes to launching a new product?
A. At legacy banks, it’s almost impossible to get something new off the ground. First, because they don’t have the systems and capabilities to launch products quickly. And second, because not only are they heavily regulated, but many of their internal processes are designed precisely to slow initiatives down. If you do few new things, you also have fewer possibilities of breaching regulation.
Q. You have previously said that an IPO would help build greater trust. Does Revolut need to go public to become one of the world’s largest banks?
A. The reality is that [an IPO] also has a lot to do with marketing. About 10 years ago, we did some fundraising on crowdfunding platforms, and it wasn’t because we needed capital. It was more about creating awareness of our product and getting more customers. If your customers are also shareholders, they’re very passionate about the product and talk about the bank to their friends, family and acquaintances. The same happens in an IPO. It’s not just a matter of trust; it also gives our customers the ability to participate in the company’s growth. They become more vocal about our services and are more likely to recommend us.
Q. Revolut generates substantial revenue without the massive loan book of a traditional bank, but lending is growing. Is that model changing?
A. Our goal has always been to be as safe as possible, and that’s why we consciously went into transactional business rather than lending business. We don’t want to go in too heavy. If you look at our loan-to-deposit ratios, they are around 4%. I don’t think we will ever exceed 10%, 15% or 20% because, I insist, the objective is to be as safe as possible and not go into risky business.
*
Storonsky began his career in finance as a derivatives trader at Lehman Brothers, witnessing the firm’s collapse in 2008 from his trading desk in London. He later moved to Credit Suisse. His education in traditional banking was not just about understanding how money is made in the markets, but also about seeing firsthand what can happen when a financial institution loses control of the risks it takes on. That experience helps explain some of the decisions he would make years later at Revolut.
Since its founding in 2015, the company has grown around businesses such as payments, cards, foreign exchange, subscription services and investing, activities that generate revenue without requiring the vast loan book that characterizes traditional banks.
The conventional banking model is built on taking deposits from customers and transforming part of that money into loans and mortgages, earning interest on the spread. Revolut has altered that equation: lending is just one source of revenue among many, and not even the main one.
That model has allowed the company to grow at remarkable speed. But breakneck growth also brings complications. The more customers, countries and products Revolut adds, the larger the machinery required to oversee what is happening inside the bank. The regulatory burden grows as well.
This is where one of the company’s central tensions emerges: how to preserve the speed and agility of a technology company while operating in one of the world’s most heavily regulated industries.
In 2025, the European Central Bank temporarily restricted the launch of new products while it reviewed whether Revolut’s internal controls were robust enough to keep pace with the rapid expansion of its business. In the United Kingdom, the company’s effort to secure a full banking license was also delayed for years as British regulators wanted to ensure that its control systems and measures to prevent financial crime were fit for an institution of its size.
Q. How do you ensure that your controls keep pace with the growth of the business and the speed of innovation?
A. We build our own internal tools dedicated to regulatory compliance and preventing financial crime. We have around 200 engineers building different products to ensure we meet regulatory compliance. And then we have another team of about 250 people — engineers, data scientists, product people — also dedicated to financial crime regulation. We are solving with technology, problems that legacy banks traditionally solved simply by hiring more people.
Q. Artificial intelligence is important for a technology company, but where will it make the difference at Revolut?
A. Practically in every area of the bank. We use AI in engineering, customer support, compliance, and it’s also used a lot in services related to preventing financial crime. I think every single area will be touched by AI, especially in digital businesses.
Q. Revolut has become one of Europe’s biggest home-grown tech companies. What is the main obstacle preventing Europe from producing more companies like it?
A. Fragmentation. If you look at the United States, they managed to create Silicon Valley by producing computers. Then many of those entrepreneurs became rich and began investing back in the tech ecosystem through startups. As a result, there was another wave of companies that grew and then another and another. An ecosystem was created. That’s what Europe lacks because Europe never had this initial tech ecosystem, nor people coming out of it and funding new startups. Hopefully, we will have more successful companies and their founders will continue investing in local companies. That is how we build an ecosystem similar to the United States.
Q. Revolut is no longer a startup. Is it still difficult to grow in Europe?
A. I would say it is challenging, yes. Generally, there is a lot of regulation and many regulators. It’s by design of the system itself. There are many countries and each country has its own regulators. When you add it all up, it is much more heavily regulated compared to the United States, which is a single market.
Q. Fifteen years ago, few people would have imagined a bank offering subscription plans, travel perks and lifestyle services. Is there room to reinvent the way loans and mortgages are offered?
A. I would say no, because lending is extremely regulated compared with lifestyle products. And I also think it’s a fairly commoditized product. Perhaps the last innovation in lending was seen with Klarna [with buy-now-pay-later], but it also ended up being heavily regulated. I think overall society and regulators prefer less risky products in lending rather than innovation. Because yes, innovation probably brings more efficiency, but it might bring more risks.
*
The numbers illustrate the scale of Revolut’s transformation. In 2019, the first year for which the company published results, the bank had around 10 million customers and was still losing money, ending the year with losses of nearly £100 million ($130 million). Six years later, the group posted a profit of £1.3 billion ($1.7 billion) and now has more than 80 million customers. Eleven business lines each generate more than £100 million in annual revenue, while only 21.6% of total income comes from interest. Cards, subscriptions, investing and foreign exchange continue to account for the bulk of the business.
In absolute terms, Revolut remains well behind Europe’s banking giants. Santander earned about $16.5 billion in 2025, while BBVA posted roughly $12.3 billion. But by profitability measures, Revolut already outperforms many of the continent’s largest lenders.
The company does not publish the standard banking profitability metrics, but calculations based on its accounts suggest a return on equity of roughly 35% in 2025, compared with 16.3% for Santander and 19.3% for BBVA, both among the most profitable major banks in Europe. The comparison is not entirely like-for-like, since listed banks disclose official profitability ratios and Revolut does not. Even so, it highlights the extent to which the company generates outsized returns with a capital structure that still differs markedly from that of traditional banking groups.
That growth has also driven up the price that investors are willing to pay for the company. Revolut remains privately held. Storonsky says a stock market listing is unlikely before 2028, but a secondary share sale carried out this summer valued the company at around $115 billion. The challenge now is to replicate that model on a global scale, building a worldwide bank on a single technological platform.
Q. To become a global bank, you also need to grow in Asia, a market where European and U.S. banks have struggled. What are your plans there?
A. Yes, certain markets in Asia are much more competitive, for example, China. But other markets are still underdeveloped, like Indonesia and Malaysia. So we have many plans to go into Asia. We are already live in Japan, we have just launched our pilot in India and we also have a bank license in Australia. We have big plans for Asia.
Q. Will there be any upcoming launches?
A. Yes, I think it will be New Zealand.
Q. Revolut has grown largely organically. But there are many fintechs with strong products that may never achieve sufficient scale. Are you considering making acquisitions?
A. Yes, we’re looking at multiple companies [Revolut recently received central bank approval to acquire Banco Cetelem in Argentina]. Maybe we can buy a company to get more customers. We see that as a marketing channel. Maybe we’ll also buy a company that has built a product that is difficult for us to develop. And other times we buy banks to get a license. So it can go in three directions. Traditionally, in the first two cases, we run an analysis and find out that it is cheaper for us to build internally than to buy. And in many cases it is also cheaper to acquire customers directly with our product than to buy a platform with many users and then try to migrate them to use Revolut.
Q. In what cases does it make sense to buy a bank rather than apply for a license in the country?
A. In some markets, it is faster to buy a license because there are countries where the process is very long. Some even prohibit you from getting a license unless you buy a bank. One example is Turkey. There, they don’t give licenses anymore because they want to consolidate the banking industry. And as a new player, you are forced to buy a bank. There are similar cases in other markets.
*
Storonsky’s management style is built around minimizing layers of hierarchy. He sets goals, gives teams autonomy and measures results. Once again, the logic resembles that of a technology company more than that of a large financial institution.
Product development, too, has something of a laboratory mindset. Revolut tests multiple ideas simultaneously, assigns relatively small teams to each and then allocates more resources to those that show signs of success. Storonsky has acknowledged that even he cannot always predict in advance which bets will pay off. The advantage is not so much in being right every time as in the ability to test, discard and rapidly scale what works.
But such a system is easier to sustain in a startup than in a company entrusted with the savings of tens of millions of people and operating under the scrutiny of regulators across numerous jurisdictions. Here lies another paradox of Revolut’s next phase: growing large enough to become one of the world’s leading banks without turning into the kind of slow, bureaucratic organization it was created to challenge.
Q. Your management style is very different from that of traditional bankers. But as Revolut has grown larger and become more heavily regulated, have you had to change the way you lead the company?
A. Obviously, we had to adjust, but at our core, we are still the same. We want to innovate and bring value to customers. But at the same time, there are borders and we need to remain compliant with a lot of regulation. We innovate within these borders of regulation. And it is possible to be fast, innovative, creative and comply with regulation.
Q. You founded Revolut with a clear vision of what you wanted to build, but the organization has grown enormously and your team has expanded with it. What still depends heavily on you?
A. Quite a lot, quite a lot of things. But I suppose that happens with any CEO. It’s their job to identify major problems, major bottlenecks, even if they are not very visible. They can be hidden. It’s their job to ensure that each person who reports directly to them delivers results and, from there, that the whole organization meets its objectives.
Q. Revolut was born as a fully digital bank, but we’re now seeing offices like this one and even ATMs in Spain. Do you expect to adopt other features of traditional banking and reinvent them in your own way?
A. Yes, because in the banking industry, trust and reputation are extremely important. We spend a lot of money to ensure we are not only safe from a technological perspective but also from a branding perspective. And what we have discovered is that the physical world generates additional trust and reputation for banks. That’s why we are entering the physical world. If you are not physically present somewhere, people will trust you less as a bank compared to legacy players.
Q. It feels as though the roles are reversing: banks are copying parts of Revolut’s business model, while Revolut is adopting elements of traditional banking.
A. Yes, because it’s more about marketing. You can spend money on digital advertising on Google, Facebook, Instagram and generate impressions. Or you can open an office and have people walking past. And if there are one, two or three million people passing by, that might pay off. You need to calculate the cost per impression digitally. And in the physical world it might be cheaper. And if it’s cheaper, then it makes sense to do it.
*
The paradox captures where Revolut finds itself today. For years, it forced traditional banks to move closer to its digital-first model. Now, as it seeks to compete with the world’s largest financial institutions, it is Revolut that is adopting some of the hallmarks of conventional banking.
The challenge is no longer to prove that banking can be done differently. It is to see how far the company can grow without losing the qualities that enabled it to challenge the banking establishment.
Q. What would need to happen in the coming years for you to be able to say that Revolut has won, that it has truly become a global bank and is competing with the likes of JPMorgan, Santander and BNP Paribas?
A. I hope I can say we have won if we are larger than JPMorgan [laughs]. I’m not sure if it’s possible in 15 years’ time, but we’ll see.
Sign up for our weekly newsletter to get more English-language news coverage from EL PAÍS USA Edition