Ask anyone in Nigeria what stablecoins are for, and you’ll hear about people. Freelancers cash out dollars from foreign clients. People save in USDT. Traders move money between apps. That picture is accurate. It is also the smaller half of the story.
At AfriFlux we map Nigerian exchanges, offramps, neobanks, and payment companies wallet by wallet.
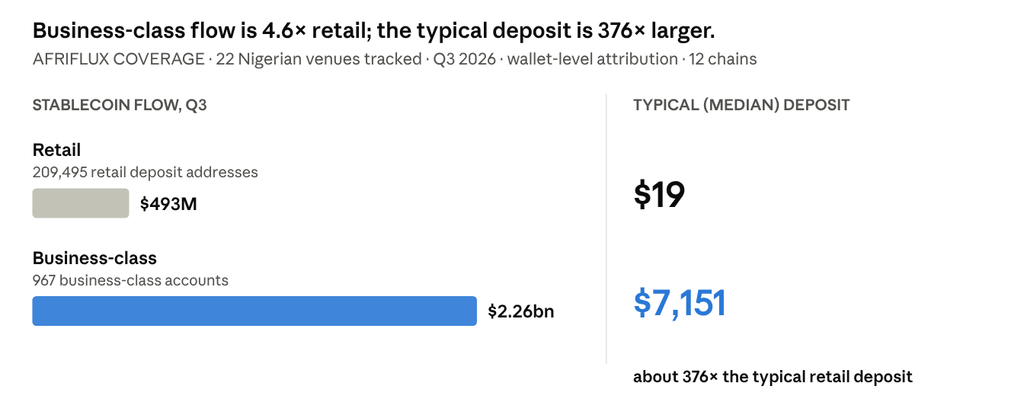
Across the 22 venues we track, 967 business-class accounts moved $2.26 billion in stablecoins between July and September. Over the same three months, 209,495 retail deposit addresses moved $493 million. Fewer than half a percent of the accounts carried 81% of the money we observed.
That is not an estimate of Nigeria’s total stablecoin market; it is what we can see onchain. But within that view, the retail story everyone tells is the minority one. Most of the money is business money, and increasingly, it is businesses paying each other.
A $19 market and a $7,151 market
The quickest way to see the split is a single deposit. The typical retail deposit in our Q3 data was $19. The typical business-class deposit was $7,151, about 376 times larger.
The rhythm is different too. A retail address made about nine deposits in the quarter; a business-class account made about sixty. Two in three retail addresses made at least two deposits; four in five business-class accounts did. Retail is many people making small deposits now and then. Business is a small number of accounts moving large sums constantly.
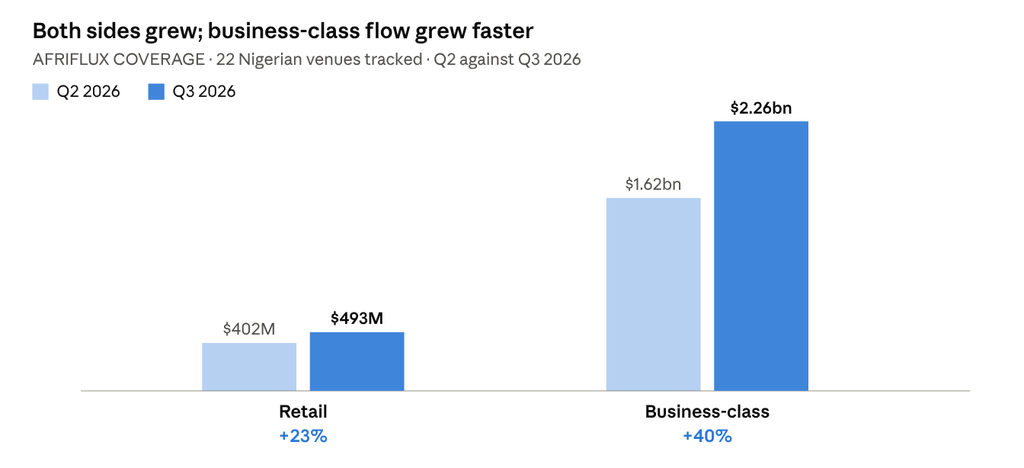
Retail deposits rose 23% in the second quarter, from $402 million to $493 million, as about 59,000 more addresses started depositing. Business-class flow grew faster, by 40%, from $1.62 billion to $2.26 billion.
Some venues, like Grey, Onboard, Raenest, and Accrue, serve both individuals and businesses through the same accounts. So, on-chain, the two can’t be clearly separated. We count their $35.6 million on its own rather than force it into either side.
We classify business activity by looking at on-chain behavior. This means we check the deposit size. We also look at confirmed company-to-company settlements. “Business-class” does not mean we have identified the legal entity behind every account.
A few big players carry the business side
Business money is concentrated. Obiex, an exchange where business clients use dedicated deposit addresses, saw $1.77 billion of business-class flow in Q3. This is an increase from $1.46 billion.
Flutterwave’s business-account flow rose from $62 million in the second quarter to $305 million in the third. Quidax’s business-class flow nearly doubled, from $103 million to $190 million.
Flutterwave shows how lumpy this is. It had 186 business-class accounts in Q3; one carried 76% of the money and five carried almost all of it. Across all business-class flow, the top 1% of accounts moved a third of the value, up from under a quarter in Q2.
That is why business flow can swing a headline number in a single quarter while retail moves steadily.
The part nobody announces: companies paying each other
The most interesting thing in the data is not size but shape. Nigerian fintechs and exchanges are settling with each other, wallet to wallet, every week. However, this activity isn’t visible in press releases or self-reported volumes.
We only name a relationship when the wallets show it. Payments go from wallets a company is known to control. These include its master and settlement wallets. Then, they move into the receiving company’s wallets or a specific deposit address. These payments must repeat over time. Five relationships met that bar in Q3:
- Spenda to Quidax: $40.9 million in Q3. Master wallet to master wallet ($33.2 million), plus a Quidax deposit address that only Spenda funds ($7.7 million). Payments ran in all 27 weeks from April to September, and almost all of Spenda’s payments to other companies go to Quidax.
- Quidax to Obiex: $22.3 million. Quidax pays into Obiex business accounts every week, mostly into one deposit address that takes 82% of its inflow from Quidax.
- Jeroid to Obiex: $4.3 million in Q3, paid every week, with a typical payment of $51,000.
- Grey to Quidax: $2.8 million, master wallet to master wallet, mostly on Solana, in 26 of 27 weeks.
- Azza to Daya Pro: ₦0.46 billion in cNGN since 24 August, the newest link. Azza is itself fed by solvers on the HyperFX exchange protocol, which sent it ₦0.38 billion in Q3. So naira stablecoin moves from an FX protocol, through one venue, into another.
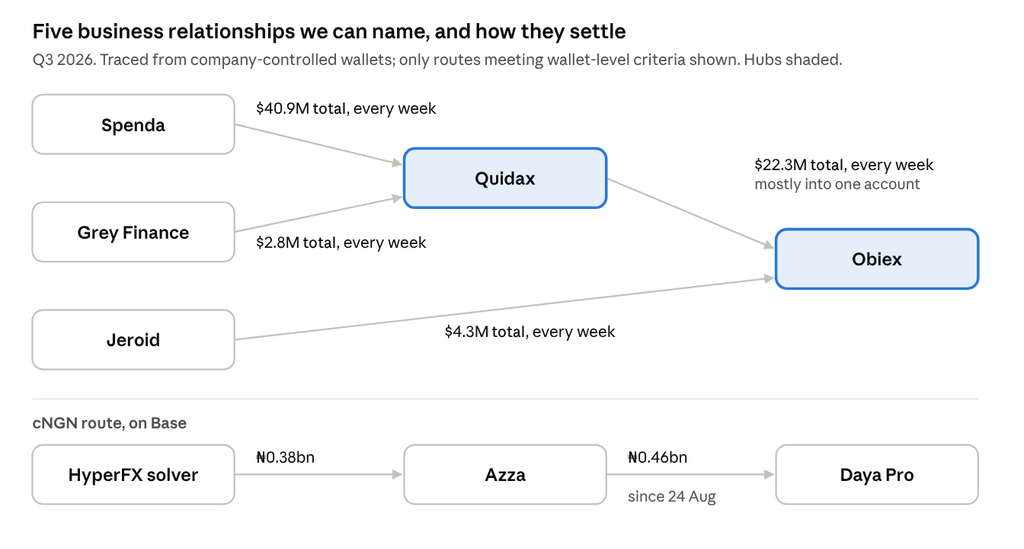
Put together, two venues act as hubs. Obiex receives business flow from nine of the venues we track, Quidax from six. Spenda’s company payments go almost entirely to Quidax, and Quidax settles with Obiex, linking all three companies onchain every week.
There is an honest limit here. These named relationships add up to about $70 million, roughly 3% of business-class flow. The other 97% is real, measured money from counterparties we cannot identify on-chain, and we leave it unnamed rather than guess.
Retail is wider, not richer
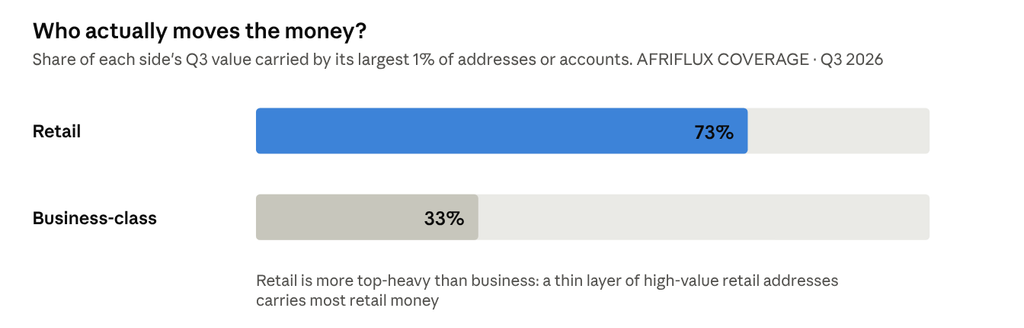
Retail looks nothing like the business side, and it is less evenly spread than the word “retail” suggests. The typical retail address deposited $49 in total over the quarter, yet the largest 1% of retail addresses carried 73% of retail value.
That is more concentrated than the business side, where the top 1% carried 33%. Two hundred thousand addresses, mostly small, with a thin layer of high-value users on top.
Retail also grew by getting broader, not richer. About 59,000 more addresses deposited than in Q2, while the typical deposit fell from $22 to $19. The new money came from more people making smaller payments, not from existing users depositing more.
That is the structural difference in one line: business activity grows when a few accounts move more; retail grows when more people arrive.
Why this matters
If you think of Nigerian stablecoins as a retail story, you will look for demand, risk, and opportunity in the wrong place. In the part of the market we can see, most of the money is business flow. Exchanges, offramps, and payment companies move dollars on a weekly schedule.
That changes the questions worth asking. Who depends on these rails, and how heavily? How concentrated is that dependence, when one account can carry three quarters of a venue’s business flow? And what happens to the wider system when one large counterparty changes its behaviour?
None of this makes retail less important. Retail is where the new users are: 59,000 more addresses in a single quarter. But most of the dollars are business money, and the part we can trace shows companies paying each other. That is the side of the market that gets the least attention.
What the chain can’t tell us
Everything here is read from public blockchains, which makes it verifiable but also bounded. An address is not a person: one person can hold several deposit addresses, and one business-class account can serve many customers.
Some deposits can be misleading. At Onboard, most deposits on the Base network are actually payments into US-dollar virtual accounts. They aren’t users topping up. And the chain does not show internal ledgers, fiat settlement or customer identity.
What it does show, precisely, is who paid whom, when and how often. That is enough to see that Nigeria’s stablecoin economy is not one market. It is two running on the same rails, and the interesting part is where they meet.
Mukthar Yahaya is co-founder of AfriFlux, which maps African exchanges, offramps, neobanks and payment companies wallet by wallet.
Methodology: AfriFlux tracked USDT and USDC deposits across 22 Nigerian venues and 12 blockchains from July 1 to September 30, 2026. Business and retail activity were classified using onchain behaviour and verified company-to-company transfers.
Figures reflect AfriFlux’s observed coverage, not Nigeria’s total stablecoin market. Onchain data cannot reveal internal ledgers, offchain settlements or unattributed wallets.