
Australian startups raised $1.31 billion in the September quarter, excluding the failed ASX aspirant Firmus, up nearly 80% on the same period in 2025.
But fewer rounds were announced, and another handful of big deals did most of the heavy lifting in what was a record quarter across six years of analysis by Cut Through Venture .
The Cut Through Venture Q3 report puts the comparable quarterly figure from 12 months earlier at $730 million, after removing $330 million Firmus raise from the 2025 quarter too. It is also a long way from the boom suggested by the headline record of $4.2 billion, which includes the $2.85 billion Firmus raise in August.
CTV’s latest historical series shows 92 announced rounds last quarter, compared to 123 a year earlier, down 25%. Funding, excluding Firmus, was essentially flat on Q2.
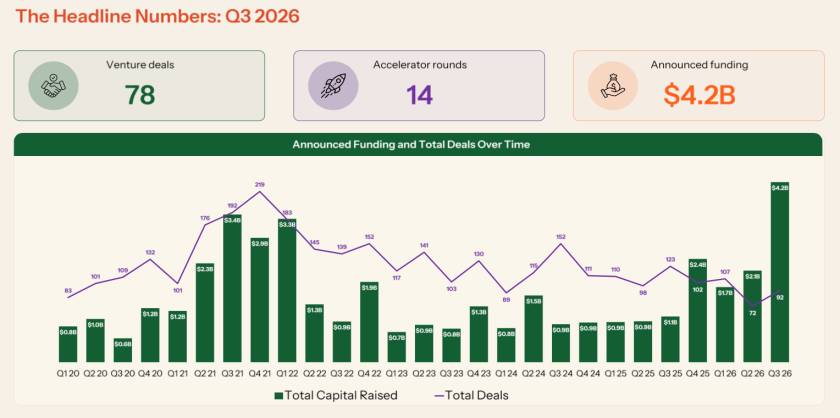
“More companies secured a cheque, but the headline jump in dollars should not be mistaken for a broad-based funding boom,” CTV said in its accompanying commentary.
And the concentration of investment stands out.
Get the best of Startup Daily straight to your inbox
Want to know the latest in startup news? Subscribe to our daily news and analysis coverage on what’s happening to ANZ startups, investors and the broader ecosystem. And best of all, it's FREE!
By continuing, you agree to our Terms & Conditions and Privacy Policy.
Queensland-US cancer treatment developer AdvanCell’s $452 million Series D gobbled up 35% of the remaining capital – and most of it came from offshore. A year ago, the largest non-Firmus Q3 round was Morse Micro’s $88 million Series C.
Without AdvanCell, this quarter’s tally falls to roughly $858 million, just 18% above last year’s total, sans Firmus.
Rebuilding the quarter’s top 10 without Firmus put Farmbot’s $22 million Series B into 10th place. And those 10 startups still account for about $1.04bn, or 79% of remaining funding.
Rounds below $10m raised $162m between them, broadly matching 2025’s quarterly average.
The other big raises were expat insurtech Cover Genius ($143m), clinical AI startup Heidi’s Series C ($140m) and energy retailer Amber Electric’s Series E ($79m). Fintechs Constantinople pocketed $62.5m and pay.com.au $39 million – although the rewards platform reannounced that figure for the US market in August, having raised the first $20m in April, then topped it up another $20m in June
Others making the top 10 were HEO’s Series B ($37m), Gridsight ($36.3m), Jet Zero ($30m) and Farmbot ($22m), suggesting that investors not slinging cash at AI focused on specialist tech and industry expertise for expensive problems in healthcare, finance, energy and defence.
What’s also noticeable alongside the growing presence of international funding, is that Australian startups are shifting offshore in terms of corporate control alongside their customer base. Farmbot’s US-led financing sat amid a move to a Delaware parent company and global HQ in Texas.
Meanwhile, AI’s influence stretched beyond data centres.
AI applications attracted $675m, roughly half the non-Firmus capital. Nearly two-thirds (65%) of all announced rounds involved AI-first or AI-enabled companies.
And the perception is reality: 81% of surveyed investors said AI-first startups commanded higher valuations than comparable non-AI businesses, including 42% reporting significantly higher prices.
“This is an AI premium, not a wholesale repricing of the market,” CTV said.
Specialist software attracted 94% of software funding, and no surveyed investor preferred general-purpose software over products built for particular industries.
Another sharp year-on-year change was in investor-reported weighted valuation averages for Series C and later businesses, which rose from $100m to $225m. Those are survey estimates, rather than measured transaction prices.
Women dudded again
But one consistency in the data is that recovery once again bypassed many female founders.
Female and mixed-founder teams raised $114m, down 14% from $133m a year earlier. Ex-Firmus in both corresponding quarters, their share of capital fell from about 18% to 9%, despite accounting for 32% of this quarter’s deals.
CTV said “participation improved faster than access to large cheques”.
So it’s not a pipeline problem. Women are on the field – they just get smaller slices of the investment pie, generally, in earlier stage startups.
Meanwhile, its a tough time to be an VC LP if you were planning to treat yourself to a gin palace on Sydney Harbour this summer: 65% of funds said their backers viewed venture less favourably than a year ago, and 71% had recorded no fund exits in 2026.
At least they didn’t spend their surplus cash on Firmus shares.