A service that lets consumers cancel unused credit cards in one place has processed only about 24,000 requests in roughly two years, according to data released on the 21st. With dormant cards surpassing 17 million, critics say the government needs both to raise usage of the bulk cancellation service and to revise rules on personal data that stays on file for years.
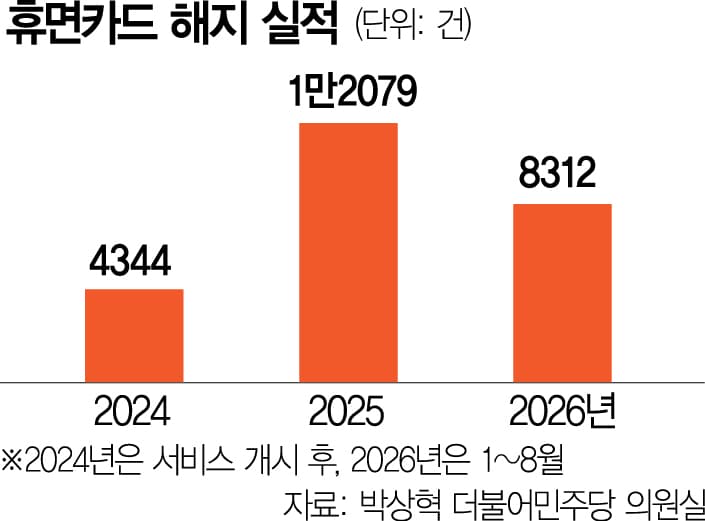
Data obtained from the Financial Supervisory Service by Rep. Park Sang-hyuk of the Democratic Party of Korea showed that 24,735 dormant cards were canceled through Accountinfo between Sept. 26, 2024, and the end of August this year. The service handled 4,344 cancellations in its first year, followed by 12,079 last year and 8,312 in the first eight months of this year. Cancellations made through card companies' apps, websites or call centers are not included in the tally.
Over the same period, consumers checked their dormant cards 948,713 times. Cancellations amounted to 2.6% of those inquiries. Another 7,410 requests were filed to keep cards active. Monthly cancellations rose only slightly, from about 1,007 last year to about 1,039 this year.
Accountinfo is an integrated account management service that lets users review bank account and card information held across multiple financial companies. Financial regulators added the bulk cancellation function in September 2024 to spare consumers from filing separate requests with each card issuer. Previously, users who found an unused card on Accountinfo still had to contact the issuer directly to cancel it or resume use.
A dormant card is a credit card that has gone unused for at least a year since its last transaction. The number of such cards has continued to grow even after the one-stop cancellation channel opened. According to the Credit Finance Association, the eight specialized card companies held 17.671 million dormant cards at the end of June, up 2.313 million, or 15.1%, from the end of September 2024, when the service launched. The figure also rose by 428,000 from the end of last year.
When long-unused cards remain on the books, the personal data tied to them can also stay stored. Dormant cards whose contracts remain in force, even without any transactions, do not fall under rules requiring data to be deleted or stored separately once a customer relationship ends.
The Credit Information Use and Protection Act generally requires personal credit information to be deleted within five years of the end of a transaction. Essential records that must be retained after that point have to be managed separately from data on active customers. Those end-of-relationship standards, however, do not apply to dormant cards whose contracts are still alive.
That has prompted calls for separate storage rules covering data on long-inactive members. Card issuers should also disclose which categories of personal data they hold and how long they plan to keep it when notifying customers that a card has turned dormant, allowing consumers to decide whether to keep the contract, the argument goes.
"It is a problem that personal information is stored for long periods simply because a contract stays in force even when the card is not used," Park said. "The rules on when a transaction ends and when personal information must be deleted should be reviewed so that there are no blind spots in data protection."