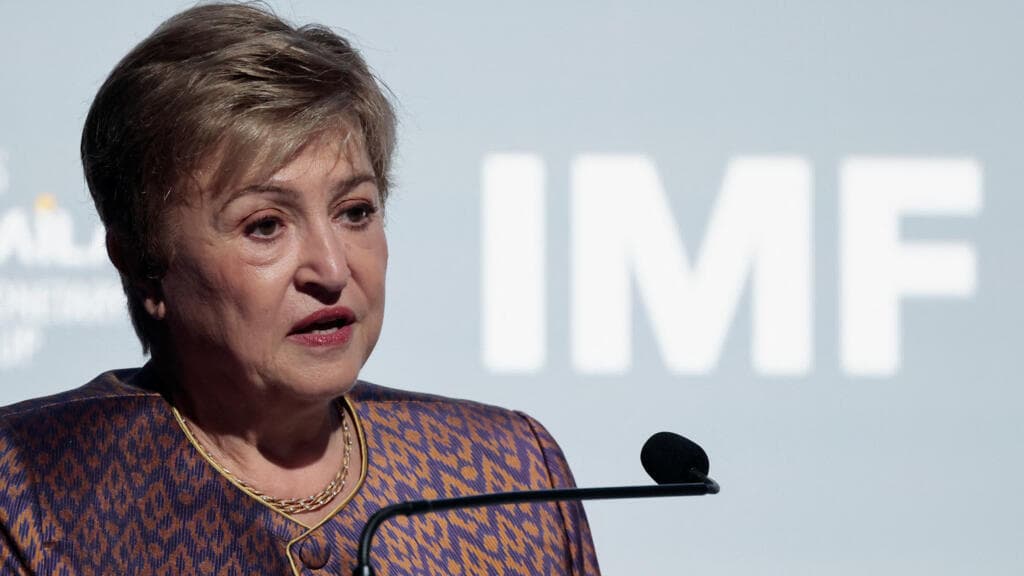
France will need time to bring its public finances under control and fully restore investor confidence, the head of the International Monetary Fund warned on Wednesday, as rising borrowing costs put renewed pressure on the eurozone’s second-biggest economy.
Issued on: Modified:
"France is currently aiming to get a budget that would put deficit and debt on a downward trajectory," IMF managing director Kristalina Georgieva said, speaking at the IMF and World Bank annual meetings in Bangkok.
However, she added that it would "take time before it could come down to levels that are providing confidence – full confidence – to people and to the investor community".
France is not alone in facing higher borrowing costs, but has attracted scrutiny in recent weeks as its fiscal difficulties collide with a fragmented parliament, mounting public anger over spending cuts – as demonstrated in recent weeks by protesting school pupils – and an impending presidential election.
The IMF has previously warned that political fragmentation has limited the government’s ability to deliver its planned fiscal adjustment and that uncertainty ahead of the 2027 election could revive market pressure.
To display this content from X (Twitter), you must enable advertisement tracking and audience measurement.
France faces record €340bn borrowing test as government braces for 2027 budget
‘No debt snowball’
The government’s draft budget aims to reduce the public deficit to 5 percent of GDP in 2027. But securing parliamentary approval remains far from certain, while the government lacks a stable majority in the National Assembly.
Opposition parties on both the left and the right have attacked measures including tighter healthcare spending and changes to pension indexation.
The government is seeking to make around €43 billion of spending cuts alongside other measures next year, while also trying to sharply reduce the social security deficit.
The Socialist Party, which helped enable this year’s budget to pass, has criticised the new proposals, while Marine Le Pen’s far-right National Rally also opposes parts of the package.
Economy Minister Roland Lescure sought on Tuesday to push back against the more alarming assessments of France’s position, insisting the country had not yet entered a self-perpetuating debt crisis.
He acknowledged that government borrowing costs had risen sharply but rejected the idea that France was trapped in a debt “snowball effect” – in which higher interest payments lead inexorably to more borrowing and still greater pressure.
Lescure urged opposition parties to allow the 2027 budget through parliament, arguing that France needed to demonstrate to investors that it was capable of changing course.
France cuts growth forecast again as economic uncertainty weighs heavy
'The solution lies at home'
This political uncertainty is increasingly being reflected in the bond market. French government bonds have been among those hardest hit by the recent global sell-off, with investors demanding higher returns to lend to a state whose spending continues to substantially exceed its revenues.
Public Accounts Minister David Amiel warned this week that parliament could not afford to delay, pointing to the recent surge in interest rates.
The Brussels-based Bruegel think tank has argued that the pressure now seen in bond markets reflects economic problems that have accumulated over years.
Its analysts suggest France may face further market pressure before its political system becomes willing to accept reforms repeatedly postponed in the past.
France seeks €4bn savings to cover cost of Middle East war
European Central Bank (ECB) President Christine Lagarde, a former head of the IMF and former French economy minister, on Wednesday said that France should solve its own debt woes through fiscal policy consolidation – effectively playing down speculation about an ECB intervention in the bond market.
“There are particular circumstances that lead to some countries being more affected, France being a case in point,” she told a CNN event on the sidelines of the IMF/World Bank meetings. “And for that one, the primary and first solution lies at home in France. And it has to do with fiscal policies.”
France's challenges come in a difficult context for the wider eurozone, with inflation pushed higher by rising energy prices linked to the Iran war, prompting the ECB to raise interest rates twice in the past four months. Another increase is expected in December.
Lagarde nevertheless struck a measured note on growth, describing the IMF’s forecast of 1.1 percent expansion in the eurozone this year as “not brilliant” but “not a bad outcome”.
(with newswires)