Every $10 (₦13,329.7) borrowed from OPay generated $2.55 (₦3,399.07) in loan-financing revenue in H1 2026. The figure includes late-payment penalties, not just interest, and offers a glimpse into the revenue lenders need to cover the risk of borrower defaults.
The fintech generated $236.12 million from $927.6 million in loans originated in Nigeria, according to its public offering prospectus. But OPay set aside $118.36 million for expected credit losses, equivalent to $1.28 (₦1,706.20) for every $10 lent. After provisions, roughly $1.27 (₦1,692.87) remained from every $10 lent.
Loan-financing revenue was equivalent to 25.5% of originations, against the Central Bank of Nigeria’s 26.5% benchmark interest rate during the period. OPay’s figure is not the interest rate charged to individual borrowers, as revenue includes accrued interest and penalties for late repayments.
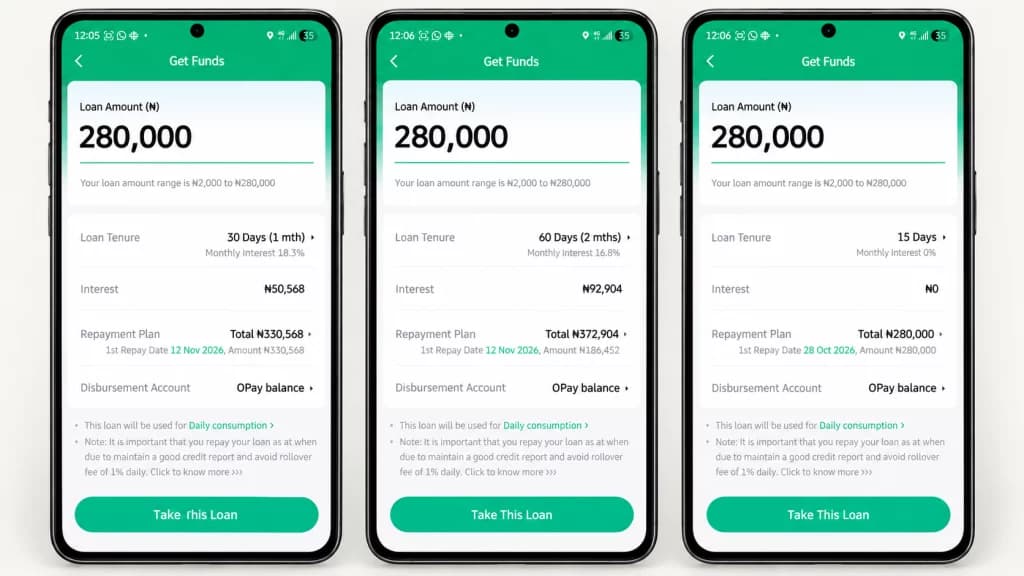
On a ₦280,000 ($210.06) loan through the OPay app, TechCabal was offered 0% interest for a 15-day repayment period, 18.3% for 30 days, and 16.8% for 60 days. The rates apply to the entire repayment period, not annually.
The fintech’s figure offers a glimpse into the economics of digital credit in Nigeria’s consumer lending market, estimated to be worth $2.1 billion. Lenders must price loans to cover defaults, funding and operating costs, with borrowers who repay on time potentially bearing part of the cost of lending to those who do not.
The company classifies loans that are 90 days past due as non-performing and charges them off at 120 days past due. Recoveries on previously written-off loans reduce credit-loss expense.
Nigeria’s conventional banking framework classifies loans as non-performing after 90 days past due, doubtful after 180 days, and as losses after 360 days. OPay reported an NPL ratio of 4.3% as of June 30, 2026, compared with 8.03% for the banking industry, above the prudential threshold of 5%.
But OPay’s 120-day charge-off policy complicates comparisons with banks that classify loans as losses after 360 days. Loans OPay writes off could remain on a bank’s books for another eight months, potentially making OPay’s NPL ratio appear lower. The company does not disclose the value of loans charged off between those thresholds, making it impossible to estimate what its ratio would be under a 360-day timeline.
The economics of OPay’s lending
Lending is OPay’s largest revenue stream, generating 55.29% more revenue than its next-largest business. But expected credit losses are growing faster than lending revenue.
In H1 2026, it originated $927.6 million in loans, more than three times the $305.1 million it originated a year earlier. Loan-financing revenue grew 167.9% year-on-year to $236.12 million, while provisions for expected credit losses increased by 210.3%.
Provisions consumed 50.2% of loan-financing revenue in H1 2026, up from 41.0% a year earlier. For every $10 OPay earned from lending, it set aside $5.02 to cover expected credit losses, leaving less revenue to cover other costs. The fintech is betting that an increasing shift towards merchant loans will reduce its credit risk profile over time.
The Hidden Cost of Digital Lending
Explore how expected credit-loss provisions consume a significant portion of digital lending revenue.
Hypothetical Ratio Adjustments
On a hypothetical $10.00 loan origination, the illustrative lending revenue is $2.55. OPay records $1.28 in expected credit-loss provisions, leaving $1.27 in revenue remaining before funding, operating, taxes, and other costs.
Methodology: These calculations apply precise ratios derived from aggregate financial reporting ($236.12M loan-financing revenue and $118.355M expected credit-loss provisions against $927.6M in originations) to a hypothetical transaction amount. They do not predict the pricing, performance, or profitability of any specific individual loan.
Source: OPay F-1 SEC Registration Statement (H1 2026).
OPay sets interest rates based on borrowers’ profiles and risk assessments. Its loan-financing revenue comprises interest accrued over the loan term using the effective interest method, alongside penalties for late instalment payments. Provisions, however, are estimates of expected losses, not the final amount the company will fail to recover. Actual losses will depend on defaults, subsequent recoveries, and changes in those estimates.
OPay has a substantial pool of cash to fund its lending. As of June 30, 2026, it held $918.7 million in cash, cash equivalents, and short-term investments. “As of June 30, 2026, we did not have credit facilities provided by financial institutions,” the company said in its prospectus.
OPay expects the proceeds from its public offering and concurrent private placement, together with existing cash and anticipated operating cash flows, to cover its cash needs for the next 12 months.
OPay’s art of lending
OPay’s loans typically last around 100 days. The company uses transaction data to assess borrowers who may lack conventional credit records. In 2025, fintech unicorn Moniepoint disbursed ₦1 trillion ($750.20 million) in loans using transaction data.
OPay said its monthly active users made an average of 209 wallet payments a month. It has leveraged more than 200 billion credit and financial data points and nearly 50 billion behavioural data points to assess borrowers, combining transaction histories with credit records, income data and third-party sources.
The company runs more than 5,000 machine-learning models and variants to assess creditworthiness, set loan limits, price loans and monitor delinquency. Its models draw on device intelligence, transaction patterns, social graphs and user-consented financial SMS data. AI tools also support collections: WhatsApp reminders improved recovery rates by 3.5% in Indonesia, with rollout to Nigeria underway. OPay warns that poor data, changing borrower behaviour, fraud and model drift can weaken its predictions and increase credit losses.
The strategy is scaling. OPay originated $1.56 billion in loans in Nigeria in the 12 months to June 30, 2026, and quarterly unique borrowers reached 6.7 million in Q2 2026, more than seven times the number in Q1 2024.
Loan financing accounted for 50.55% of OPay’s $467.06 million in total income in H1 2026. The company also reported $90.87 million in operating income.
OPay’s lending business remains small relative to established Nigerian banks. Guaranty Trust Holding Company (GTCO), for instance, reported a loan book of ₦3.14 trillion ($2.36 billion) in 2025. The figures are not directly comparable: the two businesses operate at different scales, and their lending models differ
OPay is also expanding into new lending products. It launched a buy now, pay later (BNPL) product in September 2025 and disbursed $99 million in merchant loans and $5 million through the BNPL product. Merchant lending could help OPay manage credit risk because regular business transactions provide observable signals of repayment capacity.
But as OPay expands its lending business, it must also contend with the marketing tactics used to attract and recover loans. Selling and marketing expenses rose 104.67% to $78.68 million in H1 2026. A TechCabal report in April 2026 identified OPay, EaseMoni, and OKash (both tied to OPay) as major sources of complaints about harassment from digital lenders, including persistent calls.
OPay reported a customer acquisition cost (CAC) of $1.90 in H1 2026, with average monthly revenue per user at $1.70 in Q2 2026.
In its prospectus, OPay says it limits marketing contact to twice a week and offers distressed borrowers counselling, payment deferrals and penalty or interest waivers.
True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks.
Get 20% off Early Bird tickets for a limited time.