Nigerian insurance companies are facing a new phase of regulatory scrutiny as the National Insurance Commission (NAICOM) prepares to introduce a risk-based capital (RBC) framework that will link capital requirements to the risks operators assume. This therefore raises the pressure on insurers to improve underwriting discipline, pricing accuracy and claims-paying capacity.
The framework, which is expected to be concluded soon, will require insurers to assess whether their capital is adequate to support the risks they underwrite, following the completion of the industry’s recapitalisation exercise on July 31, 2026.
The shift marks a move from capital adequacy measured largely against prescribed minimum thresholds to a more risk-sensitive regime in which the nature and scale of an insurer’s exposures will determine the capital it needs to remain financially sound.
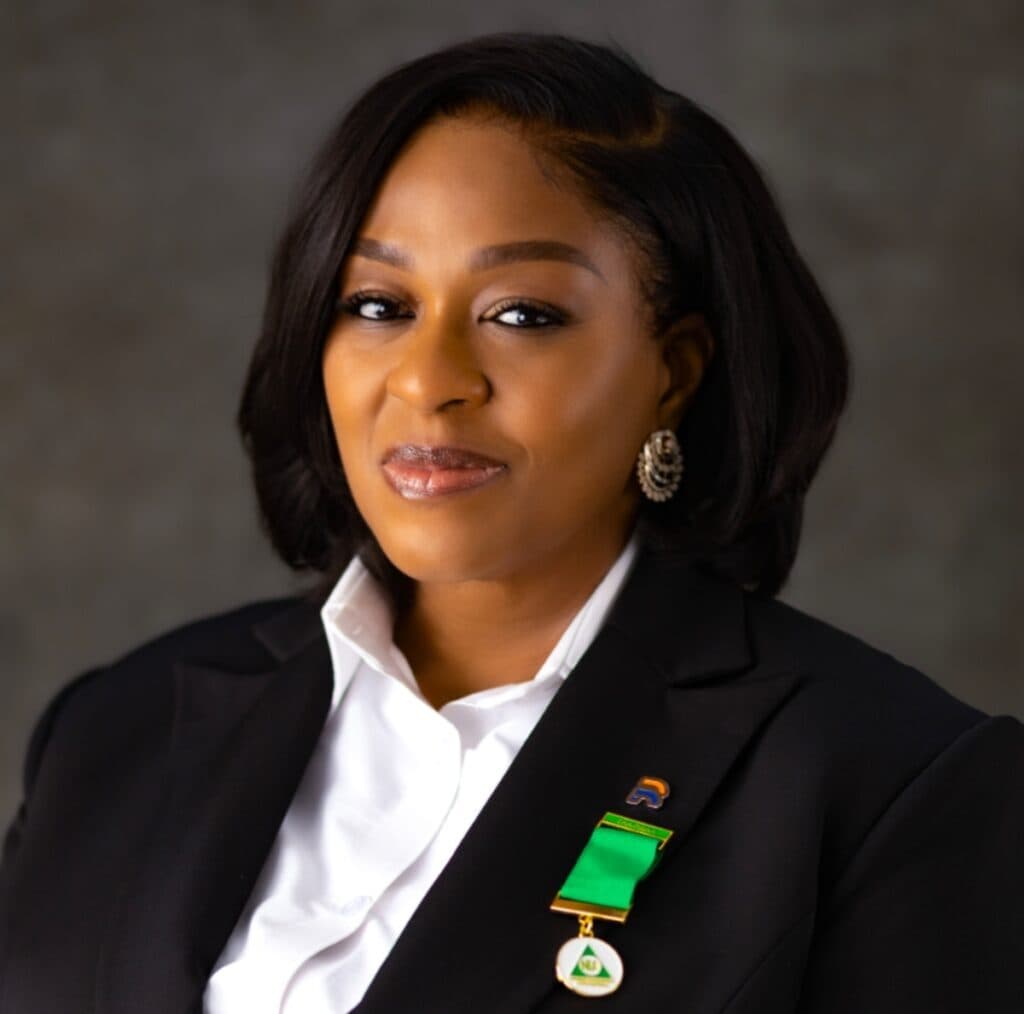
Ebelechukwu Nwachukwu, outgoing chairman of the Communications and Stakeholders Engagement Sub-Committee of the Insurers’ Committee, disclosed this during a virtual press briefing after the committee’s last meeting.
She said Commissioner for Insurance, Olusegun Ayo Omosehin, informed industry executives that NAICOM had appointed EY, the global audit firm to support the development of the framework and guide its implementation.
According to Nwachukwu, EY delivered a high-level presentation to chief executives at the meeting, while further engagements would be organised to improve operators’ understanding. A draft framework will also be circulated to industry stakeholders for review before its adoption by the commission, Nwachukwu said..
The proposed framework is expected to reshape how insurers assess risks, determine premiums, allocate capital and structure their reinsurance programmes. For operators, the implication is that stronger balance sheets following recapitalisation must now be matched by the capacity to identify, price and manage risks appropriately.
Under the new regime, insurers will need to demonstrate that their underwriting exposures are supported by adequate capital, rather than rely solely on meeting minimum capital requirements. Companies with concentrated exposures, inadequate pricing or weak risk management could face greater pressure to strengthen their capital positions or reduce the risks they accept.
Nwachukwu said NAICOM had encouraged operators to begin preparing for the transition by conducting internal assessments of their underwriting capacity and reviewing their underwriting manuals, reserving policies, reinsurance arrangements and internal controls.
These measures will be critical as insurers prepare for the next phase of regulation, particularly in determining whether premiums adequately reflect the probability and potential cost of claims, whether technical reserves are sufficient to meet future obligations and whether reinsurance arrangements provide effective protection against large losses.
For the industry, the challenge will be to move beyond the drive to raise capital and demonstrate that the additional financial resources can support sustainable underwriting growth without exposing policyholders to avoidable claims delays or insurers to excessive losses.
Omosehin, according to Nwachukwu, congratulated the 50 insurance companies that emerged from the recapitalisation exercise and urged them to translate their strengthened capital positions into improved underwriting capacity, particularly as the reinsurance renewal season approaches.
The commissioner also called for better claims settlement, wider insurance penetration and disciplined investment practices, while urging company boards to take a more active interest in the activities of their managing directors.
Recapitalisation has provided qualifying insurers with stronger capital bases, but capital alone does not guarantee profitability or financial resilience. Poor risk selection, underpricing, inadequate reserving and excessive concentration in particular sectors can still weaken an insurer’s balance sheet, even where minimum capital requirements have been met.
A risk-based framework is intended to make these vulnerabilities more visible by aligning capital requirements with the risks an insurer carries. Its effectiveness, however, will depend on the quality of the rules, the reliability of operators’ risk data, the strength of actuarial assessments and NAICOM’s capacity to supervise compliance consistently.
Insurers will therefore need to strengthen their internal risk management systems and improve the quality of information used to make underwriting decisions. Pricing must reflect expected claims costs and associated expenses, while underwriting limits should be aligned with available capital, reinsurance protection and the company’s ability to absorb unexpected losses.
The transition could also influence competition across the market. Operators with stronger risk assessment capabilities, reliable data and sound reinsurance arrangements may be better positioned to underwrite complex commercial and industrial risks. Others may need to revise their business models, improve controls or become more selective about the risks they accept.
Nwachukwu said the commissioner had also encouraged insurers to develop health insurance products and build capacity to cover emerging risks, including climate-related and cyber risks.
These segments offer opportunities for market expansion but require specialised underwriting expertise, reliable data and pricing models capable of capturing risks that may be difficult to quantify. As exposure to cyber incidents and climate-related losses grows, insurers will need to balance the need to expand coverage with the financial implications of taking on unfamiliar risks.
The RBC initiative is also unfolding alongside NAICOM’s efforts to deepen digitalisation and strengthen actuarial capacity in the industry.
Nwachukwu disclosed that discussions were ongoing on the establishment of a Joint Actuarial Development Fund to support the development of actuarial expertise in Nigeria. NAICOM has committed to supporting the initiative, while operators are reviewing the funding formula and exploring assistance from external organisations.
The proposed fund is expected to support universities and strengthen the supply of actuarial professionals whose expertise will be important in risk modelling, pricing, reserving and capital assessment under the new framework.
NAICOM is also accelerating the digitalisation of its operations and services, with insurers urged to adopt digital solutions to improve engagement with the regulator. The commission has published its Service Charter on its website as part of the initiative.
For insurers, the immediate priority is to use the transition period to identify weaknesses in their underwriting and risk management processes before the framework takes effect. This includes testing capital adequacy under adverse scenarios, reviewing exposure limits, strengthening claims data and ensuring that reinsurance programmes provide sufficient protection against severe losses.
Ultimately, the success of risk-based capital will depend not only on the amount of capital insurers hold but also on how effectively they deploy it, manage their exposures and meet their obligations to policyholders.
Related News

Modestus Anaesoronye is a leading Nigerian financial journalist with over two decades of experience reporting on the insurance and pension sectors across Nigeria and West Africa. He has held key editorial positions at major national media outlets, including The Comet, The Nation, and Financial Standard, and currently serves as a Senior Financial Analyst at BusinessDay Media Ltd. A widely travelled reporter, he has covered industry developments in more than 14 countries across Africa and Asia. Anaesoronye is a multiple award-winning journalist, honoured several times as Insurance Journalist of the Year and Pension Journalist of the Year by recognised industry bodies, including PensionScope and the Pension Fund Operators Association of Nigeria (PenOp), among others.

