Rio Times Global Economy Briefing
Key Facts
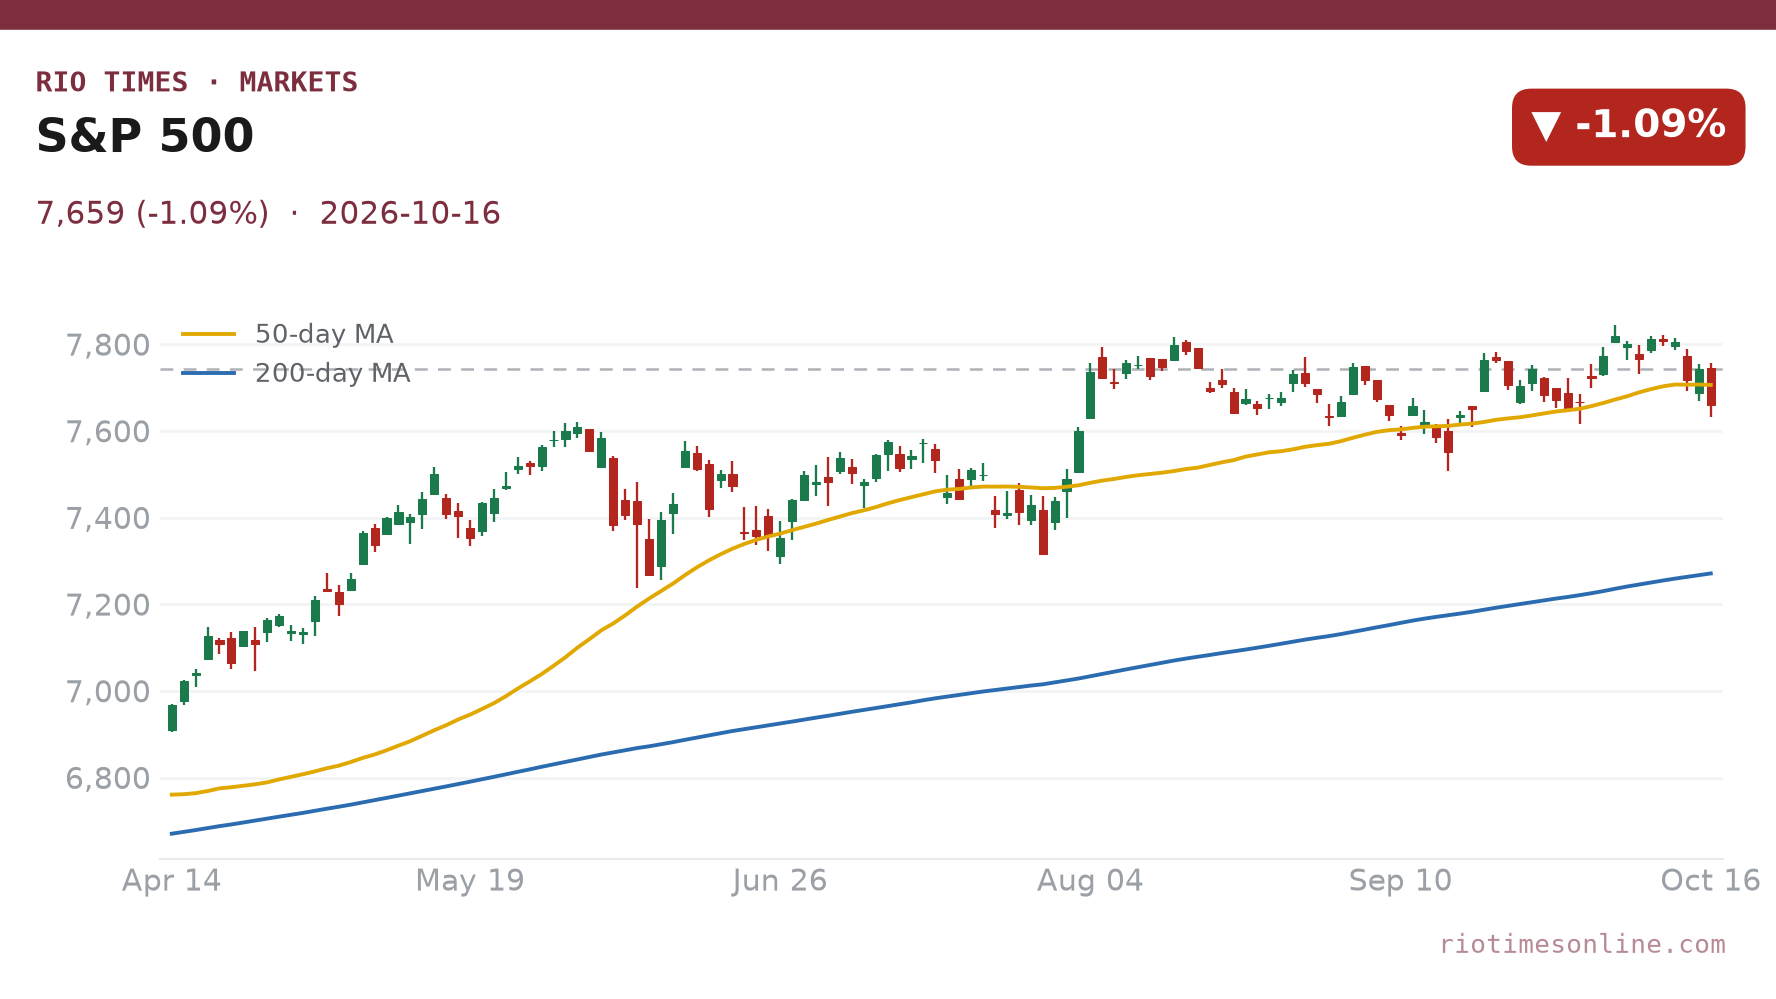
- Wall Street fell on Friday with the S&P 500 down 1.09% to 7,659, the Nasdaq down 2.1% and the Dow down 0.34% to 52,002.
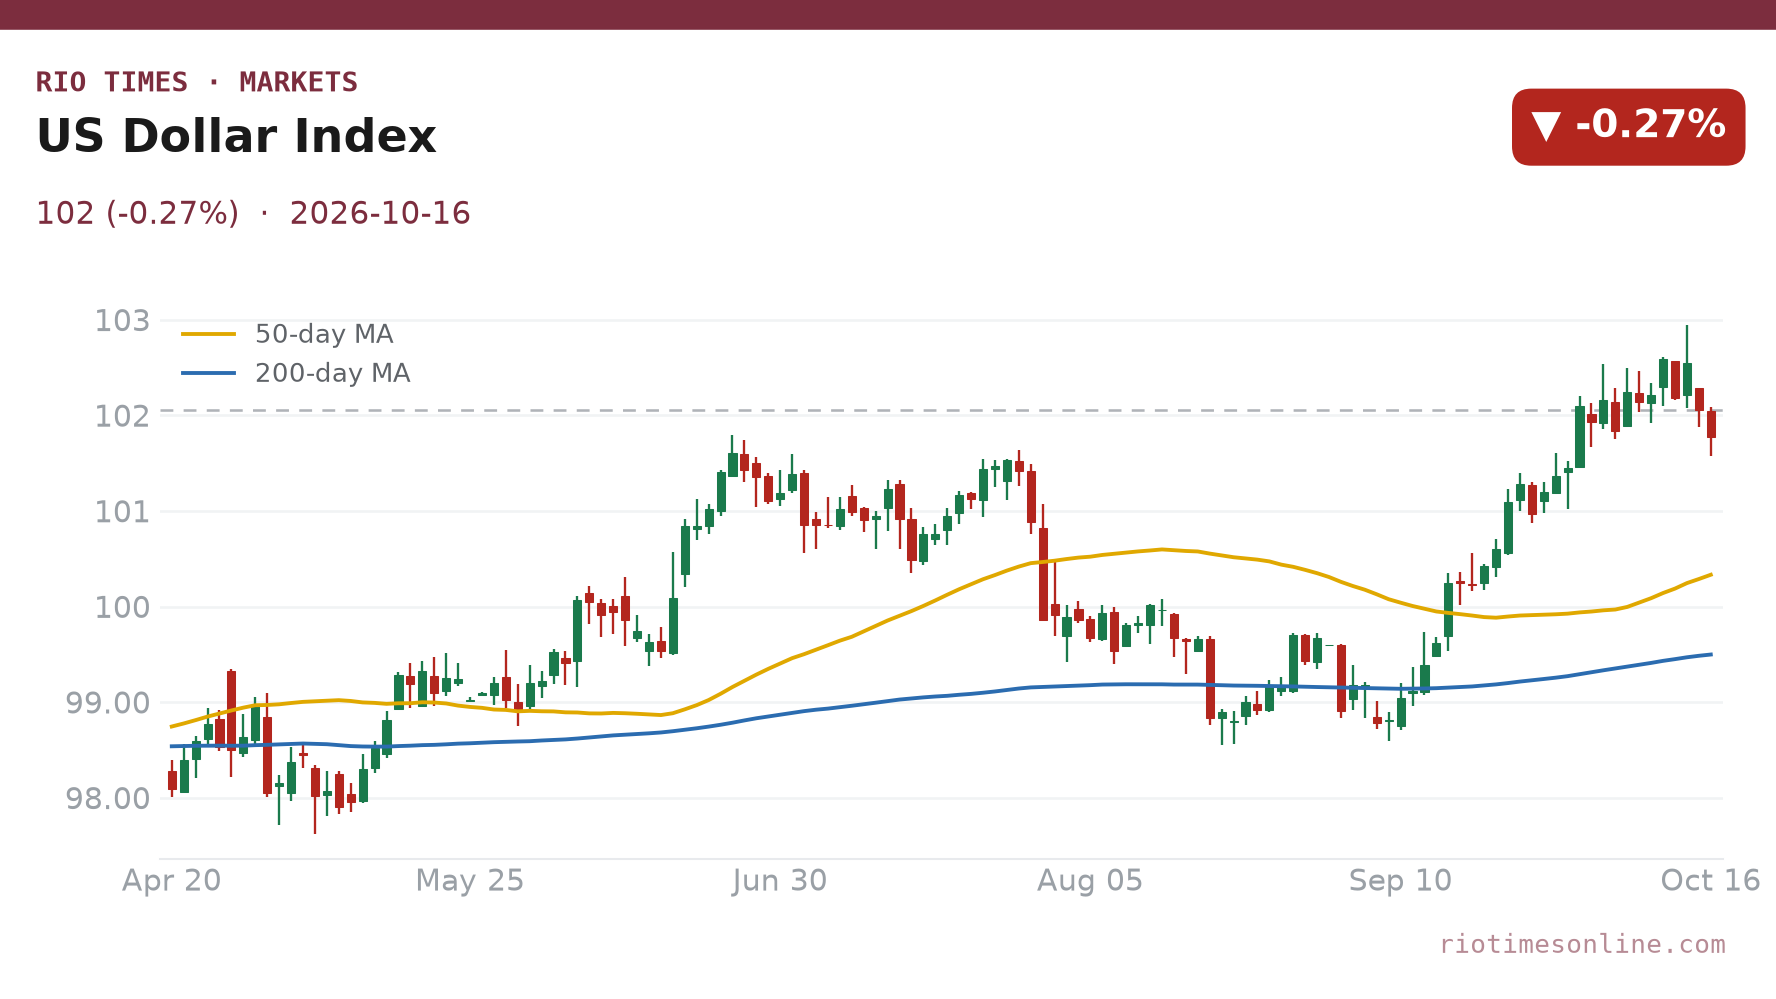
- The dollar index fell 0.27% to 101.779 and gold rose 0.2% to US$4,165 an ounce.
- The US 10-year Treasury yield was 5.085% and the VIX fear gauge jumped 21% to 19.99.
- US industrial production rose 0.7% in September against a 0.4% forecast, and euro area inflation was confirmed at 3.8%.
- Prediction markets Polymarket prices no change at the Federal Reserve’s October decision at 86.5% and a 25-basis-point hike in December at 76.5% (read at 11:15 pm ET on 16 October).
The Big Three
- AI debt anxiety keeps technology stocks under pressure Yields on CoreWeave’s bonds climbed to about 15% this week, highlighting fears that heavily indebted data-centre companies may struggle to repay borrowing while rates stay high. The Nasdaq fell 2.1% on Friday.
- Dollar index ends the week lower The dollar index fell 0.27% to 101.779 on Friday, its second straight daily decline, and ended below last Friday’s 102.213. The 10-year Treasury yield held near 5.1%.
- Volatility jumps as investors hedge The VIX fear gauge rose 21% to 19.99 from 16.46, while gold edged up 0.2% to US$4,165 an ounce.
S&P 500
7,659
-1.09%
Tech-led retreat
Dow Jones
52,002
-0.34%
Broader but gentler pullback
Nasdaq Composite
26,140
-2.15%
Technology credit stress bites
Gold
$4,165/oz
+0.21%
Soft-dollar bid persists
US 10-year Treasury
5.085%
+0.22%
Yield firms despite dollar dip
US dollar index
101.779
-0.27%
Lower on the week
VIX
19.99
+21.45%
Fear gauge jumps sharply
One-stop reference
Company Intelligence
Every listed company in Latin America — financials, ownership and structure for 1,450+ companies across 26 exchanges, in one place.
United States
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| S&P 500 | 7,659 | 7,744 | Lower |
| Dow Jones | 52,002 | 52,178 | Modest decline |
| Nasdaq | 26,140 | 26,713 | Sharp AI pressure |
| US 10-year | 5.085% | 5.074% | Still restrictive |
| VIX | 19.99 | 16.46 | Risk aversion rising |
| US industrial production, Sept (monthly) | 0.7% | 0.1% | Beat the +0.4% forecast |
Europe & United Kingdom
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| Germany 10-year yield | 3.440% | 3.423% | Edges higher |
| Euro area inflation, Sept (annual) | 3.8% | 3.2% | Confirms flash estimate |
| Euro area inflation, Sept (monthly) | 0.6% | — | Monthly rise |
| Euro area core inflation, Sept (annual) | 2.5% | 2.4% | Edges higher |
| Euro area harmonised inflation excluding energy and unprocessed food, Sept (monthly) | 0.2% | — | Core price pressure steady |
| Euro area balance of trade, Aug (EUR bn) | -16.1 | 10.7 | Swing to a deficit |
Asia-Pacific & Emerging Markets
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| China yuan (per US$) | 6.686 | 6.691 | Strongest since early 2023 |
| Indonesia Composite Index | 5,185 | 5,864 | Down 11.6%, MSCI status concerns |
| Brazil real (per US$) | 5.0648 | 5.0970 | Real firms 0.6% |
| Instrument | Level | Session |
|---|---|---|
| S&P 500 (US) | 7,659 | -1.09% |
| Ibovespa (Brazil) | 205,430 | +0.54% |
| USD/BRL | 5.0648 | -0.63% |
Source: market close, 16 October 2026.
Today’s Economic Calendar — Saturday, October 17, 2026
| Time | Country | Event | Consensus | Prior |
|---|---|---|---|---|
| — | — | No major data releases scheduled on Saturday | — | — |
Live Market IntelligenceGlobal Markets — Live BoardInside: market breadth, the sector heatmap, currencies & rates, the Latin America scoreboard and the full instrument board.
Rio Times · Live Market Intelligence
Global Markets — Live Board
World
Oct 17, 2026 · 00:19
S&P 500 · benchmark
7,751 +0.29%
Market breadth · 15 names
60% advancing
9 ▲ advancing6 declining ▼
Currencies, rates & key inputs
EUR / USD
1.1523
-0.20%
US 10-yr
4.6760
-0.17%
VIX
14.60
-4.45%
Gold
4,461
+1.78%
Brent crude
88.88
-0.03%
Full instrument board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| SPX | 7,751 | +0.29% | — | — | — | — | — |
| NDX | 29,799 | +0.93% | — | — | — | — | — |
| DJI | 53,810 | +0.03% | — | — | — | — | — |
| RUT | 3,041 | +0.46% | — | — | — | — | — |
| US10Y | 4.6760 | -0.17% | — | — | — | — | — |
| VIX | 14.60 | -4.45% | — | — | — | — | — |
| DAX | 26,331 | -0.23% | — | — | — | — | — |
| FTSE | 10,833 | -0.10% | — | — | — | — | — |
| CAC | 8,675 | -0.46% | — | — | — | — | — |
| STOXX | 659.48 | -0.16% | — | — | — | — | — |
| NIKKEI | 67,524 | +0.83% | — | — | — | — | — |
| HSI | 25,440 | -0.83% | — | — | — | — | — |
| KOSPI | 6,579 | +3.68% | — | — | — | — | — |
| CSI300 | 4,691 | +0.58% | — | — | — | — | — |
| NIFTY | 24,436 | -0.15% | — | — | — | — | — |
| TSX | 36,619 | +0.39% | — | — | — | — | — |
| GOLD | 4,461 | +1.78% | +33.20% | 4,383 | 4,503 | 4,421 | 139,824 |
| SILVER | 65.59 | +1.26% | +73.05% | 64.77 | 66.98 | 64.81 | 46,406 |
Largest moves today
VIX 14.60 -4.45%
KOSPI 6,579 +3.68%
GOLD 4,461 +1.78%
SILVER 65.59 +1.26%
NDX 29,799 +0.93%
NIKKEI 67,524 +0.83%
HSI 25,440 -0.83%
CSI300 4,691 +0.58%
The session read
The S&P 500 rose 0.29%, with breadth positive — 9 of 15 names higher. KOSPI led, while HSI lagged.
01 The AI dream meets the cost of capital
Friday’s retreat was less a broad flight from risk than a repricing of expensive technology. Debt-heavy AI infrastructure names are exposing the market’s fault line: exceptional growth expectations meet borrowing costs that remain punishingly high.
CoreWeave’s bond yields near 15% this week illustrate the pain. The Nasdaq fell hardest while the Dow slipped only modestly.
For Brazil and Latin America, the message runs through the dollar and US yields. Any renewed technology liquidation can pull foreign capital towards cash and Treasuries, tightening financial conditions even if the real initially benefits from a softer dollar.
02 The Fed’s narrow path
A slightly firmer 10-year yield at 5.085% and a weaker dollar appear contradictory. Yields have eased from 5.19% on Wednesday but remain high, which keeps the Federal Reserve’s path narrow.
The VIX jumped 21% to 19.99, showing that option traders expect choppier conditions. Persistent inflation could delay any US easing.
For Brazil’s Banco Central, this limits room for aggressive Selic cuts. A firmer US yield would pressure the real and raise imported inflation.
03 A calmer dollar, an unsettled world
China’s yuan firmed to 6.686 per dollar, its strongest since early 2023. Investors await China’s third-quarter GDP on Monday, 19 October, for clues on global demand.
Indonesia’s Jakarta Composite Index fell 11.6% on Friday to 5,185 amid concerns over MSCI’s review of the market’s status, a warning for emerging markets. Brazilian assets remain highly leveraged to US rate expectations.
Euro area inflation was confirmed at 3.8% in September, up from 3.2% in August, which keeps European rate expectations firm.
Assessment — Tech Credit Stress Meets a Softer Dollar MEDIUM
Wall Street fell and the VIX jumped even though US industrial production beat forecasts (+0.7% against +0.4%), so the pressure appears to come from technology financing rather than from US activity data. The risk is that Treasury yields near 5.1% keep weighing on debt-heavy AI companies.
The variable to watch is the 10-year yield: a move back above 5.19%, where it closed on Wednesday, would put emerging-market currencies such as the real back under pressure.
What Prediction Markets Say
- Federal Reserve, October decision: no change 86.5%, 25 bp hike 13.5% (Polymarket, US$44.7 million traded)
- Federal Reserve, December decision: 25 bp hike 76.5%, no change 20.5% (Polymarket, US$3.8 million traded)
Prices are bets, not polls, and were read at 11:15 pm ET on 16 October. Why we show this: prediction markets turn real-money bets into a live probability that moves within minutes of the news, which is why investors, campaigns and newsrooms in the United States now follow them closely. We show them next to polls and official results, never instead of them.
What to watch today and this week
- Monday 19 October: China third-quarter GDP (forecast 4.4% year on year, prior 4.3%) plus September retail sales and industrial output.
- Wednesday 21 October: UK inflation for September (forecast 3.4%, prior 3.1%) and US weekly crude stocks.
- Thursday 22 October: US weekly jobless claims (forecast 200,000, prior 199,000).
- Friday 23 October: flash PMI business surveys for the US (composite forecast 57.6, prior 58.4), the euro area and the UK.
- Ongoing: Brazilian real sensitivity to US yields, dollar demand, and expectations for the Selic.
Frequently Asked Questions
Why did technology stocks fall?
Investors questioned whether debt-heavy AI infrastructure companies can generate profits quickly enough to service elevated borrowing costs.
What supported gold?
A softer dollar and US Treasury yield moves supported gold near US$4,165 an ounce.
Why does the dollar matter for Brazil?
A stronger dollar can weaken the real, increase imported inflation, and reduce room for Selic easing; a softer dollar can provide relief.
What is the main Fed risk?
Persistent inflation and Treasury yields above 5% could keep US rates restrictive for longer than markets expect.
What is next for global markets?
China’s third-quarter GDP on 19 October, UK inflation on 21 October, US jobless claims and the 23 October PMI surveys are the key near-term catalysts.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.