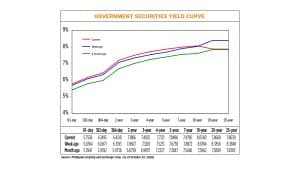
YIELDS on government securities (GS) traded at the secondary market were mostly higher last week as the market focused on the Bangko Sentral ng Pilipinas’ (BSP) policy decision, especially amid heightened inflation fears and the peso’s plunge to new record lows.
GS yields, which move opposite to prices, edged up by an average of 0.19 basis point (bp) week on week, based on the PHP Bloomberg Valuation Service Reference Rates as of Oct. 23 published on the Philippine Dealing System’s website.
At the short end of the curve, rates ended higher across all tenors, with the 91-, 182-, and 364-day Treasury bills (T-bills) rising by 7.74 bps (to 5.7538%), 8.24 bps (6.1495%), and 11.48 bps (6.4341%).
Yields at the belly also rose across the board week on week. The rates of the two-, three-, four-, five-, and seven-year Treasury bonds (T-bonds) went up by 12.79 bps (to 7.1886%), 16.64 bps (7.4925%), 18.9 bps (7.7121%), 17.58 bps (7.8496%) and 9.18 bps (7.979%), respectively.
At the long end, the 10-year T-bond rose by 3.56 bps week on week to yield 8.054%. Meanwhile, rates of the 20- and 25-year notes plunged by 51.88 bps (to 7.8668%) and 52.09 bps (7.8639%).
GS volume traded reached P16.24 billion on Friday, lower than the P19.94 billion logged a week earlier.
“Peso weakness and inflation concerns kept most yields moving upwards during the week, but a reprieve from climbing US Treasury yields eased upward pressure on the local GS curve’s tail,” University of Asia and the Pacific Economist Marco Antonio C. Agonia said in an e-mail.
He noted that the average movement in the GS yield curve was distorted by institutional buying activity at the long end, specifically the 20-year and 25-year bonds as their rates went above 8%. This caused yields on these tenors to go down substantially week on week.
“Market participants largely de-risked and shortened duration ahead of the policy meeting. This initial downward movement in short-dated tenors provided some room for yields to move upwards, tracking the large BSP rate hike. That said, the largest yield increases were in the belly of the curve, with the mid-dated tenors hiking by double digits (on a weekly basis), tracking the BSP’s higher-for-longer outlook,” Mr. Agonia said.
The Monetary Board on Thursday hiked benchmark rates by 50 bps, a move predicted by only two out of the 22 analysts in a BusinessWorld poll that had the other 20 economists penciling in a smaller 25-bp increase.
This was the first 50-bp hike in nearly four years or since February 2023 and marked the BSP’s fourth straight tightening move this year, bringing cumulative increases since April to 125 bps.
The central bank said the “decisive” policy move was necessary to address broadening price pressures and keep inflation expectations anchored amid further upside risks, especially with expectations of strong El Niño conditions over the coming months.
The BSP maintained its inflation forecast at 6.1% for this year but raised it to 6% for 2027 from 5.4% previously. It kept its inflation estimate at 3.3% for 2028.
Headline inflation returned to this year’s peak of 7.2% in September amid renewed price surges in oil, food, housing, and utilities. This was the seventh consecutive month that inflation was above the BSP’s 3% target, with the year-to-date clip standing at 5.4%.
Meanwhile, the peso closed at record lows for five straight sessions last week. On Friday, it sank by 9.5 centavos to end at P63.615. It also logged a new intraday trough of P63.62 during the session.
For this week, the market is awaiting the US Federal Reserve’s policy meeting on Oct. 27-28, Mr. Agonia said.
“Current market-based assessments price in an overwhelmingly large chance of a Fed hold, with the Fed futures showing an implied 90% probability of a hold in its October meeting. Assuming no further signals from important Fed officials, markets will be very surprised to see any hike in October. That said, the situation may change if other Fed officials weigh in, as Fed Chair Kevin Warsh’s reluctance to give forward guidance keeps markets hunting for more clues,” he said.
“Locally, a Fed hold may help contain yield upside for the sensitive 10-year tenor. Inflation outlooks, Middle East signals, and the Fed decision may induce repricing movements along the curve.”
He added that the Bureau of the Treasury’s dual-tenor bond auction this week could also cause some movement at the belly of the curve.
The government wants to raise a combined P35 billion from its dual-tranche bond auction on Tuesday, or P25 billion from seven-year bonds with a remaining life of two years and 11 months, and P10 billion via 10-year securities with a remaining life of nine years and three months. — Aliyah Naomi Ngking