For the first time since its launch a decade ago, merchants will soon have to pay fees to use the system. Some are suggesting that Washington may be behind the move.
In September, India’s Narendra Modi government unveiled a radical change to its Unified Payments Interface (UPI), the country’s instant digital payment system. That change involved the introduction of fees for the first time since its pilot launch in 2016. In September, the National Payments Corporation of India (NPCI) said a 0.4% fee would apply from October 15 (i.e. yesterday) to certain UPI payments above 2,000 rupees ($21) made to businesses by customers.
The initial announcement sparked fears that the fees could raise expenses for businesses, and by extension their customers, and discourage them from using the system. As those fears rose, the authorities made a partial U-turn. On October 13, just two days before the fee was to come into effect, the NCPI postponed the rollout until after the Diwali festival. But it is only a temporary respite.
UPI is the world’s largest real time payments system, with over 500 million users. In August alone, it processed 24.51 billion transactions worth ₹29.82 trillion ($314 billion). However, one of the main reasons for UPI’s undeniable success is that it is (or at least was) free to use for everyone. Many vendors originally made the switch to UPI because it was promoted as a free, convenient payment solution.
Launched in 2016 as a private-public partnership, UPI lets people send and receive money instantly through mobile apps, much like Brazil’s Pix system. The speed and ease of use has made it an integral part of the Indian economy, used by everyone — from small vendors to large corporations. As Business Times notes (with the media’s usual disdain for cash), “paying for goods no longer involves handling grubby old currency notes.”
The payment rails undergirding the system are operated by the National Payments Corporation of India (NPCI), an umbrella organisation established as a not-for-profit initiative by major banks. The underlying protocol standardises real-time bank-to-bank transfers so that any bank or wallet can talk to any other without closed, proprietary walls.
This has allowed private companies to build consumer and merchant apps that sit on top of the public payment rails. Until now, the government, banks and payment companies have borne the cost of running and expanding the system, which is currently dominated by two foreign-owned apps: Walmart’s PhonePe and Alphabet’s GooglePay, which together enjoy around 80% market share by value of UPI transactions.
The new charge, known as the Merchant Discount Rate (MDR), is expected to help cover some of those costs, and will be distributed among payment system providers — including banks — to support operations and continued expansion, the finance ministry press release stated. That’s the official reason, but it may not be the only one. As some are pointing out, the US government may also have played a part in the decision.
Interesting Timing
The announcement of the introduction of the MDR came just as India and the US are working to finalise their bilateral trade deal. This has fuelled speculation that the Modi government was pressured by the Trump administration into imposing the fee. Earlier this week, Congress Congress general secretary Jairam Ramesh said the government had broken the trust of UPI users and asked whether it had done so on behalf of US companies to appease Trump.
While there is no definitive proof to back that assertion, Washington has persistently pushed most of its trade partners to create a level playing field in their respective digital transaction ecosystem, reports India Express:
Since UPI’s launch in 2016, US payments market intermediaries Visa and Mastercard have cited loss of potential business as consumers in India increasingly turned to free UPI payments rather than using cards.
The Delhi-based think tank Global Trade Initiative (GTRI) said that the companies object to the “Zero transaction charges for UPI and RuPay, government promotion of RuPay, and RuPay’s early access to credit-card payments through UPI. This has strengthened RuPay and reduced the fee income of US card companies, it said.
It said that the two companies operate under a model where banks, payment processors and card networks earn fees from merchant transactions. A widely available, interoperable and zero-Merchant Discount Rate (MDR) platform, such as UPI, limits this revenue pool. An MDR is levied on merchants by banks that process payments to help meet transaction processing, settlement and infrastructure costs.
Further, RuPay challenges their position by providing an Indian card network that can be integrated closely with domestic policy objectives, GTRI said.
In March, the United States Trade Representative (USTR) had classified India’s digital payment policies “favouring” domestic players as a foreign trade barrier. Such barriers in various sectors are prominent demands under the proposed US-India trade deal.
The USTR said that “it has expressed concerns related to the inability of US electronic payment services suppliers to participate in the UPI ecosystem, including credit transactions on UPI on a level playing field with RuPay”.
“In November 2020, National Payment Corporation of India (NPCI) announced a market share limitation of 30% (measured by transactions) for third-party app providers initiating online payments made through India’s UPI. While this market share cap for third-party payment apps was originally mandated for January 2023, the NPCI has deferred enforcement, with the current deadline set for December 2026. As of December 31, 2025, two US-owned EPA suppliers together processed more than 80% of all UPI transactions,” USTR said. These suppliers are Walmart-backed PhonePe and Google Pay.
In other words, the USTR is concerned not only about the risk of UPI and its accompanying global card payment network, Rupay, eroding the market share of VISA and Mastercard in India (and potentially beyond), but also about India’s plans to reduce the dominance of the two US-owned payment apps, Walmart’s PhonePe and Alphabet’s GooglePay, over the UPI space.
Parallels With Brazil
This is not the first time the US has tried to bully a country into changing its indigenous payment system. As we have previously reported, Brazil’s development of Pix, a publicly owned and controlled digital payments system that has reduced the country’s dependence not only on Visa and Mastercard’s global duopoly but also on the mobile payment apps of US tech giants, has caused consternation on Wall Street and Silicon Valley, and by extension Washington DC.
The Office of the US Trade Representative began investigating PIX last year, warning that Brazil has given an unfair advantage to the digital payments system by requiring all banks to offer it. According to the NY Times, US trade authorities are also concerned that, by protecting consumer data that Pix collects, the Brazilian government is hurting American companies that use such information to make business decisions and develop new products.
“U.S. companies see this data as critical,” said Ignacio Carballo, a senior consultant at Payments and Commerce Markets Intelligence, a research firm based in San Francisco. “This places a lot of power in the hands of Brazil’s government.”
By embracing a largely publicly led digital payments infrastructure that cuts out the usual middle men, Brazil has turned financial innovation on its head. In most advanced economies, cash’s dominant role in the retail payments system has been eroded by digital payment alternatives, mainly from the private sector, in particular contactless debit and credit cards. Mobile wallets operated by US tech giants are also on the rise.
This has been a massive boon for Visa and Mastercard, which have done everything they can to supplant their biggest rival (to date), cash. In Brazil, however, Pix has not just overtaken cash; it has overtaken everything. As an article in Rest of World notes, it overtook debit card transactions in January 2022 and credit cards in February 2022, and now dwarfs transactions via credit cards, debit cards, bank slips, wire transfers, prepaid cards, and checks combined.
One major difference between Pix and UPI is that Pix is a public payments system created, owned, and operated by the Central Bank of Brazil (BCB) whereas UPI is a private-public system that is already dominated by two US-owned apps. Also, Brazil’s President Luiz Inácio Lula da Silva has resisted US pressure to bring Pix into line. A few months ago, he rejected any possibility of Pix being altered or privatised in order to benefit US financial interests.
“We defend Pix from any attempt at privatization. Pix is from Brazil. It’s public, it’s free and it’s going to stay that way.”
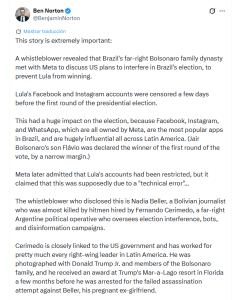
That said, Lula may soon no longer be president of Brazil, if recent polls for the second round of the upcoming presidential elections are any indication. Lula already lost the first round to his main rival, Flavio Bolsonaro, who has already agreed to make certain concessions on Pix. As the tweet below explains, Bolsonaro is benefitting from the support not only of the US and Israeli governments but also US tech firms like Meta.

A Sticky Dilemma
Back in India, the proposed imposition of a fee on UPI leaves Indian business owners facing a sticky dilemma: absorb the additional expense themselves or pass it on to their customers. As a direct result, these transaction charges are likely to raise the prices of basic goods and services. Everything from food items and fuel to routine retail purchases over 2,000 rupees will effectively become more expensive for ordinary shoppers.
Unless, of course, they go back to cash, which continues to play a vital role in the Indian economy, even as digital payments have exploded. Indeed, the amount of cash in circulation continues to grow as its share of everyday payments shrinks, reports the BBC:
The Reserve Bank of India (RBI) – the country’s central bank – now has 176 billion banknotes in circulation. It’s printing 28-30 billion fresh ones across six denominations annually and retiring roughly 21 billion. It is a vast logistics operation.
And yet, as Unified Payments Interface (UPI) digital transactions surge towards a billion a day, cash sloshing around the economy keeps climbing at a brisk pace.
The puzzle is not that Indians still use cash – 94% of transactions were cash-based as recently as 2019, according to new research by Anirudh Tagat, Mehmet Ozmen and Pushpa Trivedi. It is that cash is growing even as its share of everyday payments shrinks.
“The cash paradox has been examined globally, and India is a unique and novel case study of the same given the scale of both cash and non-cash payments,” Tagat, an economist who studies Indian payment behaviour, told the BBC.
He notes that the phenomenon of cash growing alongside digital payments has been especially prominent since the 2007-08 global financial crisis, with Bank for International Settlements research showing a similar pattern worldwide.
In Tagat’s framing, currency still serves three purposes – as a means of payment, a store of value and a hedge against calamity. Apps are replacing only the first. That helps explain why digital payments alone cannot tell the whole story of cash demand.
It will be interesting to see what consequences the introduction of fees to UPI has for India’s native payment system. After all, the Modi has done more than any government in Indian history — and more than most governments around the world — to promote digital payment methods.
It was the Modi government, with the support and guidance of the Bill and Melinda Gates Foundation, that launched India’s demonetisation campaign in 2016, whose disastrous consequences Jerri Lynn Scofield covered in great deal for this site. It was the Modi government that launched UPI just months earlier, as well as Aadhaar, India’s biometric digital identity system, years earlier.
There have been suggestions that USAID, the CIA’s soft-power arm, played a key role in promoting UPI. It is certainly coincidental that months after the launch of UPI, USAID announced the launch of a new initiative, called Catalyst of all things, in partnership with the Indian finance ministry, to scale digital payments systems in India.
A Brief Delay in Implementation
On Tuesday, the National Payment Corporation of India announced that it had decided to postpone the rollout of fees on UPI until after the Diwali festival. From Reuters:
“Diwali, which will be celebrated across India on November 8, typically marks the peak of consumer spending in Asia’s third-largest economy, with shoppers splurging on cars, clothes and home appliances”:
The proposed fee, which would end more than six years of zero-cost UPI payments in India, had drawn opposition from retailers…
The delay in implementation would likely allow payments firms to upgrade systems and not pass on costs to customers, while addressing issues that retailers may face during the festive period, Reuters reported last week, citing sources…
Shares of digital payments firms Paytm (PAYT.NS), opens new tab, Pine Labs (PINL.NS), opens new tab and One MobiKwik Systems (ONEM.NS), opens new tab gained 1%, 1.8% and 1.3%, respectively, after the news.
“The notice…brings certainty that the MDR (Merchant Discount Rate) is going to be implemented and there is no more scope of any pushback…versus the earlier uncertainty around the timeline,” said Rahul Jain, director of research at Dolat Capital.
“That is a positive for the companies,” he added.
Said companies presumably include VISA and Mastercard.
