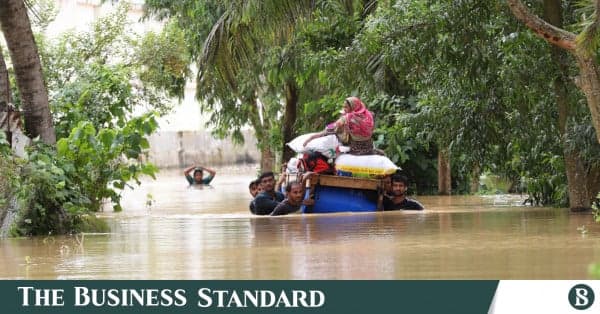
Bangladesh's struggle against disasters is not merely a story of survival; it is a story of economic resilience, financial security and national development. Every year, cyclones, storm surges, floods, river erosion and rising salinity threaten communities across the country, particularly along the coastal belt. Behind every damaged embankment, submerged field and destroyed fishing boat lies a chain of economic consequences that extends far beyond the affected village. Household savings disappear, businesses lose capital, agricultural production declines, employment becomes uncertain and the government faces mounting pressure to finance emergency relief and reconstruction.
As Bangladesh observes the International Day for Disaster Risk Reduction on 13 October, the country must recognise a fundamental economic reality: disaster prevention is not simply an expenditure; it is an investment in national prosperity.
The economic cost of disasters
Bangladesh has made considerable progress in disaster preparedness, particularly through cyclone early warning systems, community-based response mechanisms and cyclone shelters. Nevertheless, economic consequences of disasters remain substantial.
According to the International Monetary Fund's 2025 Technical Assistance Report on Disaster Risk Financing, natural hazards affected approximately 130 million people in Bangladesh between 2000 and 2023 and caused an estimated US$13.6 billion in total damage. The report also estimates that responding to a recurring disaster of the scale expected once every two years could require approximately US$4.7 billion for immediate response, early recovery, rehabilitation and reconstruction combined. These figures demonstrate that disasters are not isolated emergencies. They are recurring economic shocks that can weaken poverty reduction, disrupt investment and slow development.
The economic impact extends across multiple sectors. Agricultural losses reduce farmers' incomes and food supplies. Damage to roads, bridges, electricity networks and ports interrupts transportation and commercial activities. Fishing communities lose boats, nets and productive days at sea. Small enterprises may be forced to close, while workers lose wages and households struggle to meet basic expenses.
For a developing economy such as Bangladesh, these losses can undermine years of progress. Resources intended for education, healthcare, infrastructure and employment generation may have to be redirected towards emergency assistance and reconstruction.
The coastal belt: Where environmental risk becomes financial insecurity
Bangladesh's 19 coastal districts face a complex and interconnected range of natural and climate-induced hazards. Districts such as Satkhira, Khulna, Bagerhat, Barguna, Patuakhali, Bhola, Noakhali, Lakshmipur and Cox's Bazar are exposed, to varying degrees, to cyclones, tidal surges, flooding, river erosion and salinity intrusion.
For coastal households, disaster risk is inseparable from economic vulnerability. A cyclone may destroy a house, but its consequences can continue for years if the household loses its agricultural land, fishing equipment, livestock or access to employment.
Salinity intrusion presents another serious challenge. Increasing salinity in soil and water can reduce agricultural productivity, complicate access to safe drinking water and place additional pressure on household budgets. Farmers may have to change cultivation practices, invest in alternative water sources or abandon traditional crops. Fishers and aquaculture operators may also face changing environmental conditions, damaged ponds and uncertain production.
Women, landless labourers, small farmers and informal workers are particularly vulnerable because they often have limited savings, inadequate insurance and restricted access to affordable credit. When a disaster strikes, wealthier households may rebuild using accumulated assets, while poorer families may be forced to borrow at high cost, sell productive assets or reduce spending on nutrition and education.
The World Bank's 2025 report, From Risk to Resilience, highlights critical adaptation challenges in coastal Bangladesh. A survey of 250 coastal villages found that 57% of households cited inadequate disaster-protection infrastructure and 56% reported limited financial resources as major barriers, underscoring the need for resilient infrastructure and accessible adaptation finance.
The central policy challenge is therefore not simply to protect coastal communities from hazards, but to protect their ability to earn, save, invest and recover.
Disaster risk and public finance: A growing national challenge
Disasters create a difficult fiscal dilemma for the government. Emergency food distribution, temporary shelters, healthcare, cash assistance and infrastructure repair require immediate funding. Yet the scale and timing of disasters are uncertain, making it difficult to allocate sufficient resources through conventional annual budgeting alone.
When disaster-related expenditure rises unexpectedly, governments may have to postpone development projects, reallocate existing budgets or seek additional borrowing and external assistance. Reconstruction can also place pressure on public investment programs at a time when affected communities urgently need better roads, drainage, embankments, schools and healthcare facilities. Disaster risk should be integrated into public financial management, with budgets prioritizing cost-effective prevention in high-risk areas and transparent emergency funding. Disaster risk financing should also move beyond reliance on post-disaster relief. Bangladesh can strengthen contingency funds, develop appropriate risk-transfer mechanisms, improve emergency social protection and assess carefully designed insurance solutions. International climate finance and concessional development financing can complement domestic resources, particularly for large-scale adaptation projects that deliver long-term public benefits.
Financial planning must also consider who receives assistance and how quickly. A well-designed system of pre-arranged emergency finance and shock-responsive social protection can help vulnerable households receive support before they are forced to sell assets, withdraw children from school or take on unsustainable debt.
Banking, insurance and private investment
Disaster resilience is also a concern for Bangladesh's financial sector. When floods or cyclones damage farms, fisheries, homes and small businesses, borrowers may struggle to repay loans. Financial institutions can face rising credit risks, while enterprises may be unable to obtain the working capital required to restart operations.
Banks and other lenders should therefore incorporate climate and disaster exposure into their risk assessments. Lending decisions in vulnerable areas should consider the resilience of assets, the continuity of business operations and the borrower's capacity to recover from shocks.
At the same time, financial institutions can contribute to resilience by expanding access to affordable financing for stronger homes, climate-resilient agricultural practices, safe water systems, renewable energy and disaster-resistant business infrastructure.
Appropriately designed agricultural, property and microinsurance products could help distribute losses rather than leaving individual households to bear the entire burden. However, premiums must remain affordable, policy conditions must be transparent, and claims must be settled promptly. Insurance cannot replace public protection, particularly for households that cannot afford commercial coverage.
Small businesses also need emergency credit facilities and flexible repayment arrangements after major disasters. Such measures should be transparent and carefully targeted to support viable recovery rather than create unsustainable lending risks.
Private investment can play an important role, but it cannot replace the state's responsibility to provide essential public goods, including embankments, cyclone shelters, reliable warning systems and resilient public infrastructure.
Investing before disaster strikes
Bangladesh's experience demonstrates that sustained investment in preparedness can save lives. The next priority is to connect this achievement more directly with economic resilience.
First, coastal embankments, drainage systems and cyclone shelters require regular maintenance, risk-based upgrades and effective local oversight. Building infrastructure is not enough; it must remain functional when communities need it most.
Second, early warning systems must connect information to action. Forecasts should reach fishers, farmers, transport operators and remote households in accessible language and through reliable communication channels. Warnings must be accompanied by evacuation arrangements, safe shelters and practical guidance.
Third, agricultural adaptation should receive greater attention. Salt-tolerant crop varieties where suitable, improved water management, diversified livelihoods, climate-informed farming and resilient storage facilities can reduce the likelihood that a single disaster destroys an entire season's income.
Fourth, coastal ecosystems should be treated as productive natural infrastructure. Mangroves and other suitable natural barriers can complement engineered protection, reduce some coastal hazards and support biodiversity and livelihoods. Restoration programs must be based on local ecological conditions and long-term maintenance rather than tree-planting targets alone.
Finally, investment decisions should be made by transparent assessments of costs, benefits and distributional impacts. A project should be judged not only by its construction cost, but also by the losses it can prevent, the people it protects and the economic activity it enables.
A just and resilient future for coastal communities
Disaster risk reduction must also address inequality. A coastal protection program may reduce physical exposure, but its benefits will remain incomplete if landless workers cannot recover their income, women lack access to financial services, or displaced families cannot find secure livelihoods.
Local governments should work with communities to identify their most urgent needs and ensure that public investments reach the most exposed households. Education, vocational training, accessible banking, livelihood diversification and social protection can improve families' ability to recover and adapt.
Planned relocation may become necessary in some locations where risks become unmanageable. Such decisions must be evidence-based, participatory and sensitive to land rights, employment, social networks and cultural connections. Relocation should not transfer the economic burden of climate change onto the people least able to bear it.
Bangladesh also has a role to play internationally. Although its contribution to global greenhouse gas emissions is relatively small, it faces considerable climate-related risks. The country should continue advocating for accessible international adaptation finance, effective climate cooperation and support for communities facing unavoidable losses and damage.
From disaster response to economic resilience
The International Day for Disaster Risk Reduction should serve as a call to reconsider how Bangladesh plans its economic future. Disaster management cannot remain confined to emergency response after a cyclone or flood has already destroyed homes, livelihoods and infrastructure.
The country needs a coordinated approach that brings together public finance, banking, insurance, private investment, environmental protection and community preparedness. Every major development project should consider disaster exposure. Every coastal investment should be assessed for its long-term resilience. Every financial strategy should recognize that the poorest households often bear the greatest losses while possessing the fewest resources for recovery.
Bangladesh has already demonstrated that sustained preparedness and collective action can reduce the human toll of disasters. The next challenge is to ensure that these achievements also protect household wealth, preserve public resources, strengthen financial stability and sustain economic growth.
A disaster-resilient Bangladesh is not built only by rebuilding what has been destroyed. It is built by investing today so that fewer lives, livelihoods and public resources are lost tomorrow.
Abdul Quader is a PhD researcher in the Department of Geography and Environment at Dhaka University.