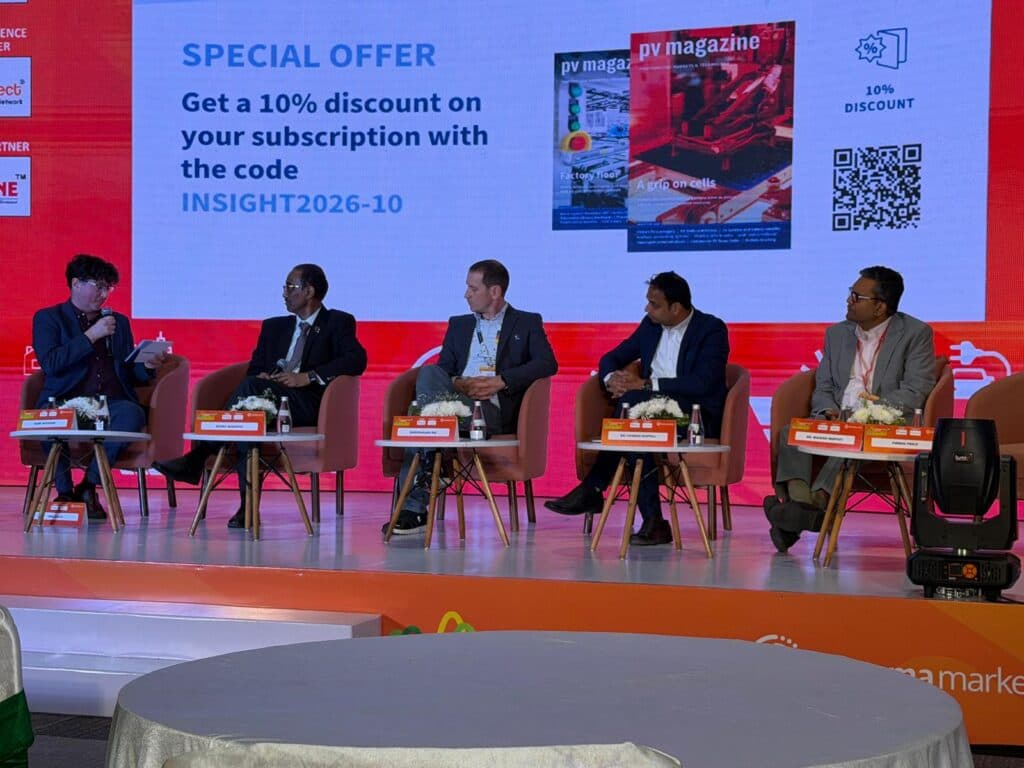
India’s solar and energy storage industry has grown to massive proportions, reflected in the more than 54,000 visitors that descended on Greater Noida’s India Expo Center this week for Renewable Energy India Expo (REI) and the Battery Show India, and the more than 1,000 exhibitors that filled the center beyond its capacity, with temporary buildings added and exhibits flowing out into the car park.
After three days navigating the halls and meeting with companies from up and down the solar supply chain, pv magazine has these three key takeaways from REI 2026.
Survival of the biggest
Previous years at REI saw a PV industry highly focused on bringing module assembly to India. And now, analysts estimate the country has more than 200 GW of annual module capacity – far beyond its expected demand for 50-60 GW of PV installations per year out to 2030.
This has many predicting a market shakeout beginning in 2027, where manufacturers operating module capacity only will struggle to find demand, and also to source cells since the country extended its domestic content requirements to the cell sector earlier this year.
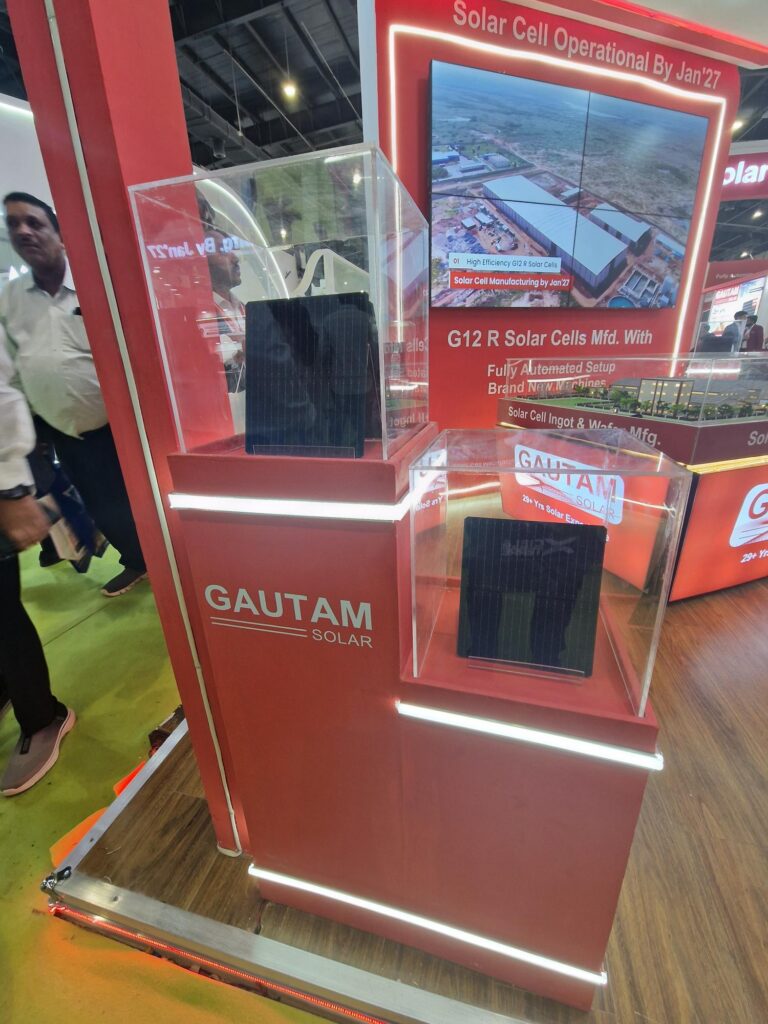
Many manufacturers at the show were keen to emphasize their ability to supply “domestic content requirement” modules. Nonetheless, 2027 may be a difficult year for some. India’s market is led by those companies that have been able to invest early in building out local cell manufacturing capacity – expected to reach 80 GW by the end of 2027.
Quality is also emerging as a key differentiator as module manufacturing heads into a highly competitive period. And speakers at pv magazine’s Insight session on day 2 were keen to emphasise their sophisticated quality control procedures, as well as work to ensure their modules are prepared specifically for the varying and often harsh climates found in India.
The next step for India’s domestic content plans is adding solar wafers to the list of components that must be produced in India for modules used in projects receiving government assistance. And many of those same companies are now announcing plans to produce wafers locally as well – Saatvik, Grew, Solex, Zetsol, Navitas, Reliance, Adani, and more all shared plans to have wafer production up and running by the time policy takes effect in 2028.
While India’s ambition to host the entire PV supply chain is clear, opportunities for international collaboration are still there, with some manufacturers happy to discuss OEM deals in place with established manufacturers in China, as well as collaboration with technology suppliers in Europe and the United States.
India’s PV market has long been utility-scale led, and so favored those with the ability to supply and operate at megawatt or even gigawatt scale. Many manufacturers that pv magazine spoke with this year, however, also expressed optimism about the country’s commercial and industrial sector, where companies are keen to secure long term energy prices away from the grid, and to meet decarbonization goals. Several also spoke of new demand from the residential sector, and particularly the opportunity that adding residential batteries to the PV offering will add in the next year or two.
Totally TOPCon
Virtually all of India’s cell manufacturing buildout is focused on tunnel oxide passivated contact (TOPCon) technology. And those manufacturers expect this to remain the mainstream for several years at least.
Reliance Industries, which is building out a 20 GW supply chain focused on heterojunction technology, is the most notable exception. A few others still have older passivated emitter rear cell (PERC) production lines that they expect to be able to keep running for a few more years at least. And mentions of back contact were few, and confined to those sourcing cells from abroad or working on OEM deals with Chinese manufacturers.
Most manufacturers told us that they have perovskite tandem cells on their radar, but still see this technology as at least five years away from commercial. Others though, including Grew Solar, Navitas Solar, Rayzon Solar and INA Solar, are partnering with US-based perovskite producer Caelux, and plan to have hybrid perovskite-silicon modules commercially available in India by 2028.
One stop shops
Moves to cover more of the supply chain also extend far beyond the cell and wafer segment. Other module components like encapsulant films, glass, aluminum are not covered by domestic content requirement, nonetheless several manufacturers are investing in capacity to produce these locally as well, while Indian solar glass maker Borosil is itself expanding into module production.
Many manufacturers are also expanding into projects sector, developing and building projects with their own modules. Waaree Energies and other companies more known in the PV module sector have begun producing inverters. Others including Gamechange Energy and Delta Electronics are expanding into production of transformers and other system components in India.
Some on the projects side of the industry said that the shock of the domestic content requirement for cells has pushed prices upward and temporarily slowed plans for new projects, all expect this to be a short-term issue though as India demonstrates that it has the scale and the capital to support an energy system based on components made in India.
The post Renewable Energy India Expo 2026: Three key takeaways appeared first on pv magazine Global.