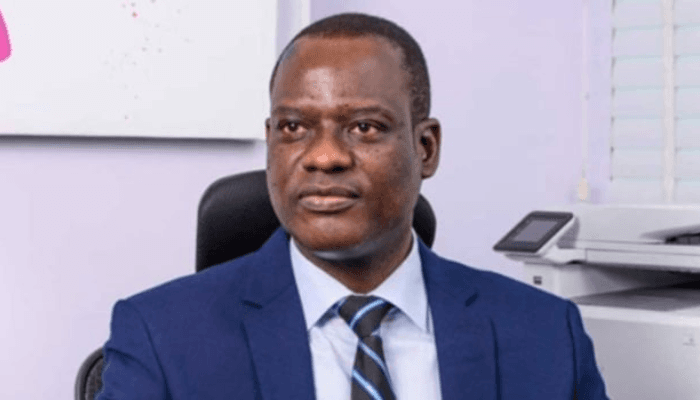
Nigeria is developing an economic policy framework to align fiscal, monetary and trade policies as the government seeks to expand regional trade, attract investment and support its ambition of building a $1 trillion economy, Finance Minister Taiwo Oyedele said.
The framework will incorporate Nigeria’s international commitments, including regional trade agreements, and guide how different economic policies work together, Oyedele said Tuesday at the IMF-World Bank Annual Meetings in Bangkok, Thailand.
“We’re developing an economic policy framework for Nigeria, and it has the international dimension, including the regional treaty,” Oyedele said during a panel discussion on “Africa’s Golden Future”, which focused on the continent’s economic prospects, structural reforms and private sector-led growth.
The minister said inconsistent policies could undermine efforts to integrate African markets, making it important for Nigeria to address domestic barriers before seeking deeper economic cooperation with other countries.
His remarks come as Nigeria implements the African Continental Free Trade Area (AfCFTA), which seeks to create a single market across the continent, allowing businesses to reach more customers, expand production and strengthen regional supply chains.
Oyedele said Africa needed to become more competitive internally, arguing that it should not be easier for businesses and consumers to buy goods from China than from other African countries.
The continent’s fragmented markets and non-tariff barriers continue to constrain trade, he said, adding that clearer standards, harmonised rules and supporting infrastructure would be necessary to realise the agreement’s potential.
Nigeria is introducing a national single window to streamline border procedures, using technology to make trade more efficient, although implementation is still under way, he said.
The government also needs to coordinate policies on tariffs, energy, logistics, agricultural processing and storage to strengthen domestic production and trade across the continent. Tariff protection, where necessary, should be strategic and phased out carefully to avoid making consumers pay for inefficiencies, Oyedele said.
He cited Nigeria’s recent reforms, including fuel subsidy removal, foreign-exchange reforms and tax changes, as examples of the importance of sequencing policies and maintaining public communication.
“Trust is not something you can’t legislate. You have to earn it,” he said.
“Capital follows trust before it follows returns,” Oyedele added, summing up the challenge facing African governments as they seek to turn reform commitments into investment, jobs and sustainable growth.
Oyedele said reforms needed to be designed with their intended outcomes in mind, embedded in institutions and legislation, and accompanied by measures to protect vulnerable households. Nigeria’s cash-transfer programme had reached more than 10 million households, while education support was helping students and their families, he said.
He also called for consistent policies that allow investors to plan over the long term, saying Nigeria’s reforms had laid the foundation for more inclusive growth and job creation.
The panel, titled “African Golden Future: Structural Reforms, Trade Integration, and Private Sector-Led Growth,” brought together policymakers, development financiers and business leaders to discuss how the continent could convert its demographic and resource advantages into sustained investment and higher living standards.
Bo Li, deputy managing director of the International Monetary Fund, said Africa’s young workforce, natural resources and expanding cities offered significant growth potential, but turning those advantages into higher incomes would require stronger institutions, better infrastructure and more private investment.
He cited IMF analysis suggesting that closing half the gap with emerging markets in governance, business regulation and market openness could raise sub-Saharan Africa’s economic output by as much as 20% over five to 10 years.
Li said reliable electricity, simpler business regulations, enforceable contracts and lower trade barriers were essential to attracting investors. He also highlighted the AfCFTA’s potential to connect a market of 1.3 billion people, while calling for better cross-border infrastructure, modern payment systems and investment in digital technology and skills.
Sidi Ould Tah, president of the African Development Bank Group, said the priority was to move from announcing reforms to delivering results. The bank was supporting reforms alongside investment in infrastructure and private-sector development, he said, highlighting Mission 300, an initiative with the World Bank and other partners aimed at expanding electricity access to 300 million people in Africa by 2030.
Ould Tah also said Africa needed to mobilise its own savings more effectively. He estimated that the continent had about $4 trillion in savings, but only 3% was directed towards infrastructure and productive sectors. He advocated stronger regional financial cooperation and guarantees to reduce investment risks and attract more private capital.
Ahmed Rostom, Egypt’s minister of planning and economic development, said stronger private-sector participation depended on credible institutions, responsible fiscal management and a clear division between areas led by private investors and sectors requiring government partnership to protect energy and food security.
He also called for improvements in customs procedures, recognition of rules of origin and technology to facilitate intra-African trade. Egypt was investing in ports, railways and roads and pursuing a plan to generate 42% of its electricity from renewable sources by 2030, he said.
Daniel Mminele, chairman of Nedbank Group and Nedbank Ltd., said macroeconomic stability was necessary but insufficient to attract long-term investment. Investors also needed predictable policies, effective implementation and confidence that contracts and property rights would be protected.
Related News

