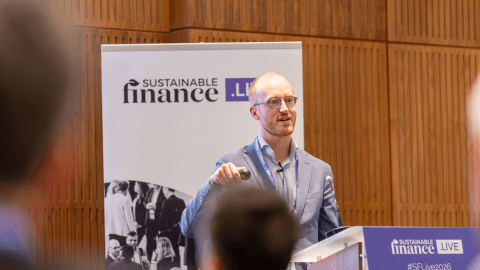
At Sustainable Finance Live 2026, the afternoon sessions discussed strategies to place social purpose over profit, improve access to inclusive banking, and use open data and AI to build community-led business models.
In the keynote session ‘Banking Needs a Social Purpose’, Ernst Hobma, economics researcher at Triodos Bank analysed how to confront a banking industry that places profit over people. Hobma started out by defining finance as “a system that serves society”, and as “a tool to reach the things we think collectively are desirable”. He described a dual approach that Triodos uses to make positive change in the banking sector: outline where change needs to take place, and finance the transitions to get there.
Hobna pointed out that today’s finance industry is not “fit for purpose”. He noted that while global financing is available on a “systems-level”, the problem is not lack of financing, but where the financing is being allocated.
“How much financing is still going to destroy nature, and it overwhelms the financing gap, right? So, speaking only of the shortage of money or financing, basically massively understates the problem because you're working against a system that, on balance, destroys a lot more than it creates.”
Referencing data from the UN’s State of Nature Finance report, he explained that lots of financing can also be incredibly harmful, which can outweigh financing for nature and sustainable solutions.
“We're in a moment in society when the need for change is abundantly clear,” Hobna said. “We have all these interconnected crises, and rather than sort of solving them one by one, we need to look at how can we reorganise systems and our system of systems to fundamentally eradicate these crises.”
Hobna provided a few examples of productive finance. One was B4RN, a UK provider of broadband in the rural north where there were previously no high-quality networks. The network focused on powering local internet - for businesses, libraries, schools – and created goodwill in the community. This led to landowners allowing them to pass cables through their land, and making B4RN a threat to commercial broadbands in the area who do not have the same community connections. This is an example of tapping into the strength of a community, Hobna stated.
The theme of the conference was reiterated: change can be created from community initiatives. However, for this to work, Hobna emphasised, there needs to be levers for change implemented by the government.
Hobna said that governments need to introduce financial guidance, which is outlining where private finance needs to go and regulating it. He cited efforts in France, India, and China where the government requires banks to invest a certain percentage of their investments into clean energy or green priorities as an example.
He noted that there needs to be guardrails in place to direct private finance towards public interests. Hobna pointed out that they are currently advocating for fossil fuel financing to be banned, which would be an easy to understand principle, based on scientific evidence, and could “embed the kind of thinking that finance should be a tool rather than an angle to municipal communities”.
Making local value visible and scaling inclusive financial services
Kicking off the 'Innovation vs Incumbency in the Race for Inclusive Banking' session at Sustainable Finance Live 2026 was Transition Value Partners founder Anna-Marie Slot, who led the panel featuring speakers Grassroots Economics Foundation’s Damaris Njambi Njoroge, CreditNature’s Irena Badelska and No1 CopperPot’s Caroline Domanski.
The discussion explored the nuances of community pooling, where individuals or groups combine their money, assets and time to fund mutual goals – in this case, ensuring communities can recognise the value in front of them to scale access to inclusive financial services.
Njoroge, in a short presentation, shared real-world success stories of community pooling from countries like India and Bhutan. She explained that “they realise that with what they offer, so much is needed, and they can grow themselves even without expecting external support”.
The core of Njoroge’s message was that with so much value existing within the community, by showing up for one another and pooling resources, communities can build the infrastructure they need and grow together. Slot asked Badelska to comment and explore one of the use cases mentioned by Njoroge and build a bridge between nature recovery in communities and inclusive banking.
Badelska mentioned that CreditNature is working on community pooling as part of green margin contributions, where participating supermarkets and retailers embed a small financial contribution into everyday transactions. This ‘Green Margin’ is taken from the business’s existing profit margin or transaction flow and does not result in any impact on the customer at checkout.
These micro-contributions are pooled to purchase Nature Investment Certificates, where the capital directly funds real-world rewilding and habitat restoration projects such as the Broughton Sanctuary in Yorkshire. Badelska explained that the financing of that project comes from a local pension fund, the West Yorkshire Pension Fund, which is backed by investment manager Rebalance Earth and benefit pension holders by protecting assets that are downstream from the project.
“That creates a virtuous cycle where benefits are created for the beneficiaries and the local community, while also protecting assets from climate risks, flooding and other climate hazards. A small contribution from every transaction can also be directed towards funding positive nature outcomes for the local community, creating jobs, health and wellbeing outcomes, and tangible financial benefits around heat stress alleviation and flood protection,” Badelska said.
Building on the idea that small contributions can deliver collective benefits, Domanski also mentioned that No1 Copperpot, a credit union for the police force and their families, is using its savings and lending model to offer financial incentives to lower carbon footprints.
Domanski said that as a mutually owned savings and loans company and the members all work within the community, savings and lending products work for their business. “A lot of people are still finding their own place and looking at what they can do to have an impact, and we see our role as helping people make choices that will help the environment.”
She added: “From Copperpot’s perspective, we very much see that small changes for individuals will add up to make a big change in the environment. We help people to save through payroll deduction, and those savings then support our lending, including a green loan that has now lent £1.5 million to almost 100 members. Ultimately, it’s about helping people have the options to make choices that will help the environment.”
Open data and AI could unlock resource liquidity for local communities
In a world in which firms like Uber and Airbnb have proven that social business models can lead to community integration, a number of issues abound. We remain time-poor and resources-poor. So, how can digital transformation and AI help connect resource liquidity with the services and assets that communities rely on?
This was the key question explored this afternoon in the panel, ‘A Marketplace for Resource Liquidity and the Role of Open Data and AI in Enabling Communities’. Moderated by Diba Salam, StudioDS, the panel featured Mark Chadwick, Kew Reach; Pooran Desai, OnePlanet; Helen Goulden OBE, Lloyds Banking Group; and Ru Pearce, Rewired Earth.
Doughnut economics
Salam opened the discussion by encouraging us to re-focus on the human perspective, which is so often lost in discussions of technology.
Incidentally this is also the jumping-off point for the Doughnut Economics philosophy, which seeks to pivot away from the perennial pursuit of GDP growth, toward thriving from an environmental, social, and governance standpoint. Most fundamentally, Doughnut Economics is about recognising that the economy is “embedded within, and dependent upon, society and the living world”.
Salam attributed the dire planetary-boundary picture to the fact that, in last 50 years, the roles of the household and the state have been reduced. “The market has dominated,” she said. “The youth is feeling disenfranchised and lost. We need to bring hope back to the story. We need to disrupt this trend.”
Fortunately, change is afoot. The Community Empowerment Bill, for example, received Royal assent in April 2026, supporting the government’s plan to rebuild and reform local government, as the foundation for devolution, and give communities stronger tools to shape their local areas.
Data-informed, not data-led
Of course, open data remains key for working with neighbourhoods and building out sustainable community assets, but to avoid losing sight of their stories, requirements, and goals, we need bespoke, innovative answers.
Desai was keen to outline the pitfalls of relying too heavily on data: “It’s a mistake to be data-led. We need to be data-informed. Data is only a small part of the picture. It can lead to incorrect conclusions. We should never be evidence-led, either. All evidence is in the past. It would be like driving while looking in the rear-view mirror. Let’s be informed by the evidence.”
Desai believes AI does have the capacity to help communities here, but we need to stay focused on the outcomes: “We shouldn’t let AI end up selling us more stuff we don’t need. We should look at how this technology can enable us to come together as communities.”
Trust as the foundation
As ever, scale was cited by the panel as one of the key blockers to unlocking resource liquidity within local communities.
“Lloyds Banking Group has 28 million customers,” commented Goulden. “It’s hard for banks to have a credit risk policy that enables them to lend to certain types of entities. There are two ways to respond. We either walk away and say it’s too difficult, or we work out how to fix the problem in collaboration.”
In March 2024, Lloyds Bank became the first high-street UK bank to make a direct commercial investment in enterprise-lending Community Development Finance Institutions (CDFIs). The initiative focuses on underserved small- and medium-sized enterprises (SMEs), start-ups, and underrepresented business owners – including women-led and ethnic minority-led firms – in deprived regions across England and Wales who are typically declined by mainstream bank lending policies.
“Every part of my heart loves this broader idea of thinking about a community’s aspirations and using AI to catalyse them,” Goulden said. “However, it is very complex. Making a case for the business model will be tough. Understanding that these things are not just nice-to-haves is hard. Who pays for it? Who gets value from it? When it comes down to it, many of these moving parts will not be online. It’s about building trust within these places as a foundation.”
Extolling the virtues of the “left brain”, as Desai coined it, Chadwick returned to brass tacks.
“Without revenue you don’t have a business model,” he stated. “If you’re interested in rebuilding nature, I’d first be thinking about how I establish a situation report, say from satellite or LiDAR data. Then, I’d ask where the opportunities to add value are. Who is interested in paying for that additional value? A collective inside a community will understand the gaps and can fill it with skills and knowledge. Here’s where a platform starts to become useful. If the platform can find funding and bring people together, then you have something very useful.”
Such a platform would need to, for instance, enable councils to contract multiple entities and achieve scale. Simply put, platforms and data must be rooted in outcomes in order to be effective.
Pearce agreed. He pointed to the need to see “what is physically happening” in communities, as well as to reach outcomes in a democratic way.
“What are the outcomes the community wants?” He asked. “We need to not just pay lip service but embed them. Unless we start in this way we’ll never get the outcomes we want. It’s not about cutting the ribbon on day one, it’s about cutting the ribbon on year 100. How do we steward these assets? How do we stop them being a drain on the community? How do we aggregate these assets? How do we bring insurers or investment funds in?”
Once again, it is the people – with their local skills and knowledge – who can make the rubber hit the road and bring the financing in.