South Korean pharmaceutical and biotech companies are expected to face earnings pressure in the third quarter as they overhaul distribution networks and reduce channel inventory. Analysts say some companies will fall short of market expectations as prescription volumes for their flagship drugs diverge from the revenue they book.
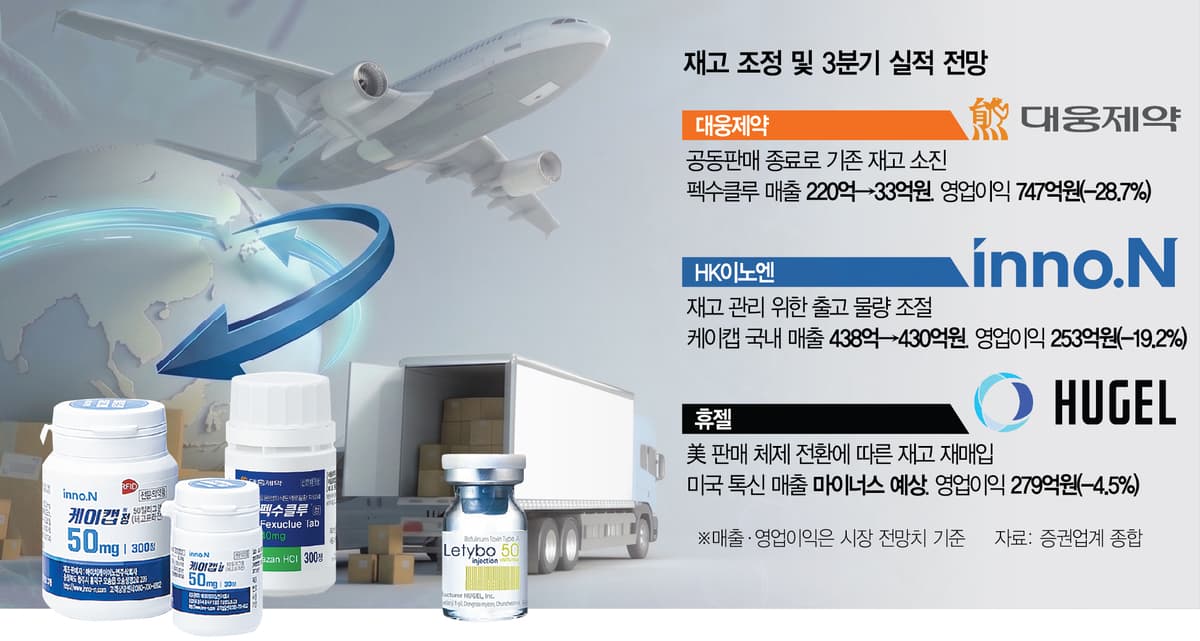
Daewoong Pharmaceutical (069620.KS) is expected to post smaller-than-expected profit growth in the third quarter because of a revenue gap at Fexuclue, its treatment for gastroesophageal reflux disease, according to industry sources on the 20th. KB Securities estimated Daewoong Pharmaceutical's third-quarter standalone revenue at 411.8 billion won and operating profit at 74.7 billion won, 4.4% and 28.7% below market consensus. Both revenue and operating profit are still expected to rise from a year earlier on strong exports of Nabota, its botulinum toxin product, but inventory adjustments at Fexuclue will cap profit growth, the brokerage said.
Fexuclue shipments were delayed in the second quarter by distributor inventory adjustments, and the slowdown is expected to continue into the third quarter as remaining stock is worked down following the end of a co-marketing arrangement with Chong Kun Dang. Fexuclue prescriptions totaled 45.5 billion won in the third quarter, up 95.9% from a year earlier, according to pharmaceutical market researcher UBIST, confirming solid demand. But with existing volumes in the distribution channel being dispensed first, Daewoong Pharmaceutical's new shipments have been limited, widening the gap between prescription volumes and actual revenue. KB Securities estimated Fexuclue revenue would fall to 3.3 billion won in the third quarter from 22 billion won in the third quarter of last year and 14 billion won in the second quarter of this year. "Once the shift to direct sales is complete, the gap between shipments and prescriptions will close," said Shin Ji-hoon, an analyst at KB Securities.
K-CAB, made by HK inno.N (195940.KQ), is also expected to see revenue decline despite rising prescriptions. Domestic prescriptions climbed to 61.5 billion won in the second quarter of this year and 65.4 billion won in the third quarter, from 56.1 billion won in the third quarter of last year. Domestic revenue recognized by the company, however, is expected to fall because of distribution inventory adjustments. IBK Investment & Securities estimated K-CAB's third-quarter domestic revenue at 43 billion won, down 1.8% from a year earlier. With royalty income also slowing on weaker sales activity in China, the brokerage expects HK inno.N's revenue and operating profit to come in at 266.6 billion won and 25.3 billion won, 2.9% and 19.2% below market consensus.
An HK inno.N official said the company periodically adjusts shipment volumes to its partner to appropriate levels because K-CAB is sold through a co-marketing arrangement. "Domestic distribution inventory adjustments for K-CAB will continue into the fourth quarter, but royalties will recover as sales in China normalize," said Jung Yi-soo, an analyst at IBK Investment & Securities.
Hugel (145020.KS) will book an inventory buyback in its third-quarter results tied to a change in its U.S. sales structure. Ahead of a full shift to direct sales in the second half of 2027, the company has converted its contract with local distributor Benev to a sales agency arrangement, repurchasing four to five months' worth of inventory. Previously, Hugel recognized revenue when it supplied products to Benev; under the agency structure, revenue will be recognized when products are sold to end customers. In the process, the inventory buyback amount will be deducted from revenue, and U.S. toxin sales are expected to turn negative in the third quarter. Higher labor costs from hiring U.S. sales staff will also weigh on results.
Hyundai Motor Securities estimated Hugel's third-quarter consolidated revenue at 104.2 billion won, down 1.6% from a year earlier, and operating profit at 27.9 billion won, down 41.1%. "U.S. toxin sales will normalize from the fourth quarter," said Kim Hyun-suk, an analyst at Hyundai Motor Securities. "After the full shift to direct sales in the second half of 2027, higher prices and market share can drive earnings growth."