
Patch Brothers, via Wikimedia Commons
- Key insight: By following its own historical example, JPMorganChase can help address the nation's affordable housing crisis and transform community reinvestment.
- Supporting data: With $5 trillion in assets, the bank's holding company, JPMorgan Chase & Co., is larger than the combined assets of the 4,100 smallest banks.
- Forward look: Using its marketing infrastructure and national reach, Chase could recognize every bank, including competitors, receiving an Outstanding CRA rating each month.
JPMorganChase has an outstanding tax bill.
Processing Content
Not imposed by Congress or collected by the IRS. And, not imposed by New York City or any other municipality.
It's a leadership tax.
This leadership tax comes with the privilege of being the dominant player in an industry where a corporate titan's responsibility goes beyond shareholders and requires ecosystem stewardship.
It not only demands a willingness to protect the industry's public standing but also a mandate to help improve industry efforts to address social problems, the biggest today being affordable housing.
My first CRA book in 1993 called this "capitalism with a corporate conscience."
With $5 trillion in assets, the bank's holding company, JPMorgan Chase & Co ., is larger than the combined assets of the 4,100 smallest banks. There are just over 4,200 banks nationwide. Controlling nearly one-fifth of industry assets and being 43% larger than its nearest competitor, Bank of America, Chase is in a leadership class of its own.
Chase's enormous scale, profitability and influence create an opportunity to do something no other American bank can do: use its unrivaled position to help transform how the industry serves low- and moderate-income communities.
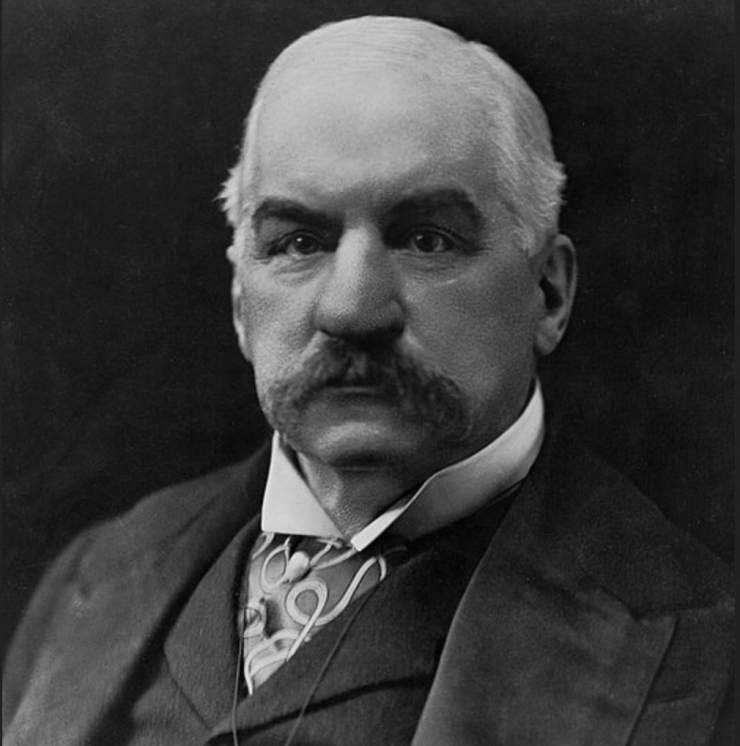
There is historical precedent for this leadership tax, coming from none other than the bank's namesake founder and architect of modern finance, J.P. Morgan.
Before the Fed's 1913 creation, he effectively acted as America's de facto central bank, leading the private rescue that stabilized the financial system during the Panic of 1907. J.P. Morgan used his financial influence to address a problem beyond his own banking interests, paying the leadership tax of his time.
That was a different century and a different crisis.
Chase is not being asked to rescue the financial system or solve the affordable housing crisis.
The ask is narrower: use its institutional resources and marketing platform to make outstanding community reinvestment performance visible, so other banks treat it as something worth doing.
By way of disclosure, I have no business or other interest in Chase besides a bank account.
Chase is uniquely positioned for this mission, not only because of its industry dominance, but because of its proven community reinvestment record.
I previously argued Chase's commitment to opening 100 new branches in underserved communities effectively made it America's largest "community bank." A community banking association disagreed, arguing that an institution of Chase's size couldn't qualify as a community bank.
This reflects two definitions of community banking. One, shared by the industry and its regulators, emphasizes size and business models. The other, mine, emphasizes what a bank actually does for its communities, measured by CRA ratings. Most of the 2% of banks with failing CRA ratings are small banks.
When Chase announced plans to open 100 branches in "banking deserts," employ local community managers, and invest in underserved communities, including the Detroit inner-city neighborhood where I was born, it demonstrated that community banking is about corporate commitment, not just size.
Chase walks the CRA walk rather than talking the CRA talk. Call it "JPMorganChase Community Bank."
Chase has a once-in-a-generation opportunity to use this record and take a leadership role by encouraging thousands of banks to make community reinvestment a priority.
Read more:
- How new payment technology puts trust at a premium
- JPMorganChase still tops AI ranking as big-bank lead widens
- Life insurers concealed $21B in private-credit risk: Lawsuit
- SBA starts new fiscal year with even tighter credit box
How exactly would Chase pay this leadership tax?
By using its enormous marketing power as it currently does with the NFL, the undisputed ratings champion of American media.
Regular-season NFL games averaged 19 million viewers in 2025, and the NFL accounted for 89 of the top 100 telecasts. Post-season and Super Bowl viewership is off the charts.
Recognizing this unparalleled reach, Chase spends millions as official sponsor of the NFL RedZone's incredibly popular "Every Touchdown" segment, replaying every touchdown from every NFL game.
Why couldn't Chase apply that same approach to community reinvestment?
Every month, federal banking regulators release CRA ratings, but only about 10% are Outstanding "touchdowns." For example, there were just seven Outstanding ratings announced in September and 10 in August.
Yet, these achievements, representing three or more years of community commitment, receive little public recognition. Some banks celebrate their own Outstanding ratings, but the rest of the industry and regulators move on.
I spent more than 30 years encouraging federal regulators to publicize Outstanding ratings through a monthly "honor roll" but got nowhere. None of the trade associations regularly highlight Outstanding ratings either. These public ratings can be reprinted by anyone, anywhere.
Forget the government and trades, and imagine a Chase-sponsored "Every CRA Touchdown" program.
Using its marketing infrastructure and national reach, Chase could recognize every bank, including competitors, receiving an Outstanding CRA rating each month.
Like the classic E.F. Hutton, when Chase talks, banks listen.
Instead of spectacular one-handed end-zone receptions or pick-sixes, this program could highlight successful affordable housing projects, first-time homebuyer programs, and other innovative approaches meeting the credit needs of underserved communities.
Highlighting its own competitors with Outstanding CRA ratings would demonstrate leadership, putting industry achievements ahead of its own. Instead of surrendering a competitive advantage, Chase would be encouraging banks to compete more visibly on community reinvestment.
Recognizing successful community development initiatives would help other institutions identify approaches worth replicating. CRA imitation is the best form of flattery.
At a time when affordable housing remains beyond the reach of millions of Americans, the public needs to know that banks, especially the winning 10%, are doing their very best to help.
Chase's CRA highlight reel, using a combination of traditional and social media, would have relatively minimal costs because it already has the marketing machinery and national platform.
By encouraging the industry to promote affordable housing in this manner, Chase would be repeating its corporate history of helping the country by doing what the government and trades have not.
Chase would be following the example of J.P. Morgan and paying its leadership tax in full.

President, K.H. Thomas Associates
Dr. Thomas is the nation's leading expert and author on the Community Reinvestment Act, or CRA. He has a Ph.D. in business and applied economics and... Read full bio