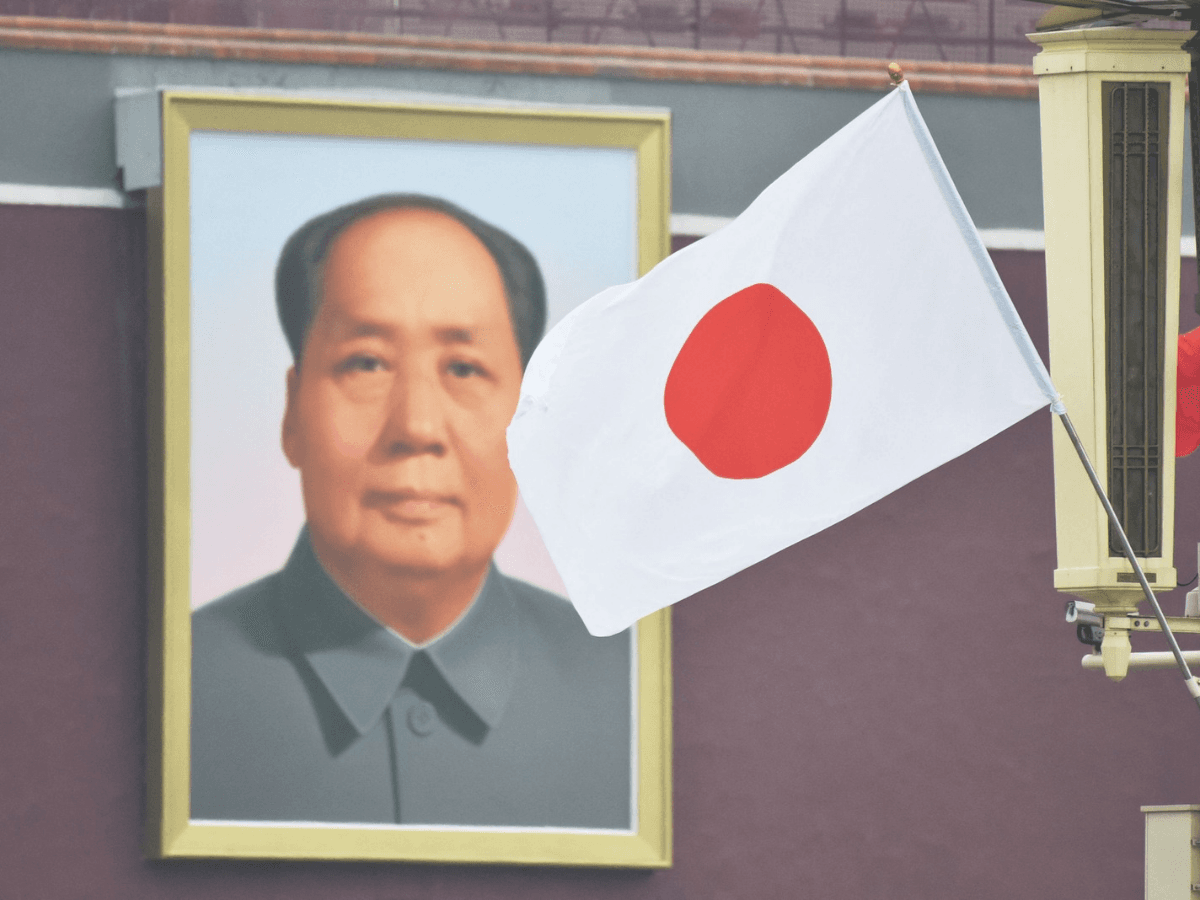
Tokyo lost decades when a property bust led to an economic slump. Could the same phenomenon undo Xi Jinping's ambitions?
Author of the article:

Xu, a semiconductor engineer in Shanghai, should feel like a master of the universe in China’s new economy. He earns well in a sector critical to the nation’s future and lavished for decades with state subsidies.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman, and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account.
- Share your thoughts and join the conversation in the comments.
- Enjoy additional articles per month.
- Get email updates from your favourite authors.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account
- Share your thoughts and join the conversation in the comments
- Enjoy additional articles per month
- Get email updates from your favourite authors
Sign In or Create an Account
Yet for all the promise on his horizon, the 29-year-old is reluctant to splash his cash. His income, in an environment of high youth unemployment, falling property values and a threadbare social security net, feels more precious by the day. An atmosphere of consumer “downgrading” and pessimism, he says, is everywhere.”I am also under more pressure now,” Xu adds, “so I’m less inclined to go out and spend.”
Such an evaporation of confidence is chillingly familiar. To Xu and millions like him, the world’s second-biggest economy increasingly resembles that of Japan during the long period of stagnation and deflation that followed the bursting of its property bubble in 1990.
Get the latest headlines, breaking news and columns.
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
A welcome email is on its way. If you don't see it, please check your junk folder.
The next issue of Top Stories will soon be in your inbox.
We encountered an issue signing you up. Please try again
The parallels are everywhere, from deteriorating demographics, persistent deflation and weak consumer spending to moribund stock and property markets. At around 300 per cent of GDP, according to calculations by Capital Economics, China’s total public and private debt is also closing in on Japanese levels.
China’s leaders have studied Japan’s experience in detail, in an effort to avoid the policy mistakes that bedevilled Tokyo’s response to the slump.
But despite their efforts, signs of Japan-style malaise, such as reluctant consumers and deflationary pressures, are still proliferating in China.
According to Goldman Sachs, an updated version of the Japanization index — a gauge originally devised by the late economist Takatoshi Ito — shows that for the past five years, China has been consistently more “Japanized” than Japan itself.
Looming over all of this is what economists describe as the iron law of demographics. Japan’s population started to shrink in 2009; China’s decline began in 2022 and is on track to be steeper, worsening the country’s economic prospects.
That outlook threatens President Xi Jinping’s reputation as a reliable steward of the economy, raising the prospect that the country will not surpass the United States to become the world’s largest economy in the next one or two decades, as some once also believed Japan might.
In another echo of Japan’s post 1990s-slump, the IMF warned last week of growing numbers of “zombie” companies across Asia, kept alive only by lenient banks. This is now evident across China’s heavily subsidised manufacturing economy.
Outside favoured sectors, companies are increasingly refusing to invest while households hoard cash instead of spending. Phrases coined in 1990s Japan, such as “job hunting ice age” and “price destruction”, are creeping into China’s vernacular.
And while economists can see the signals of Japanification in the data, Xu can see it at breakfast, lunch and dinner. Restaurants across China are competing to offer meals for under Rmb10 (US$1.50).
“The focus for customers seems to be on filling up, rather than the taste of the dishes themselves or the quality,” Xu says.
This too is redolent of Japan, where restaurants entered a margin-crushing price war to attract an ever-shrinking pool of consumer spending as deflation took hold. The price of a basic bowl of rice and beef at the nation’s leading gyudon chain hit a high of ¥400 (US$2.50 at current exchange rates) at the end of 1990 before falling. It only reached ¥400 again in 2021.
“The criticism of Japan’s response was that it was too little, too late. It was slow to take the drastic measures that were required, and reluctant to take the pain,” says Toshiya Tsugami, a fellow at the Japan Institute of International Affairs think-tank who specializes in the comparison between the Chinese and Japanese economies.
“China appears to be doing everything it can, but it is treating the symptoms only. In fact, China’s problems are getting bigger and more serious,” he adds.
Although higher energy prices as a result of the Iran war have recently lifted Chinese factory-gate prices out of more than three years of deflation, economists say weak demand continues to fester. Consumers are deleveraging, with bank lending to households as of August this year declining outright for the first time in history.
Five years on from the bursting of China’s property bubble, some economists are concerned over whether the economy is now halfway through its first “lost decade” — and whether that could extend into a second or even a third.
But others counter that the two economies are very different. Andrew Tilton, chief Asia-Pacific economist at Goldman Sachs, says that China “has been at pains to make sure its manufacturing sector stays competitive and maintains market share”. Third-quarter year-on-year GDP growth of 4.5 per cent, announced this week, was driven substantially by export growth.
China is also less developed now than Japan was when its bubble burst, leaving more room for growth, and it is more able to resist political pressure from the U.S. over exchange rates than Japan was.
Isabelle Mateos y Lago, chief economist at BNP Paribas, says that while there are parallels, these differences seem far more important. “China could reflate its domestic economy by addressing the root causes of households’ astonishingly high savings rate, which is roughly twice Japan’s in the early 1980s,” she says.
Even so, the reversal in sentiment from a decade ago is striking. “It isn’t so long ago since people were drawing lines on charts that showed China keeping on growing at seven, eight or even 10 per cent [a year] for another couple of decades,” says Adam Slater, lead economist at Oxford Economics.
“Now all of a sudden we’re looking at, within a decade, Chinese growth dropping towards three per cent per year. It’s a very big change in the outlook.”
China’s real estate bubble was the largest in history, outpacing even Japan’s speculative frenzy of the late 1980s and at its peak accounting for a third of the country’s economy.
The contraction since it burst in 2021 has been dramatic, with new housing starts down 78 per cent from their peak, according to Macquarie. That compares with a 73 per cent fall in the U.S. between 2005 and 2009 and Japan’s 65 per cent drop between 1996 and 2025.
The collapse of the property market has set off what Richard Koo, the Nomura Research Institute’s chief economist, calls a “balance sheet recession” — a term he originally coined in the 1990s to describe the tendency of Japanese companies and individuals to pay down debt rather than borrow to invest or spend.
Weaker demand and deflation then worsen the debt burden, leading to a vicious cycle. Investment opportunities decline, the labour market calcifies and salaries stagnate.
Just as it did in Japan, demand for debt has slowed markedly in China since the real estate bust. The country’s total outstanding renminbi-denominated loans rose 4.8 per cent in September from a year earlier, a record low, and down from 4.9 per cent in August.
China’s weakening economic conditions meant that up to 10.6 per cent of the adult population had overdue loans last year, compared with about 7.8 per cent a year earlier, according to a report by Gavekal Dragonomics analyst Xiaoxi Zhang.
China’s official statistics show an uncannily stable urban unemployment rate of about five per cent. But youth unemployment is high by international standards at 18.9 per cent in August.
The country’s local governments are also trying to reduce debt after borrowing hundreds of billions of dollars to finance often unproductive investments during the property boom.
The province of Guizhou alone binged about Rmb770 billion (US$115 billion) a year on large infrastructure projects between 2017 and 2023, including some of the world’s highest bridges. Now that high-spending era appears to be over.
In the private sector, companies in favoured high-tech sectors or export industries are still borrowing, but those exposed to the weak domestic economy are not.
The ultimate sign of China’s weak credit demand is the 1.7 per cent yield on 10-year government bonds, which Nomura’s Koo describes as “absolutely ridiculous”. Prices, which move inversely to yields, have risen because investors are unpersuaded by the opportunities on offer elsewhere in the country and have parked cash in government debt. The yield “should be 3 or 4 per cent at a minimum”, adds Koo.
He argues that the best response to a balance-sheet recession is increased fiscal spending by government to mobilize the savings accrued in the banking system, rather than repeating Japan’s mistake of using lower interest rates to stimulate the economy. Loose monetary policy merely encouraged companies to limp along without addressing fundamental flaws in their business models and resulted in capital misallocation, he adds.
Xi’s administration has announced some spending programs for consumption, such as subsidies for one-off purchases of consumer goods, including televisions and appliances. But these have only brought forward spending by households rather than raising incomes.
“A lot of people in China fully understand the need for fiscal stimulus but the government is still not adapting [its] stance fully,” says Koo. “It has done some, but nothing near enough to offset the deflationary pressure.”
One reason for Beijing’s reluctance to resort to domestic stimulus, economists believe, is China’s strong export performance. The trade surplus hit US$1.2 trillion last year — the biggest recorded by any country, ever — and may meet or exceed that level this year.
Policymakers in Beijing think the country’s export performance will buy China time while it waits for the property market to stabilize. In the meantime, they are pursuing investment in areas such as chipmaking and AI as the country competes with the U.S. for geopolitical dominance.
One Chinese government adviser, speaking on condition of anonymity, says the top leadership believes that its long-term investment in high-tech will bring a pay-off that was not seen after the bubble burst in Japan.
The adviser points to China’s growing capabilities in semiconductor manufacturing, an industry where Japan ceded ground to Taiwan and South Korea during its two lost decades.
“So China is different. China did this on purpose,” the adviser adds. “We did not wait until the [property] bubble burst itself — we intentionally, we proactively made this happen.”
He says Beijing is making sacrifices now, in terms of weak domestic sentiment, in exchange for the long-term benefits. “They believe that this [the property downturn] will not last very long.”
Japan’s share of global manufacturing value was 23 per cent in 1995, falling to 11 per cent in 2010. China’s share was still 28 per cent in 2024. Some economists note that since the country’s property bubble burst, China’s exporters have increased their share of global manufacturing while Japan’s fell.
“Since the onset of U.S.-China trade tensions in 2018, China’s overall exports have risen about 52 per cent, and its goods surplus has more than tripled,” said Larry Hu, chief China economist at Macquarie, in a research note.
He said that contrasted sharply with Japan, where corporate capital expenditure declined by about 14 per cent from 1990 to 2010 as companies repaired their balance sheets. “That persistent capex weakness helps explain why Japan missed much of the subsequent waves of technological change in the internet and semiconductors.”
Others caution that China’s manufacturing export boom may yet prove unsustainable as big trade partners such as the U.S. and EU push back more forcefully against the flood of cheap exports.
In 1985, when Japan’s exports were booming, it was in effect forced to rebalance its economy by allowing the yen to appreciate. The so-called Plaza Accord with the U.S. and others kept Japan’s trading partners open to receiving its goods, Koo argued.
But Chinese propaganda portrays the agreement as a capitulation. “Japan’s acquiescence was influenced as much by its security dependence on the U.S. as by economic factors, and the resulting shock triggered Japan’s asset collapse and prolonged economic stagnation,” said the official China Daily newspaper last month.
“Japan was responsive to U.S. political and policy pressure [over its weak currency] in a way China is not,” says Tilton, at Goldman Sachs. “Without the same electoral constraints, China can continue directing resources away from the household sector for longer than Japan could.”
Macquarie’s Hu argues that even if exports prove unsustainable at their current levels, Beijing still has enough fiscal firepower to stimulate consumption.
“After five years of painful adjustments, policymakers have deflated the property bubble,” he wrote. “Now, with low inflation, low rates, and an undervalued currency, they have ample policy space to pivot, such as [through] rolling out forceful housing stimulus.”
Not everyone is convinced such a shift will be easy. Just as two generations of Japanese endured the fallout from the collapse of the 1980s bubble, a generation of young Chinese people is now bearing the brunt of their country’s domestic slowdown.
Gavekal analyst Andrew Batson calculates that about 74 million Chinese have completed their education and entered the workforce since 2022.
The weak economy means many members of this “lost generation” will become disillusioned with their prospects, he argues, making it more difficult to stabilize the property market.
This psychological cloud, argue Goldman Sachs analysts, matters even more than the demographic overhang in judging how hard Japanification might hit China.
The “expectation channel”, where households and businesses saw no prospect of longer-term growth, created a vicious circle of reduced consumption and investment in Japan which in turn lowered expectations.
Zhu Ning, an economist and author of a book about China’s property bubble, says younger people “just don’t think buying a property makes economic sense or investment sense, because all [they] have experienced is that housing prices came down 30 to 40 per cent in a matter of five years.”
The stock market could offer a substitute for some households looking for investment opportunities, he adds, with about 200 million Chinese holding some shares.
But for some economists, a bigger question is whether China’s bubble has actually fully burst, given the country’s still extraordinarily high investment rates.
Gross fixed capital formation — the acquisition of assets for the production of goods and services — was 40 per cent of GDP in 2024 against Japan’s 28 per cent and the OECD average of 22 per cent, fuelled by an augmented fiscal deficit that Goldman Sachs forecasts will hit 11 per cent of GDP this year. No one knows when this debt will become unsustainable.
“I would say China hasn’t really started its adjustment yet because debt continues to rise at an astonishingly rapid pace,” says Michael Pettis, a senior fellow at the Carnegie Endowment for International Peace. “We’re going to see a surge in investment growth later on this year, because I don’t think [China’s leaders] are prepared to see GDP growth come in below target at 4 per cent.”
In Japan’s case, the adjustment started relatively clearly in 1991 after the collapse of the real estate and stock markets. “I’m not sure we’re going to have such a clean starting date with China,” adds Pettis.
Some might say China’s adjustment began in 2022 after the crackdown on housing sector over-leverage, or even as far back as 2015 when a stock market collapse led the country to cut interest rates, setting off the last phase of the housing boom. More recently, there has been a boom in manufacturing.
The seminal book Japan as Number One, published in 1979, triggered a wave of predictions that the Japanese economy would overtake that of the U.S. Such forecasts endured even after Japan had entered its first lost decade.
Similar pronouncements regarding China, which proliferated until recently, have become more scarce. If Beijing cannot shake off Japanification, the prospect of convergence with the U.S. will fade.
Slater, at Oxford Economics, does not rule out the possibility that the country’s growth slows to between two and 2.5 per cent over the next decade — half the average of the last. In that case, Xi’s hope of overtaking the U.S. might look increasingly forlorn, just as the challenge posed by Japan receded in the 1990s.
“The catch-up process would pretty much level off,” he says.
© 2026 The Financial Times Ltd

Join the Conversation
This website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more about cookies here. By continuing to use our site, you agree to our Terms of Use and Privacy Policy.