The African Union says 23 African economies do not currently have ratings from the major global agencies
NEWS ANALYSIS | THE INDEPENDENT | When the African Export-Import Bank ended its credit-rating relationship with Fitch Ratings earlier this year, it was more than a disagreement between a lender and one of the world’s biggest rating agencies.
It exposed a much bigger argument about who gets to define financial risk in Africa. Afreximbank said in January that it had terminated its relationship with Fitch because the agency’s assessment no longer reflected a proper understanding of the bank’s establishment agreement, mandate and operating model. The decision followed a series of disagreements after Fitch downgraded the pan-African lender.
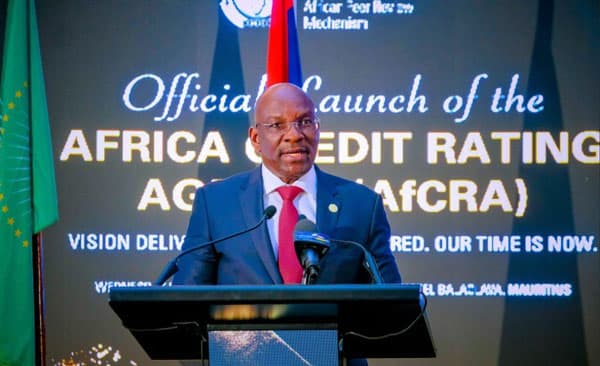
The dispute has given added significance to the launch of the Africa Credit Rating Agency (AfCRA), the African Union-backed institution officially launched in Mauritius on October 7.
AfCRA is being presented not as a replacement for Fitch, Moody’s or S&P Global, but as another source of analysis that can bring African data, expertise and economic realities more directly into the assessment of credit risk.
Africa already has rating agencies operating on the continent. Moody’s owns Global Credit Rating, while S&P Global agreed this year to acquire a majority stake in Nigeria’s Agusto & Co. There are also several other domestic and regional agencies.
So AfCRA is not entering an empty market. It is entering a market where the question is increasingly about whose methodology, data and interpretation should determine the price of African risk.
The Afreximbank-Fitch dispute
The argument became particularly visible in the case of Afreximbank. Fitch downgraded the bank in June 2025, cutting its long-term issuer default rating to BBB- from BBB and assigning it a negative outlook.
The agency cited increased credit risks, including its assessment of the bank’s non-performing loans and concerns about risk management and exposure to sovereign borrowers.
Afreximbank disputed the assessment, arguing that Fitch’s treatment did not adequately reflect the legal and institutional framework under which the bank operates.
The bank subsequently ended its relationship with Fitch in January 2026. The episode was significant because Afreximbank is itself a multilateral financial institution created by African governments and has a mandate to finance trade and economic development across the continent.
The disagreement therefore went beyond a single rating.
It raised a question that AfCRA will now have to answer: can an African institution be assessed in a way that fully captures the legal protections, shareholder structure and development mandate of African multilateral institutions?
Afreximbank’s experience also shows that different agencies can reach very different conclusions.
In June this year, S&P Global assigned Afreximbank a BBB+ investment-grade rating with a stable outlook, three notches above Fitch’s BB+ assessment after the Fitch relationship ended.
That divergence illustrates why methodologies matter.
Two international agencies can examine broadly the same institution and arrive at substantially different assessments of its risk.
African Union Commission Chairperson ,Mahmoud Ali Youssouf, said the launc of the AU backed-agency is an important milestone in Africa’s economic development, while emphasising that the agency must maintain its independence to earn the confidence of investors and financial markets.
He also cautioned that AfCRA alone would not significantly reduce Africa’s cost of capital, underscoring the need for broader reforms to address the continent’s financing challenges.
An African view of African risk
Afreximbank’s senior executive vice-president, Denys Denya, said at AfCRA’s launch that the new agency should not simply reproduce the methodologies used elsewhere.
“The rating methodology AfCRA develops must recognise the uniqueness of our environment and its institutional structures,” he said.
“The Agency must set its own standards and not follow those set elsewhere.”
But there is an important qualification. An African rating agency cannot expect investors to accept its ratings simply because it is African.
Its greatest challenge will be to establish independence and credibility. Investors will want to know whether AfCRA can downgrade an African government when its finances deteriorate, challenge an influential institution or issue an unfavourable assessment when the evidence demands it.
That is where the agency’s African ownership could become both its greatest strength and its biggest test.
Africa is not short of rating agencies
The creation of AfCRA also needs to be understood against the changing structure of Africa’s rating industry.
There are already several African agencies providing ratings, while global agencies have expanded their presence through local operations and acquisitions.
Moody’s owns GCR, one of the continent’s largest rating agencies, while S&P Global’s agreement to acquire a majority stake in Agusto & Co gives another major international agency a stronger foothold in Africa.
The market is therefore not simply divided between foreign and African institutions.
There is an increasingly interconnected rating industry in which global agencies operate alongside domestic firms.
AfCRA’s proposition is different. The African Union says it is intended to provide independent, credible and Africa-focused assessments of sovereigns, sub-sovereigns and businesses, using African data and expertise while complementing existing international agencies.
That could be particularly important in markets that remain poorly covered.
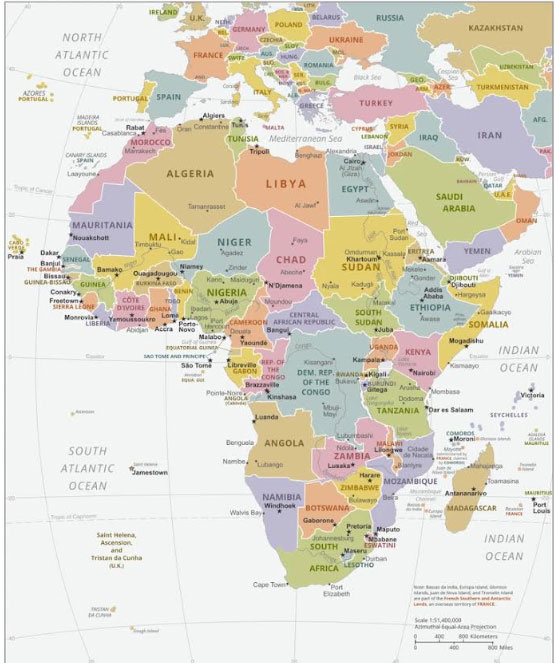
The African Union says 23 African economies do not currently have ratings from the major global agencies. That leaves governments and companies without the kind of formal credit assessment required by many international investors.
The cost of being misunderstood
The argument for AfCRA is ultimately about more than ratings. It is about the cost of capital.
Credit ratings influence how investors price debt. A lower assessment can mean higher borrowing costs, while a lack of a rating can prevent some institutions from accessing particular pools of capital altogether.
The United Nations has estimated that Africa could be losing billions of dollars each year through higher borrowing costs and missed financing opportunities linked to perceptions of risk.
African governments therefore have a strong interest in ensuring that the information used to assess them is complete and accurate.
But there is an equally important responsibility on African governments and institutions.
Better ratings cannot be created by changing the agency producing them.
Countries still need sound fiscal policies, transparent public finances, credible institutions and sustainable debt.
AfCRA’s credibility will depend partly on its willingness to say so.
The test will come with the first difficult rating
The launch in Mauritius may mark the beginning of a new chapter in Africa’s financial architecture, but it does not settle the debate over African risk.
That will happen when AfCRA begins issuing ratings and the first uncomfortable assessment arrives.
If the agency gives a lower rating to a government that supported its creation, investors will have a reason to take its independence seriously.
If its methodology identifies risks that international agencies have overlooked, it could demonstrate the value of having another voice in the market.
And if it produces ratings that appear designed to make African borrowers look better, investors may simply ignore them.
That is why Afreximbank’s dispute with Fitch is so relevant to the new agency.
The episode demonstrated that credit ratings are not simply numbers attached to bonds.
They are judgments built from data, assumptions, methodologies and an understanding of institutions.
Africa now wants to have a bigger role in making those judgments.
The challenge for AfCRA is to prove that an African perspective can also be an independent, rigorous and investable one. That is the standard by which the new agency will ultimately be judged.
The post Africa’s new credit agency faces its biggest test: winning investors’ trust appeared first on The Independent Uganda:.