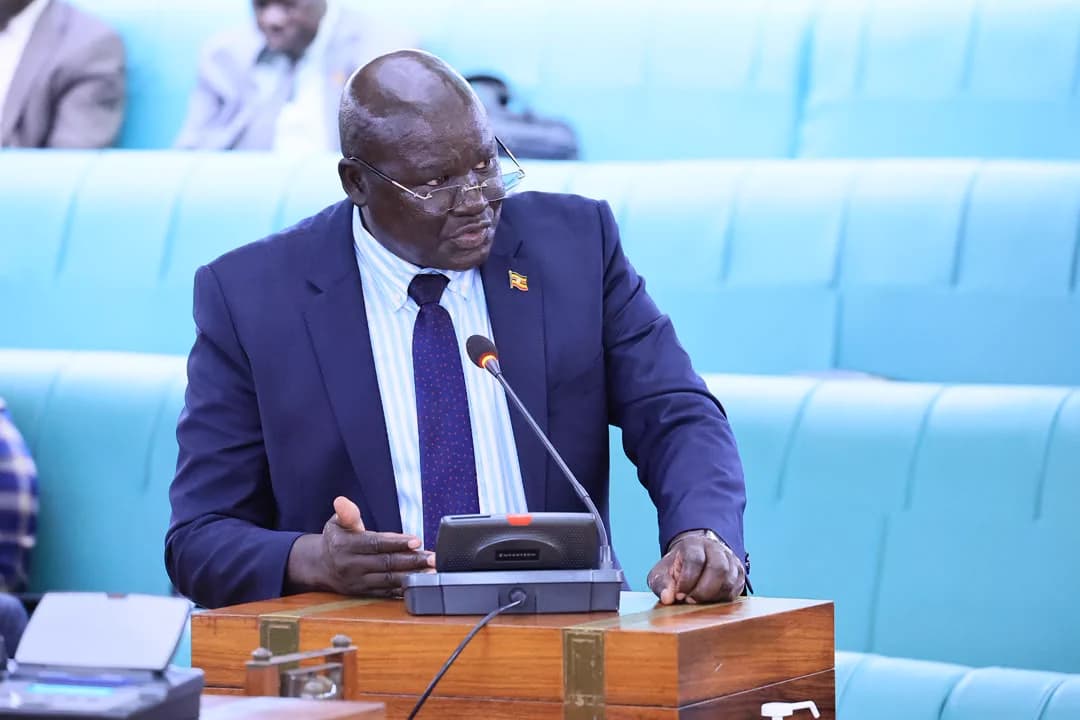
Otuke County MP Paul Omara has challenged President Museveni’s hands-off approach to the weakening Shilling, warning that falling export prices, rising import costs and foreign debt obligations could outweigh any gains from currency depreciation.
Otuke County MP Paul Omara has urged the Bank of Uganda (BoU) to take further action to stabilise the weakening Shilling, warning that rapid depreciation could fuel inflation, erode household purchasing power and increase the cost of servicing Uganda’s external debt.
In a statement released to the media on Thursday, Omara challenged President Museveni’s argument that allowing the Shilling to depreciate could benefit exporters by increasing their earnings in local currency.
His intervention came a day after BoU raised its benchmark Central Bank Rate (CBR) by 225 basis points to 12%, one of the sharpest monetary policy adjustments in more than a decade, as the central bank moved to contain rising inflationary pressures.
Governor Dr Michael Atingi-Ego defended the increase, acknowledging that tighter monetary policy could impose short- and medium-term economic costs but arguing that the central bank could not ignore mounting inflation risks.
Atingi-Ego also said the Protection of Sovereignty Act should not be singled out as the principal cause of the Shilling’s depreciation, pointing instead to global economic uncertainty, geopolitical tensions, higher international energy prices and declining foreign exchange inflows.
Omara’s statement adds to the debate over whether Uganda should allow market forces to determine the Shilling’s value or intervene to limit the economic consequences of its rapid depreciation.
Falling export earnings
Omara, a former senior banking executive, businessman and development economist, with an MBA from Cardiff University, argued that a weaker Shilling does not automatically translate into higher export earnings, particularly when international commodity prices are falling and production cannot quickly increase to compensate.
Using coffee as an example, he said the price of a kilogramme of fair average quality coffee had declined from about $5.10 last year to $3.60 this year, a fall of approximately 28%.
He estimated that if Uganda exported the same eight million bags, earnings would decline from $2.4 billion to $1.72 billion, leaving the country with about $680 million less in dollar receipts.
Converting the reduced earnings at Shs4,035 per dollar would generate approximately Shs6.94 trillion, compared with Shs8.88 trillion from $2.4 billion converted at Shs3,700 per dollar, according to his calculations.
Omara said falling commodity prices could outweigh the apparent gains from currency depreciation, especially when exporters could not rapidly increase production.
Inflation and household costs
Omara warned that depreciation was raising the cost of imported medicines, petroleum products, machinery and industrial inputs, with businesses likely to pass additional costs on to consumers.
Citing figures in his statement, he said headline inflation had risen to 4.6% from 4.1% in August, while petrol prices had increased by 30.9% year-on-year and diesel by 42.5%.
He warned that inflation could exceed the government’s 5% target, putting further pressure on interest rates and the cost of credit.
BoU’s decision to raise the CBR to 12% on Wednesday reflects the central bank’s response to inflationary pressures. Higher rates are intended to make borrowing more expensive and moderate demand, although they can also increase lending costs for businesses and households.
Omara said ordinary Ugandans on fixed incomes would suffer as prices rose faster than their earnings, reducing the amount of food, fuel and other essentials they could afford.
External debt burden
The legislator further warned that depreciation was increasing the Shilling cost of servicing Uganda’s foreign-currency debt.
Citing the Ministry of Finance’s June 2026 debt bulletin, published in September, Omara put total public debt at Shs136.06 trillion, equivalent to $37.12 billion, with external debt accounting for Shs59.74 trillion.
He estimated that converting the same $16.3 billion in external debt at Shs4,035 per dollar, rather than Shs3,665, would raise its local-currency value from Shs59.74 trillion to approximately Shs65.77 trillion.
That represents an increase of about Shs6.03 trillion in the Shilling equivalent without the government borrowing additional dollars, he argued.
He also estimated that servicing $1.38 billion in external principal and interest payments budgeted for the 2026/27 financial year would cost approximately Shs5.57 trillion at the current exchange rate, compared with Shs5.06 trillion at Shs3,665 per dollar.
The additional Shs510 billion, he said, would place further pressure on the national budget.
Omara proposes coordinated action
Omara said BoU’s monetary measures would have limited impact if government continued to spend heavily and borrow domestically, calling for a coordinated response between the central bank and the Ministry of Finance.
He urged BoU to deploy its available tools to stabilise the currency, including carefully considered foreign exchange intervention and measures to manage liquidity.
However, Wednesday’s increase to a 12% CBR has overtaken the statement’s earlier proposal to raise the rate to 10.25% or 11%.
On the fiscal side, Omara proposed cutting non-essential government expenditure, reducing domestic borrowing, reviewing low-priority capital projects and widening the tax base by reconsidering tax exemptions rather than increasing tax rates.
He also called for investment in irrigation and agricultural inputs to increase food supplies and moderate prices, alongside targeted relief on selected fuel taxes or electricity costs for manufacturers.
Another proposal was to require exporters to repatriate 30% of their foreign exchange earnings, which he argued could increase the supply of dollars in the domestic market. Such a measure would require careful assessment of its legal and economic implications.
Omara maintained that allowing rapid depreciation was unwise when major export prices were falling, inflation was rising and a substantial share of public debt was denominated in foreign currencies.
He urged BoU and the Ministry of Finance to coordinate their responses, warning that potential gains for exporters could be outweighed by expensive imports, declining household purchasing power and rising debt-servicing costs.
The challenge facing policymakers is to contain inflation and exchange-rate instability without unnecessarily constraining credit, investment and economic growth.