African companies are reporting strong revenue growth, but fewer chief executives expect sustained earnings gains over the next three years than their global counterparts, highlighting the challenges of translating higher sales into long-term profitability.
Read also:Partnerships for lasting impact: Why West Africa needs Rotary to think beyond projects
The 2026 KPMG Africa CEO Outlook, released on Thursday, found that 86 percent of African CEOs reported revenue growth in their latest financial year, but only 58 percent expect annual earnings growth of at least 2.5 percent over the next three years, compared with 68 percent globally.
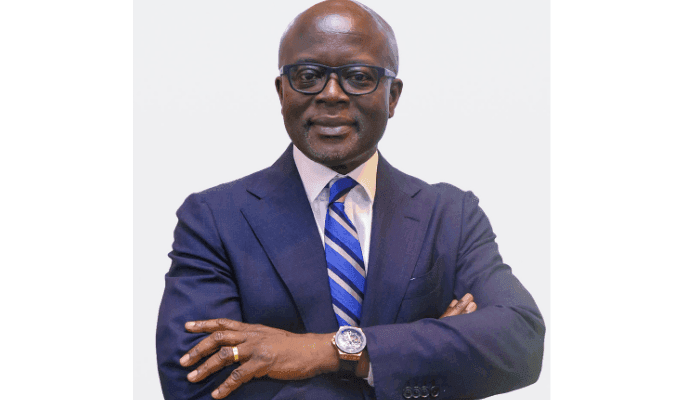
“African businesses are demonstrating confidence in their ability to grow, but the next phase of growth will require more than ambition,” said Tola Adeyemi, senior partner and chief executive officer of KPMG One Africa.
Leaders must make deliberate investment decisions, strengthen resilience and build organisations capable of adapting to disruption, Adeyemi said, adding that Africa’s resources, markets and entrepreneurial capacity could support more productive, competitive and sustainable businesses.
The findings point to a gap between recent business performance and future earnings expectations as companies navigate economic uncertainty, supply-chain disruptions, cybersecurity threats and technological change.
Read also: Nigeria targets African capital hub status with new listing rules
Despite the weaker earnings outlook, confidence remains relatively strong. About 66 percent of African CEOs expressed confidence in the global economy, close to the global average of 65 percent. Confidence in domestic economies stood at 72 percent, while 79 percent were confident in the growth prospects of their own organisations.
AI readiness lags global peers
Artificial intelligence (AI) emerged as a major challenge for African businesses, with companies lagging global peers in their readiness to keep pace with technological developments.
Although 72 percent of African CEOs identified AI as a top investment priority, only 14 percent said their organisations were keeping pace with or moving ahead of AI developments, compared with 66 percent globally.
The gap highlights the challenge of turning investment ambitions into operational capabilities. Expectations for returns also differ: 48 percent of African CEOs expect AI investments to deliver returns within one to three years, compared with 71 percent globally.
Meanwhile, 42 percent expect returns to take more than three years, against 12 percent of global CEOs.
The report points to the need for businesses to strengthen data infrastructure, governance and workforce capabilities to deploy AI effectively and improve productivity.
Cybersecurity and data security, alongside supply-chain resilience, were identified as the leading threats to growth, each cited by 31 percent of African CEOs. The integration of AI into business operations followed at 27 percent.
In response, 45 percent said they were increasing investment in cybersecurity and digital-risk resilience, while 36 percent were prioritising regulatory compliance and reporting. Another 31 percent were increasing investment in AI integration.
Workforce and sustainability priorities
Despite growing investment in AI, African companies expect to expand their workforces. About 84 percent of CEOs anticipate an increase in headcount over the next three years, compared with 89 percent globally.
Some 86 percent intend to retain and retrain high-potential employees, while 82 percent are redesigning roles, career paths and team structures to support collaboration between workers and AI systems.
However, skills shortages remain a constraint. About 59 percent identified workforce skills gaps as a challenge, while 58 percent cited AI upskilling and training and 52 percent pointed to difficulties attracting and retaining talent.
African businesses are also making progress in sustainability reporting. The proportion of CEOs who said their organisations had the capabilities to meet new sustainability reporting requirements rose to 65 percent in 2026 from 55 percent a year earlier.
However, only 48 percent said they were embedding sustainability more deeply into their core business strategies, compared with 63 percent globally.
Adeyemi said Africa’s growth prospects would depend on how effectively businesses worked across markets, developed talent and built the capabilities needed to compete in a changing global economy.
“The priority is to move from recognising the opportunity to executing against it, with investment decisions that strengthen resilience today while building capacity for long-term growth,” he said.
The report concludes that business confidence alone will not guarantee sustained performance. African companies will need to turn investment into measurable outcomes, manage uncertainty and strengthen their capabilities to compete in an increasingly technology-driven global economy.
Related News

Faith Omoboye is a foreign affairs correspondent with background in History and International relations. Her work focuses on African politics, diplomacy, and global governance.

