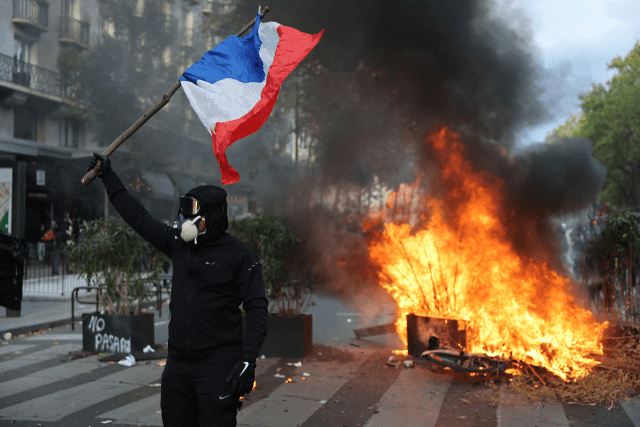
The fates of France, which failed at structural reform amid loose fiscal expansion, and Greece, which overhauled its economy through painful effort, are diverging sharply. France is now in chaos, with public order breaking down. Protests that began with high school students angry over poor education conditions spread nationwide as young people and low- and middle-income households struggling to make ends meet joined in. The government has imposed a partial curfew, and the situation has grown so uncontrollable that troops were deployed on the 24th.
France, once half of Europe's economic locomotive alongside Germany, reached this point because a flood of populist policies drained the state coffers. French retirees receive pensions equal to 70% of their pre-retirement income, far above the 55% replacement rate in Germany and Britain. That is why the country's tax burden stands at 43.5% of gross domestic product, the second highest among Organisation for Economic Co-operation and Development countries. With snowballing fiscal deficits pushing national debt to 119% of GDP, growth engines have run dry. Growth, which fell below 1% last year, is projected to shrink to 0.4% this year.
Unlike France, now cast as the "sick man of Europe," Greece, which took an International Monetary Fund bailout in 2010, is staging a comeback as "Europe's model student." The turnaround came from boldly discarding populist politics that pandered to public sentiment and devoting all its energy to strengthening the economy. Athens shored up fiscal health through pension reform and by scrapping free health care, and adopted a broad set of market-friendly policies including lower corporate and dividend income taxes, privatization of state-owned enterprises and efforts to attract foreign capital. As the foundation for growth was laid, the national debt ratio fell to 140% from 206% in 2020. It was possible because of a great decision to shake off the temptation of populism and choose the country's future.
The diverging fates of France and Greece are a cautionary lesson for a Korean economy facing a long-term slowdown in growth. They show that dragging out structural reform tasks in labor, regulation and pensions in the face of resistance from vested interests can lead to an even bigger crisis. It is also clear that the economy's fundamental strength must be built by spurring corporate investment and hiring, not by one-off cash handouts. It is time for a wise decision: whether to follow France, which took the easy path of fiscal expansion and fell gravely ill, or Greece, which succeeded in overhauling its economy through fiscal tightening and a business-friendly environment.