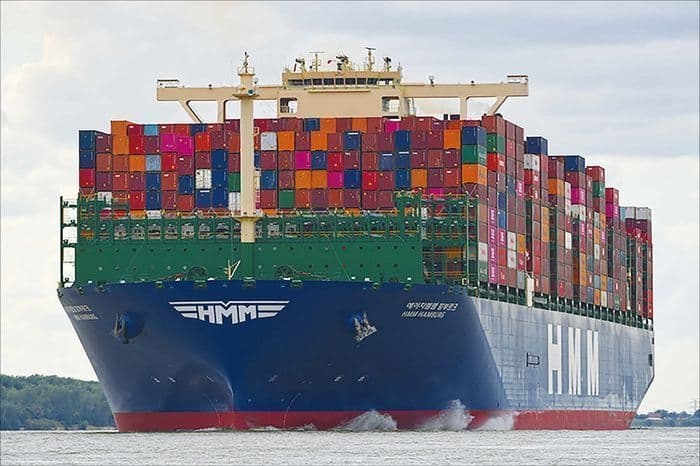
HMM (011200.KS) climbed nearly 6% in early trading on forecasts that its third-quarter earnings would far exceed market expectations. Buying interest picked up as rising container freight rates lifted near-term profit estimates and brokerages issued upbeat outlooks.
HMM was trading at 23,350 won, up 1,300 won or 5.90% from the previous session, as of 9:23 a.m. on the 14th, according to the Korea Exchange.
Shinhan Securities (008670.KS) on the same day projected HMM's third-quarter revenue at 4.08 trillion won ($2.9 billion) and operating profit at 1.0042 trillion won, up 51% and 238% respectively from a year earlier. The brokerage said operating profit would beat the market consensus by 46%. It raised its rating on the stock to buy and lifted its target price to 26,000 won.
Container freight rates are driving the earnings improvement. The Shanghai Containerized Freight Index averaged 3,407 points in the third quarter, up 130% from a year earlier, while the China Containerized Freight Index averaged 1,867 points, up 55%. Analysts attribute the increase to front-loaded shipments ahead of changes in U.S.-China tariffs and peak-season inventory building, compounded by typhoons in China, port congestion in Western markets and bottlenecks at the Panama Canal.
LS Securities (078020.KS) also forecast operating profit above 1 trillion won. The brokerage estimated HMM's third-quarter revenue at 4.2795 trillion won and operating profit at 1.0158 trillion won. Operating profit would rise 242.2% from a year earlier, about 48% above the market consensus of 686.5 billion won. LS Securities said the container division benefited from both high freight rates and improved utilization rates during the peak season on transpacific routes, while the bulk division would also gain from higher rates.
Expectations that strong earnings will expand capacity for shareholder returns are also supporting the stock. Shinhan Securities raised its full-year operating profit forecast for HMM by 42.3% to 2.498 trillion won from 1.755 trillion won, and lifted its forecast for next year by 96.8% to 1.813 trillion won from 921 billion won. LS Securities estimated HMM's cash holdings would reach about 14 trillion won by the end of this year, saying the company could secure funding for medium- to long-term growth even after special shareholder returns.
The variable is how long the shipping upturn lasts. Gains in container rates feed into earnings with a lag, which should limit any decline in profit in the fourth quarter. But a return to the Suez Canal amid shifting conditions in the Middle East and an expansion in vessel supply are cited as factors that could push rates lower. "The global container ship order backlog exceeds 40% of the existing fleet, so supply pressure will persist through 2029," said Lee Jae-hyuk, an analyst at LS Securities.
